• The Carbon Capture, Utilization, and Storage (CCUS) Market According to the latest research insights from Stellar Market Research, the global CCUS market is experiencing a paradigm shift, crossing critical valuation milestones as heavy industries accelerate decarbonization roadmaps to comply with stringent global emission frameworks.

    The global industrial landscape is undergoing a massive structural transformation, shifting from voluntary carbon-reduction pledges to mandatory, compliance-driven decarbonization. As international regulatory bodies enforce tighter carbon pricing mechanisms—such as the European Union’s Emissions Trading System (ETS) and Carbon Border Adjustment Mechanism (CBAM)—heavy-emitting sectors like power generation, cement, steel, and chemicals can no longer treat carbon management as an afterthought.

    Key Findings from the Report
    Valuation & Growth Trajectory: The global Carbon Capture, Utilization, and Storage Market is projected to exceed USD 25.3 Billion by 2033, registering a compound annual growth rate (CAGR) of 23.8% from the base year.

    Dominant Segment: The Capture service segment commands the largest market share, serving as the essential upstream entry point for all downstream utilization and permanent geologic storage workflows.

    High-Growth Industrial End-Use: The Chemicals & Petrochemicals sector stands out as a leading end-use vertical, propelled by inherent high-concentration CO2 byproduct streams and direct integration into existing petrochemical gas-separation infrastructure.

    Regional Powerhouse: North America retains the leading regional market share, heavily supported by robust federal tax credits (such as the expanded 45Q tax incentives) and well-established pipeline networks.

    Emerging Growth Epicenter: Europe is recognized as the fastest-growing regional market, catalyzed by the EU Green Deal, cross-border infrastructure projects (like Northern Lights), and rigorous carbon pricing enforcement.

    Technology Adoption Shifts: Membrane and advanced solvent-based absorption technologies are gaining rapid commercial preference over legacy systems due to lower operational footprints and superior energy efficiency.

    Investment Relevance: Venture capital and institutional investments in CCUS infrastructure projects have surged past multi-billion-dollar thresholds, attracting major energy majors and sovereign wealth funds.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/carbon-capture-utilization-storage-market/2817
    Market Drivers and Restraints
    Drivers
    Stringent Environmental Regulations and Carbon Pricing: Global implementation of rigorous carbon taxes, net-zero mandates, and emission caps compel corporations to adopt CCUS to evade heavy financial penalties.

    Lucrative Government Subsidies and Tax Credits: Generous fiscal frameworks—most notably the U.S. 45Q tax credit and European green industrial funding—significantly improve project internal rates of return (IRR).

    Corporate Net-Zero Commitments and ESG Pressures: Institutional investors and consumer markets increasingly demand verified Scope 1 and Scope 2 emission reductions, compelling heavy industries to scale up carbon capture adoption.

    Restraints
    Prohibitive Capital Expenditure (CapEx): High upfront costs associated with engineering, designing, and constructing industrial-scale capture facilities and dedicated pipeline grids can deter mid-sized market participants.

    Complex Regulatory and Permitting Bottlenecks: Lengthy approval processes for underground CO2 storage sites and cross-border transport rights frequently cause project development delays.

    Technology, Regulation, and Sustainability Trends
    The evolution of the CCUS ecosystem is fundamentally anchored in next-generation technology and regulatory convergence. Innovations in modular, scalable solid sorbents and direct air capture (DAC) systems are driving down per-ton capture costs. Simultaneously, regulatory frameworks are evolving past simple emissions reporting into liability frameworks for permanent carbon storage, ensuring long-term environmental integrity. From an ESG standpoint, integrating CCUS into heavy industrial clusters is now viewed as the ultimate corporate safeguard against stranded assets, ensuring regulatory compliance while opening doors to green-certified product premiumization.

    Regional Insights
    North America: Dominates the global landscape, underpinned by proactive federal policies, abundant enhanced oil recovery (EOR) infrastructure, and deep-pocketed energy conglomerates accelerating commercial-scale hubs in the U.S. Gulf Coast and Western Canada.

    Europe: Serves as the fastest-growing market, led by aggressive decarbonization targets in the UK, Norway, the Netherlands, and Germany. The rapid development of North Sea offshore storage formations and cross-border transport agreements is establishing Europe as a global benchmark for industrial carbon management.

    Asia-Pacific: Exhibits substantial long-term potential, led by emerging industrial hubs in India, China, and Japan, where expanding manufacturing bases are gradually implementing early-stage CCUS feasibility pilots and national carbon-trading frameworks.

    Recent Industry Developments
    ExxonMobil (2025): Expanded its low-carbon solutions portfolio by securing major industrial carbon capture and offtake agreements along the U.S. Gulf Coast, scaling regional sequestration capacity by over 5 million metric tons per annum.

    Linde plc (2025): Partnered with key clean-energy developers to engineer modular carbon capture units for chemical processing plants, reducing customer retrofitting downtime by 30%.

    Mitsubishi Heavy Industries, Ltd. (2026): Deployed its proprietary advanced KS-21 solvent technology at a commercial waste-to-energy facility in Europe, achieving record-high CO2 recovery rates exceeding 98%.

    Shell Plc (2025): Advanced construction milestones on the Northern Lights offshore CO2 transport and storage project in Norway, successfully securing cross-border industrial storage contracts across multiple European manufacturing sectors.

    Aker Solutions (2026): Secured a major engineering contract for a large-scale cement plant decarbonization project, utilizing standardized carbon capture modules to slash lifecycle operational costs.

    Competitive Landscape
    The global CCUS market features a highly competitive ecosystem populated by major oil and gas multinationals, industrial gas giants, specialized clean-tech engineering firms, and oilfield service providers. Key market leaders—including Exxon Mobil Corporation, Fluor Corporation, Linde plc, Shell Plc, Mitsubishi Heavy Industries, Ltd., Schlumberger Limited, Aker Solutions, and Honeywell International—are actively expanding their market presence through strategic joint ventures, cross-border infrastructure partnerships, and aggressive intellectual property acquisitions. Competitors are heavily focusing on modular scalability and end-to-end service integration, offering turnkey solutions from point-source capture to secure underground storage.

    Analyst Commentary
    "The carbon capture, utilization, and storage market has decisively transitioned from experimental pilot testing to a multi-billion-dollar commercial asset class," said a Senior Research Analyst at Stellar Market Research. "As regulatory compliance costs rise and green premiums take hold, industrial players can no longer view decarbonization as a compliance cost center. The companies successfully navigating the next decade will be those that treat captured carbon not as waste, but as a strategic feedstock and a core pillar of sustainable industrial profitability."

    Future Outlook
    Through the forecast period, the CCUS market is poised for exponential expansion. Driven by declining technology costs, expanding shared pipeline networks, and tightening global emissions caps, adoption is expected to branch out from oil, gas, and chemicals into hard-to-abate sectors like maritime shipping, cement, and primary steelmaking. Public-private partnerships will remain instrumental in de-risking early-stage megaprojects, ultimately embedding CCUS as an indispensable structural pillar of the global low-carbon economy.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/carbon-capture-utilization-storage-market/2817
    About Stellar Market Research
    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Address
    Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041

    Email
    [email protected]

    Mobile
    +91 9607365656
    The Carbon Capture, Utilization, and Storage (CCUS) Market According to the latest research insights from Stellar Market Research, the global CCUS market is experiencing a paradigm shift, crossing critical valuation milestones as heavy industries accelerate decarbonization roadmaps to comply with stringent global emission frameworks. The global industrial landscape is undergoing a massive structural transformation, shifting from voluntary carbon-reduction pledges to mandatory, compliance-driven decarbonization. As international regulatory bodies enforce tighter carbon pricing mechanisms—such as the European Union’s Emissions Trading System (ETS) and Carbon Border Adjustment Mechanism (CBAM)—heavy-emitting sectors like power generation, cement, steel, and chemicals can no longer treat carbon management as an afterthought. Key Findings from the Report Valuation & Growth Trajectory: The global Carbon Capture, Utilization, and Storage Market is projected to exceed USD 25.3 Billion by 2033, registering a compound annual growth rate (CAGR) of 23.8% from the base year. Dominant Segment: The Capture service segment commands the largest market share, serving as the essential upstream entry point for all downstream utilization and permanent geologic storage workflows. High-Growth Industrial End-Use: The Chemicals & Petrochemicals sector stands out as a leading end-use vertical, propelled by inherent high-concentration CO2 byproduct streams and direct integration into existing petrochemical gas-separation infrastructure. Regional Powerhouse: North America retains the leading regional market share, heavily supported by robust federal tax credits (such as the expanded 45Q tax incentives) and well-established pipeline networks. Emerging Growth Epicenter: Europe is recognized as the fastest-growing regional market, catalyzed by the EU Green Deal, cross-border infrastructure projects (like Northern Lights), and rigorous carbon pricing enforcement. Technology Adoption Shifts: Membrane and advanced solvent-based absorption technologies are gaining rapid commercial preference over legacy systems due to lower operational footprints and superior energy efficiency. Investment Relevance: Venture capital and institutional investments in CCUS infrastructure projects have surged past multi-billion-dollar thresholds, attracting major energy majors and sovereign wealth funds. For further information, click the following link:https://www.stellarmr.com/report/req_sample/carbon-capture-utilization-storage-market/2817 Market Drivers and Restraints Drivers Stringent Environmental Regulations and Carbon Pricing: Global implementation of rigorous carbon taxes, net-zero mandates, and emission caps compel corporations to adopt CCUS to evade heavy financial penalties. Lucrative Government Subsidies and Tax Credits: Generous fiscal frameworks—most notably the U.S. 45Q tax credit and European green industrial funding—significantly improve project internal rates of return (IRR). Corporate Net-Zero Commitments and ESG Pressures: Institutional investors and consumer markets increasingly demand verified Scope 1 and Scope 2 emission reductions, compelling heavy industries to scale up carbon capture adoption. Restraints Prohibitive Capital Expenditure (CapEx): High upfront costs associated with engineering, designing, and constructing industrial-scale capture facilities and dedicated pipeline grids can deter mid-sized market participants. Complex Regulatory and Permitting Bottlenecks: Lengthy approval processes for underground CO2 storage sites and cross-border transport rights frequently cause project development delays. Technology, Regulation, and Sustainability Trends The evolution of the CCUS ecosystem is fundamentally anchored in next-generation technology and regulatory convergence. Innovations in modular, scalable solid sorbents and direct air capture (DAC) systems are driving down per-ton capture costs. Simultaneously, regulatory frameworks are evolving past simple emissions reporting into liability frameworks for permanent carbon storage, ensuring long-term environmental integrity. From an ESG standpoint, integrating CCUS into heavy industrial clusters is now viewed as the ultimate corporate safeguard against stranded assets, ensuring regulatory compliance while opening doors to green-certified product premiumization. Regional Insights North America: Dominates the global landscape, underpinned by proactive federal policies, abundant enhanced oil recovery (EOR) infrastructure, and deep-pocketed energy conglomerates accelerating commercial-scale hubs in the U.S. Gulf Coast and Western Canada. Europe: Serves as the fastest-growing market, led by aggressive decarbonization targets in the UK, Norway, the Netherlands, and Germany. The rapid development of North Sea offshore storage formations and cross-border transport agreements is establishing Europe as a global benchmark for industrial carbon management. Asia-Pacific: Exhibits substantial long-term potential, led by emerging industrial hubs in India, China, and Japan, where expanding manufacturing bases are gradually implementing early-stage CCUS feasibility pilots and national carbon-trading frameworks. Recent Industry Developments ExxonMobil (2025): Expanded its low-carbon solutions portfolio by securing major industrial carbon capture and offtake agreements along the U.S. Gulf Coast, scaling regional sequestration capacity by over 5 million metric tons per annum. Linde plc (2025): Partnered with key clean-energy developers to engineer modular carbon capture units for chemical processing plants, reducing customer retrofitting downtime by 30%. Mitsubishi Heavy Industries, Ltd. (2026): Deployed its proprietary advanced KS-21 solvent technology at a commercial waste-to-energy facility in Europe, achieving record-high CO2 recovery rates exceeding 98%. Shell Plc (2025): Advanced construction milestones on the Northern Lights offshore CO2 transport and storage project in Norway, successfully securing cross-border industrial storage contracts across multiple European manufacturing sectors. Aker Solutions (2026): Secured a major engineering contract for a large-scale cement plant decarbonization project, utilizing standardized carbon capture modules to slash lifecycle operational costs. Competitive Landscape The global CCUS market features a highly competitive ecosystem populated by major oil and gas multinationals, industrial gas giants, specialized clean-tech engineering firms, and oilfield service providers. Key market leaders—including Exxon Mobil Corporation, Fluor Corporation, Linde plc, Shell Plc, Mitsubishi Heavy Industries, Ltd., Schlumberger Limited, Aker Solutions, and Honeywell International—are actively expanding their market presence through strategic joint ventures, cross-border infrastructure partnerships, and aggressive intellectual property acquisitions. Competitors are heavily focusing on modular scalability and end-to-end service integration, offering turnkey solutions from point-source capture to secure underground storage. Analyst Commentary "The carbon capture, utilization, and storage market has decisively transitioned from experimental pilot testing to a multi-billion-dollar commercial asset class," said a Senior Research Analyst at Stellar Market Research. "As regulatory compliance costs rise and green premiums take hold, industrial players can no longer view decarbonization as a compliance cost center. The companies successfully navigating the next decade will be those that treat captured carbon not as waste, but as a strategic feedstock and a core pillar of sustainable industrial profitability." Future Outlook Through the forecast period, the CCUS market is poised for exponential expansion. Driven by declining technology costs, expanding shared pipeline networks, and tightening global emissions caps, adoption is expected to branch out from oil, gas, and chemicals into hard-to-abate sectors like maritime shipping, cement, and primary steelmaking. Public-private partnerships will remain instrumental in de-risking early-stage megaprojects, ultimately embedding CCUS as an indispensable structural pillar of the global low-carbon economy. For further information, click the following link:https://www.stellarmr.com/report/req_sample/carbon-capture-utilization-storage-market/2817 About Stellar Market Research Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Address Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041 Email [email protected] Mobile +91 9607365656
    0 Comments ·0 Shares ·67 Views
  • Asia Pacific UPS Battery Market Trends Highlight Advanced Battery Technologies

    Market Estimation & Definition

    The Asia Pacific UPS Battery Market is expected to expand as businesses invest in digital infrastructure, data centers, telecommunications, and reliable power backup systems. According to Stellar Market Research, the market was valued at USD 412.18 million in 2025 and is projected to reach USD 917.63 million by 2035 , registering a compound annual growth rate (CAGR) of 9.3% during 2026–2035 .

    An uninterruptible power supply (UPS) battery provides backup electricity when the main power source fails or experiences a disruption. These batteries protect critical equipment, including servers, networking devices, industrial machinery, communication systems, and financial infrastructure. By maintaining power continuity, UPS batteries help prevent data loss, equipment damage, and costly operational interruptions. Their importance is increasing as businesses across Asia Pacific become more dependent on digital services and connected infrastructure.

    Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Asia-Pacific-UPS-Battery-Market/136

    Market Growth Drivers & Opportunity

    The rapid expansion of data centers is a major driver of the Asia Pacific UPS Battery Market. Cloud computing, online transactions, artificial intelligence infrastructure, and enterprise digitalization are increasing the need for uninterrupted power. Data centers require dependable backup systems to protect servers and maintain service availability during electrical disturbances.

    Telecommunications development is another important growth factor. The expansion of 5G networks and edge computing infrastructure is creating demand for reliable backup power at communication facilities. Banking, financial services, and insurance companies also depend on UPS systems to maintain ATMs, transaction platforms, and data-processing operations.

    Government initiatives supporting smart cities, digital public services, and modern electricity infrastructure are creating additional opportunities. However, high initial investment, battery replacement costs, maintenance requirements, and differences in infrastructure development across the region can influence adoption. Suppliers that offer reliable products, efficient battery management, and competitive lifecycle costs may be better positioned to meet demand.

    What Lies Ahead: Emerging Trends Shaping the Future

    Lithium-ion technology is expected to play an increasingly important role in UPS battery applications. Compared with traditional lead-acid batteries, lithium-ion batteries can offer lower weight, a compact footprint, faster charging, and longer service life under suitable operating conditions. These characteristics make them attractive for data centers and facilities where space efficiency and reliability are priorities.

    Modular UPS systems are also gaining attention as businesses seek scalable power protection. Modular configurations can allow facilities to expand capacity as requirements increase, helping operators manage investment and operational needs.

    The development of smart grids, cloud services, and connected industrial systems will further support demand for advanced backup solutions. Battery monitoring and management technologies can help operators track battery health, identify potential failures, and plan maintenance more effectively. Manufacturers will need to balance performance, safety, affordability, and environmental considerations as battery deployment increases.

    Get More Report Details: https://www.stellarmr.com/report/Asia-Pacific-UPS-Battery-Market/136

    Segmentation Analysis

    According to Stellar Market Research, the Asia Pacific UPS Battery Market is segmented by topology, product type, and application.

    By Topology: Online, Standby, Line Interactive.
    By Product Type: Lead-acid, Lithium-Ion, Nickel Cadmium, Others.
    By Application: Residential, Commercial, Data Center, Industrial.
    Online UPS systems provide continuous power conditioning and are suitable for equipment requiring high levels of protection. Standby and line-interactive systems offer alternatives for applications with different power protection requirements.

    Within product types, lithium-ion batteries are projected to register strong growth because of their compact design, charging performance, and potential service-life advantages. By application, data centers represent a significant opportunity as cloud computing and digital services increase demand for dependable power infrastructure. The report identifies China as the leading country in the regional market, supported by its substantial digital infrastructure and investment in technology.

    Country-Level Analysis: USA and Germany

    United States: The United States is outside the geographic scope of this Asia Pacific report, but US-based companies participate in the broader UPS battery industry. Eaton Corporation and Vertiv Group Corporation are among the key players identified by Stellar Market Research. Their power management and critical-infrastructure solutions illustrate the importance of reliable backup power for data centers and industrial facilities.

    Germany: Germany is also outside the report's geographic scope. The study does not provide a separate German market valuation or forecast. For European industry context, the report identifies international suppliers operating in the wider power protection ecosystem, including Schneider Electric, although the company is headquartered in France rather than Germany. The market analysis therefore remains focused on Asia Pacific, where China, India, Japan, South Korea, Australia, ASEAN, and the rest of the region form the report's country coverage.

    Competitive Analysis

    The Asia Pacific UPS Battery Market features established battery manufacturers, electrical equipment suppliers, and power management companies. Key players identified by Stellar Market Research include CSB Battery Co., Ltd., East Penn Manufacturing Company, Eaton Corporation plc, Exide Industries Limited, FIAMM Energy Technology SpA, GS Yuasa International Ltd., Leoch International Technology Limited Inc., Schneider Electric SE, and Vertiv Group Corporation .

    Competition is shaped by battery performance, reliability, service life, safety, pricing, and compatibility with UPS systems. Companies investing in lithium-ion technology, intelligent monitoring, and scalable backup solutions may strengthen their position as data center and industrial power requirements grow.

    Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Asia-Pacific-UPS-Battery-Market/136

    Press Release Conclusion

    The Asia Pacific UPS Battery Market is projected to reach USD 917.63 million by 2034 as digital infrastructure, data center development, telecommunications expansion, and industrial automation increase demand for dependable backup power.

    Although cost and maintenance considerations remain important, lithium-ion batteries, modular UPS systems, and advanced monitoring technologies are creating new opportunities. Manufacturers that combine reliability, efficiency, and competitive lifecycle costs will be well positioned to support the region's growing need for uninterrupted electricity.

    About Stellar Market Research:

    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Contact Stellar Market Research:

    3rd Floor, Navale IT Park, Phase 2

    Pune Banglore Highway, Narhe,

    Pune, Maharashtra 411041, India

    [email protected]

    +91 20 6630 3320 | +91 9607365656
    Asia Pacific UPS Battery Market Trends Highlight Advanced Battery Technologies Market Estimation & Definition The Asia Pacific UPS Battery Market is expected to expand as businesses invest in digital infrastructure, data centers, telecommunications, and reliable power backup systems. According to Stellar Market Research, the market was valued at USD 412.18 million in 2025 and is projected to reach USD 917.63 million by 2035 , registering a compound annual growth rate (CAGR) of 9.3% during 2026–2035 . An uninterruptible power supply (UPS) battery provides backup electricity when the main power source fails or experiences a disruption. These batteries protect critical equipment, including servers, networking devices, industrial machinery, communication systems, and financial infrastructure. By maintaining power continuity, UPS batteries help prevent data loss, equipment damage, and costly operational interruptions. Their importance is increasing as businesses across Asia Pacific become more dependent on digital services and connected infrastructure. Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Asia-Pacific-UPS-Battery-Market/136 Market Growth Drivers & Opportunity The rapid expansion of data centers is a major driver of the Asia Pacific UPS Battery Market. Cloud computing, online transactions, artificial intelligence infrastructure, and enterprise digitalization are increasing the need for uninterrupted power. Data centers require dependable backup systems to protect servers and maintain service availability during electrical disturbances. Telecommunications development is another important growth factor. The expansion of 5G networks and edge computing infrastructure is creating demand for reliable backup power at communication facilities. Banking, financial services, and insurance companies also depend on UPS systems to maintain ATMs, transaction platforms, and data-processing operations. Government initiatives supporting smart cities, digital public services, and modern electricity infrastructure are creating additional opportunities. However, high initial investment, battery replacement costs, maintenance requirements, and differences in infrastructure development across the region can influence adoption. Suppliers that offer reliable products, efficient battery management, and competitive lifecycle costs may be better positioned to meet demand. What Lies Ahead: Emerging Trends Shaping the Future Lithium-ion technology is expected to play an increasingly important role in UPS battery applications. Compared with traditional lead-acid batteries, lithium-ion batteries can offer lower weight, a compact footprint, faster charging, and longer service life under suitable operating conditions. These characteristics make them attractive for data centers and facilities where space efficiency and reliability are priorities. Modular UPS systems are also gaining attention as businesses seek scalable power protection. Modular configurations can allow facilities to expand capacity as requirements increase, helping operators manage investment and operational needs. The development of smart grids, cloud services, and connected industrial systems will further support demand for advanced backup solutions. Battery monitoring and management technologies can help operators track battery health, identify potential failures, and plan maintenance more effectively. Manufacturers will need to balance performance, safety, affordability, and environmental considerations as battery deployment increases. Get More Report Details: https://www.stellarmr.com/report/Asia-Pacific-UPS-Battery-Market/136 Segmentation Analysis According to Stellar Market Research, the Asia Pacific UPS Battery Market is segmented by topology, product type, and application. By Topology: Online, Standby, Line Interactive. By Product Type: Lead-acid, Lithium-Ion, Nickel Cadmium, Others. By Application: Residential, Commercial, Data Center, Industrial. Online UPS systems provide continuous power conditioning and are suitable for equipment requiring high levels of protection. Standby and line-interactive systems offer alternatives for applications with different power protection requirements. Within product types, lithium-ion batteries are projected to register strong growth because of their compact design, charging performance, and potential service-life advantages. By application, data centers represent a significant opportunity as cloud computing and digital services increase demand for dependable power infrastructure. The report identifies China as the leading country in the regional market, supported by its substantial digital infrastructure and investment in technology. Country-Level Analysis: USA and Germany United States: The United States is outside the geographic scope of this Asia Pacific report, but US-based companies participate in the broader UPS battery industry. Eaton Corporation and Vertiv Group Corporation are among the key players identified by Stellar Market Research. Their power management and critical-infrastructure solutions illustrate the importance of reliable backup power for data centers and industrial facilities. Germany: Germany is also outside the report's geographic scope. The study does not provide a separate German market valuation or forecast. For European industry context, the report identifies international suppliers operating in the wider power protection ecosystem, including Schneider Electric, although the company is headquartered in France rather than Germany. The market analysis therefore remains focused on Asia Pacific, where China, India, Japan, South Korea, Australia, ASEAN, and the rest of the region form the report's country coverage. Competitive Analysis The Asia Pacific UPS Battery Market features established battery manufacturers, electrical equipment suppliers, and power management companies. Key players identified by Stellar Market Research include CSB Battery Co., Ltd., East Penn Manufacturing Company, Eaton Corporation plc, Exide Industries Limited, FIAMM Energy Technology SpA, GS Yuasa International Ltd., Leoch International Technology Limited Inc., Schneider Electric SE, and Vertiv Group Corporation . Competition is shaped by battery performance, reliability, service life, safety, pricing, and compatibility with UPS systems. Companies investing in lithium-ion technology, intelligent monitoring, and scalable backup solutions may strengthen their position as data center and industrial power requirements grow. Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Asia-Pacific-UPS-Battery-Market/136 Press Release Conclusion The Asia Pacific UPS Battery Market is projected to reach USD 917.63 million by 2034 as digital infrastructure, data center development, telecommunications expansion, and industrial automation increase demand for dependable backup power. Although cost and maintenance considerations remain important, lithium-ion batteries, modular UPS systems, and advanced monitoring technologies are creating new opportunities. Manufacturers that combine reliability, efficiency, and competitive lifecycle costs will be well positioned to support the region's growing need for uninterrupted electricity. About Stellar Market Research: Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Contact Stellar Market Research: 3rd Floor, Navale IT Park, Phase 2 Pune Banglore Highway, Narhe, Pune, Maharashtra 411041, India [email protected] +91 20 6630 3320 | +91 9607365656
    0 Comments ·0 Shares ·390 Views
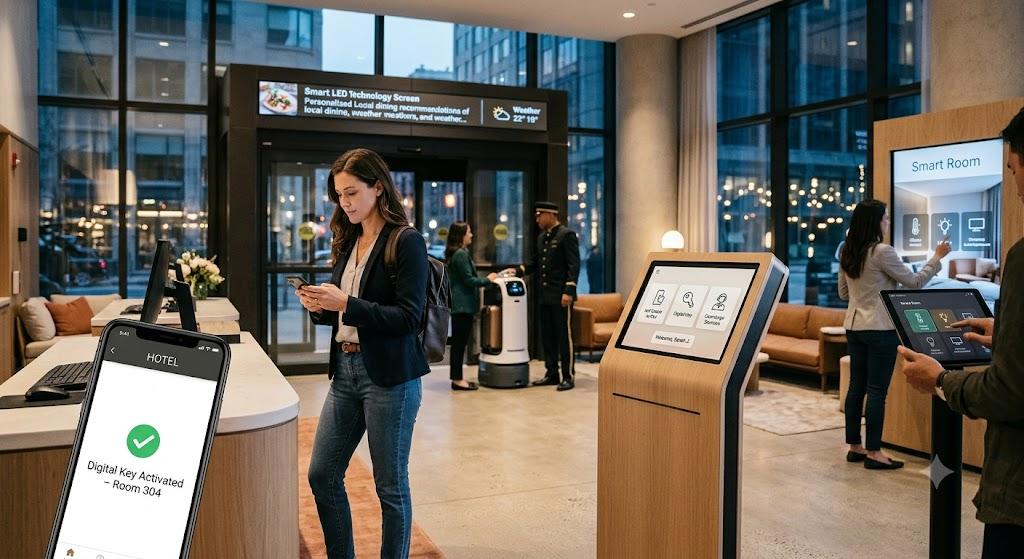
  • Smart Hospitality Market Digital Transformation and Automation Trends Report by MMR

    Unveiling the Latest Trends in the Smart Hospitality Market

    Maximize Market Research, a leading business consultancy firm, has released a comprehensive analysis of the Smart Hospitality Market. The report offers valuable business insights, including demand and pricing analysis, as well as an overview of the competitive landscape. It provides a detailed examination of the current state of the Smart Hospitality market, with projections extending through 2032

    Unlock more insights—request a free sample report now :https://www.maximizemarketresearch.com/request-sample/13824/

    Defining the Smart Hospitality Market Scope Through Comprehensive Research

    The Smart Hospitality market research delivers an in-depth analysis of key factors influencing industry growth, along with potential challenges that may arise. It provides stakeholders with a comprehensive understanding of the competitive landscape, including insights into leading companies, their product offerings, and emerging investment opportunities within the market. The report integrates both qualitative and quantitative insights, offering a well-rounded perspective on the industry’s current and future trajectory. Additionally, the MMR report includes a detailed competitive analysis, examining market players, their strategies, and key trends shaping the industry. The research is based on a blend of primary and secondary data sources, such as government publications, company websites, annual reports, and expert opinions from industry professionals and academics. Furthermore, the report identifies new market demands and trends, providing a thorough explanation of their impact on the Smart Hospitality market’s evolution. By addressing consumer preferences, regulatory frameworks, and technological advancements, the study equips businesses with actionable insights to navigate the industry’s dynamic landscape effectively.

    Explore Regional Insights and Market Dynamics in the Smart Hospitality Industry

    This report provides an in-depth regional analysis, covering essential aspects such as market size, growth rate, and trade activities, including imports and exports across different regions. By examining the geographic distribution of the Smart Hospitality market, the study offers a clear understanding of industry trends and market conditions in various countries.

    The Smart Hospitality market spans across North America, Europe, Asia Pacific, Latin America, Africa, and the Middle East, with each region presenting unique opportunities and challenges. This comprehensive analysis helps businesses identify regional growth potential, competitive landscapes, and key market drivers, enabling strategic decision-making in a dynamic global market

    Unlock the Key Market Segments Powering Smart Hospitality Industry Growth :

    The Global Smart Hospitality Market is expected to grow from USD 56.77 billion in 2025 to USD 225.64 billion by 2034, at a CAGR of 16.57% during the forecast period.

    Gain more details with a free sample report. Inquire now :https://www.maximizemarketresearch.com/request-sample/13824/

    Breaking Down the Smart Hospitality Market: Key Segments Shaping the Industry


    by Component

    Solution
    Services

    by Solution Type

    Hotel Operation Management
    Hotel Automation Management
    Guest Service Management System
    Security Management System
    Others

    by Deployment Mode

    On-Premise
    Cloud

    by End-User

    Hotels
    Cruises
    Luxury Yachts
    Others

    Meet the Industry Leaders Revolutionizing the Smart Hospitality Market

    Global

    1. IBM Corporation (United States)
    2. Schneider Electric (France)
    3. Siemens AG (Germany)
    4. Honeywell International (United States)
    5. Cisco Systems, Inc. (United States)
    6. Oracle Corporation (United States)
    7. Huawei Technologies (China)
    8. NEC Corporation (Japan)
    9. SAMSUNG (South Korea)
    10. Qualsoft Systems Pvt. Ltd. (India)
    11. Control4Corporation (United States)
    12. Cloudbeds (United States)
    North America
    1. BuildingIQ (United States)
    2. Johnson Controls (United States)
    3. Infor, Inc. (United States)
    4. WiSuite (United States)
    5. Frontdesk (United States)
    Europe
    1.Winhotel Solutions (Spain)
    2. BLAZON HOTELS (Dubai)
    3.Guestline (United Kingdom)

    Uncover Key Insights Answering the Biggest Questions in the Smart Hospitality Market

    What is Smart Hospitality ?
    What is the growth rate of the Smart Hospitality Market?
    Which are the factors expected to drive the Smart Hospitality market growth?
    What is the CAGR at which the Smart Hospitality market will grow during the forecast period?
    What are the different segments of the Smart Hospitality Market?
    Which is the fastest growing region in the Smart Hospitality market?
    What growth strategies are the players considering to increase their presence in Smart Hospitality ?
    What are the upcoming opportunities and trends for the Smart Hospitality Market?
    What are the recent industry trends that can be implemented to generate additional revenue streams for the Smart Hospitality Market?
    Who are the leading companies and what are their portfolios in Smart Hospitality Market?
    What segments are covered in the Smart Hospitality Market?
    Who are the key players in the Smart Hospitality market?
    Gain a Competitive Edge – Access Market Insights Through the Sample Link @https://www.maximizemarketresearch.com/market-report/smart-hospitality-market/13824/

    Explore the Revolutionary Products Powering Market Success

    Past Size and Competitive Landscape
    Past Pricing and price curve by region
    Size, Share, Size Forecast by different segment
    Dynamics Growth Drivers, Restraints, Opportunities, and Key Trends by Region
    Segmentation A detailed analysis by segment with their sub-segments and Region
    Competitive Landscape Profiles of selected key players by region from a strategic perspective
    Explore Our Trending Reports to Stay Ahead of Industry Shifts :

    Global Oxyfluorfen Market https://www.maximizemarketresearch.com/market-report/global-oxyfluorfen-market/81643/
    Global Windproof Lighter Market https://www.maximizemarketresearch.com/market-report/global-windproof-lighter-market/69909/
    Global Organic Baby Shampoo Market https://www.maximizemarketresearch.com/market-report/global-organic-baby-shampoo-market/72693/

    Connect with Maximize Market Research for Expert Insights In-Depth Analysis :

    +91 9607365656

    [email protected]
    Smart Hospitality Market Digital Transformation and Automation Trends Report by MMR Unveiling the Latest Trends in the Smart Hospitality Market Maximize Market Research, a leading business consultancy firm, has released a comprehensive analysis of the Smart Hospitality Market. The report offers valuable business insights, including demand and pricing analysis, as well as an overview of the competitive landscape. It provides a detailed examination of the current state of the Smart Hospitality market, with projections extending through 2032 Unlock more insights—request a free sample report now :https://www.maximizemarketresearch.com/request-sample/13824/ Defining the Smart Hospitality Market Scope Through Comprehensive Research The Smart Hospitality market research delivers an in-depth analysis of key factors influencing industry growth, along with potential challenges that may arise. It provides stakeholders with a comprehensive understanding of the competitive landscape, including insights into leading companies, their product offerings, and emerging investment opportunities within the market. The report integrates both qualitative and quantitative insights, offering a well-rounded perspective on the industry’s current and future trajectory. Additionally, the MMR report includes a detailed competitive analysis, examining market players, their strategies, and key trends shaping the industry. The research is based on a blend of primary and secondary data sources, such as government publications, company websites, annual reports, and expert opinions from industry professionals and academics. Furthermore, the report identifies new market demands and trends, providing a thorough explanation of their impact on the Smart Hospitality market’s evolution. By addressing consumer preferences, regulatory frameworks, and technological advancements, the study equips businesses with actionable insights to navigate the industry’s dynamic landscape effectively. Explore Regional Insights and Market Dynamics in the Smart Hospitality Industry This report provides an in-depth regional analysis, covering essential aspects such as market size, growth rate, and trade activities, including imports and exports across different regions. By examining the geographic distribution of the Smart Hospitality market, the study offers a clear understanding of industry trends and market conditions in various countries. The Smart Hospitality market spans across North America, Europe, Asia Pacific, Latin America, Africa, and the Middle East, with each region presenting unique opportunities and challenges. This comprehensive analysis helps businesses identify regional growth potential, competitive landscapes, and key market drivers, enabling strategic decision-making in a dynamic global market Unlock the Key Market Segments Powering Smart Hospitality Industry Growth : The Global Smart Hospitality Market is expected to grow from USD 56.77 billion in 2025 to USD 225.64 billion by 2034, at a CAGR of 16.57% during the forecast period. Gain more details with a free sample report. Inquire now :https://www.maximizemarketresearch.com/request-sample/13824/ Breaking Down the Smart Hospitality Market: Key Segments Shaping the Industry by Component Solution Services by Solution Type Hotel Operation Management Hotel Automation Management Guest Service Management System Security Management System Others by Deployment Mode On-Premise Cloud by End-User Hotels Cruises Luxury Yachts Others Meet the Industry Leaders Revolutionizing the Smart Hospitality Market Global 1. IBM Corporation (United States) 2. Schneider Electric (France) 3. Siemens AG (Germany) 4. Honeywell International (United States) 5. Cisco Systems, Inc. (United States) 6. Oracle Corporation (United States) 7. Huawei Technologies (China) 8. NEC Corporation (Japan) 9. SAMSUNG (South Korea) 10. Qualsoft Systems Pvt. Ltd. (India) 11. Control4Corporation (United States) 12. Cloudbeds (United States) North America 1. BuildingIQ (United States) 2. Johnson Controls (United States) 3. Infor, Inc. (United States) 4. WiSuite (United States) 5. Frontdesk (United States) Europe 1.Winhotel Solutions (Spain) 2. BLAZON HOTELS (Dubai) 3.Guestline (United Kingdom) Uncover Key Insights Answering the Biggest Questions in the Smart Hospitality Market What is Smart Hospitality ? What is the growth rate of the Smart Hospitality Market? Which are the factors expected to drive the Smart Hospitality market growth? What is the CAGR at which the Smart Hospitality market will grow during the forecast period? What are the different segments of the Smart Hospitality Market? Which is the fastest growing region in the Smart Hospitality market? What growth strategies are the players considering to increase their presence in Smart Hospitality ? What are the upcoming opportunities and trends for the Smart Hospitality Market? What are the recent industry trends that can be implemented to generate additional revenue streams for the Smart Hospitality Market? Who are the leading companies and what are their portfolios in Smart Hospitality Market? What segments are covered in the Smart Hospitality Market? Who are the key players in the Smart Hospitality market? Gain a Competitive Edge – Access Market Insights Through the Sample Link @https://www.maximizemarketresearch.com/market-report/smart-hospitality-market/13824/ Explore the Revolutionary Products Powering Market Success Past Size and Competitive Landscape Past Pricing and price curve by region Size, Share, Size Forecast by different segment Dynamics Growth Drivers, Restraints, Opportunities, and Key Trends by Region Segmentation A detailed analysis by segment with their sub-segments and Region Competitive Landscape Profiles of selected key players by region from a strategic perspective Explore Our Trending Reports to Stay Ahead of Industry Shifts : Global Oxyfluorfen Market https://www.maximizemarketresearch.com/market-report/global-oxyfluorfen-market/81643/ Global Windproof Lighter Market https://www.maximizemarketresearch.com/market-report/global-windproof-lighter-market/69909/ Global Organic Baby Shampoo Market https://www.maximizemarketresearch.com/market-report/global-organic-baby-shampoo-market/72693/ Connect with Maximize Market Research for Expert Insights In-Depth Analysis : +91 9607365656 [email protected]
    0 Comments ·0 Shares ·119 Views
  • Stellar Market Research, a premier market intelligence and business consulting firm, has released an in-depth strategic analysis report on the Nutricosmetics Market. The comprehensive study evaluates current dynamics, shifts in consumer behavior, and technological catalysts transforming the global landscape. According to the report, the market was valued at USD 7.69 billion in 2025 and is projected to scale to USD 15.34 billion by 2034, registering a robust compound annual growth rate (CAGR) of approximately 7.9% to 8.31% over the forecast period.

    The convergence of personal care, dermatology, and nutraceutical science has catalyzed a paradigm shift in how consumers approach anti-aging and daily beauty regimens. Moving beyond topical cosmetics, the global market is experiencing unprecedented demand for ingestible solutions that target skin elasticity, hair vitality, and nail strength at a cellular level. This structural transformation is heavily propelled by heightened consumer literacy regarding holistic wellness, preventative health, and the limitations of surface-level cosmetic treatments.

    Key Findings from the Report

    Market Valuation & Growth Trajectory: The global nutricosmetics market, valued at USD 7.69 billion in 2025, is on a high-growth trajectory, poised to reach USD 15.34 billion by 2034, expanding at a steady CAGR of ~7.9% to 8.31%.

    Dominant Product & Segment Share: Dietary supplements (capsules, tablets, and powders) lead product-type demand, capturing over 60% of the market share due to consumer familiarity, ease of precise dosing, and seamless integration into daily wellness routines.

    Application Insights: Skin care applications hold the largest revenue share, driven by surging consumer preference for anti-aging, hydration, and UV-protection ingestibles, while hair care emerges as the fastest-growing application category.

    Ingredient Leadership: Collagen peptides dominate the active ingredient base, capturing a dominant share supported by strong consumer awareness surrounding skin matrix support and joint-beauty synergies.

    Leading Geographic Hub: North America commands the largest regional revenue share, anchored by advanced retail channels, high disposable incomes, and robust regulatory oversight by the FDA that bolsters consumer confidence.

    Fastest-Growing Region: Asia-Pacific is projected to record the highest regional CAGR through the forecast period, powered by deeply entrenched cultural traditions of functional foods and preventive health in Japan and South Korea.

    Distribution Channel Evolution: Online retail channels represent the primary sales avenue, fueled by direct-to-consumer (D2C) subscription models, digital beauty education, and targeted social media marketing.

    For further information, click the following link: https://www.stellarmr.com/report/req_sample/Nutricosmetics-Market/2625
    Market Drivers and Restraints
    Drivers
    Rising Consumer Preference for Preventive Health & Wellness: A cultural shift toward proactive self-care has accelerated consumer willingness to invest in ingestible beauty products that promise long-term systemic benefits over quick fixes.

    Advancements in Bioactive Extraction & Delivery Systems: Innovations in bioavailability—such as advanced hydrolyzed peptides, liposomal delivery, and biomimetic ingredients—are substantially enhancing product efficacy and consumer results.

    Proliferation of D2C Subscription Models & Digital Personalization: E-commerce platforms and AI-driven skin diagnostic tools allow brands to offer tailored supplement regimens, successfully lowering adoption friction and driving repeat purchases.

    Restraints
    Strict and Fragmented Regulatory Frameworks: Navigating cross-border compliance regarding health claims, ingredient approvals (such as novel foods in Europe), and substantiating beauty-from-within claims presents a significant hurdle for market entrants.

    High Price Points for Premium Formulations: Premium clinical ingredients and specialized manufacturing processes often result in elevated retail price points, limiting market penetration among price-sensitive consumer segments.

    Technology, Regulation, and Sustainability Trends
    The nutricosmetics sector is undergoing a profound operational transformation driven by technology and sustainability. Artificial intelligence and mobile diagnostic apps are increasingly utilized to analyze individual skin metrics and deliver customized supplement formulations. Concurrently, regulatory bodies are enforcing stricter documentation standards for substantiating skin and hair health claims, compelling brands to invest heavily in clinical trials.

    On the environmental front, sustainability (ESG) has become a core competitive differentiator. Manufacturers are rapidly transitioning to eco-friendly packaging—such as paper-based canisters and biodegradable pouches—and adopting traceable, ethically sourced marine and plant-derived ingredients to satisfy eco-conscious consumers.

    Regional Insights
    North America: Maintaining a dominant regional market share, North America benefits from robust venture capital activity, widespread adoption of personalized nutrition, and mainstream retail expansion into metabolic and inner-beauty aisles.

    Asia-Pacific: Poised for the fastest regional growth, Asia-Pacific thrives on mature consumer habits in Japan and South Korea, where fermented botanicals, collagen drinks, and functional foods are deeply woven into daily lifestyle and heritage routines.

    Europe: Driven by stringent European Food Safety Authority (EFSA) standards, Europe prioritizes clean-label transparency, rigorous product safety, and aggressive corporate sustainability mandates.

    Recent Industry Developments
    L'Oréal (2026): Entered the nutricosmetics space with the launch of Vichy Laboratories Liftactiv Collagen Supplements, designed to support cellular health and natural collagen synthesis for both men and women.

    Solabia Group (2026): Completed the strategic acquisition of Mibelle Biochemistry in July 2026, expanding its biotech-oriented active ingredient portfolio and accelerating formulation capabilities for global beauty brands.

    TOSLA & Geltor (2026): Partnered to launch the Signaling Collagen liquid shot, a vegan-certified ingestible featuring biomimetic type 21 signaling collagen polypeptides to improve skin architecture.

    Nutrafol (2026): Expanded its life-stage product portfolio with the launch of the Men 50+ Hair Growth Nutraceutical, addressing targeted hair-thinning pathways in aging demographics.

    Amway / Nutrilite (2026): Won the Cellular Longevity from Within category at INNOCOS for its CelAct Cellular Aging Support formulation, highlighting the industry's pivot toward cellular health innovations.

    Competitive Landscape
    The global nutricosmetics market features a dynamic mix of established multinational health-science conglomerates, specialized beauty giants, and agile direct-to-consumer disruptors. Leading players are focusing on strategic mergers, biotech acquisitions, and clean-label product extensions to capture market share. Key market participants include Nestlé Health Science, Shiseido Company, L'Oréal, Amway (Nutrilite), Solabia Group (Mibelle Biochemistry), Nutrafol, and Ritual, among others. Competitive advantage increasingly relies on clinical validation, transparent sourcing, and personalized digital subscription ecosystems.

    Analyst Commentary
    "The nutricosmetics sector is no longer viewed as an experimental crossover between food and cosmetics; it has matured into a science-driven category defined by clinical validation and cellular health," said a Senior Research Analyst at Stellar Market Research. "As consumers increasingly look inward to manage long-term skin vitality and healthy aging, brands that successfully combine bioavailable active ingredients with transparent, sustainable supply chains will command the next wave of market leadership."

    Future Outlook
    Through the forecast period, the nutricosmetics market is anticipated to experience accelerated mainstream adoption. Growth will be heavily underpins by continuous technological innovations in biotechnology, precision nutrition, and multi-functional format diversification (such as functional gummies, liquid ampoules, and daily convenience sachets). Regulatory compliance will tighten, filtering out unsubstantiated claims and favoring science-led market leaders. Strategic cross-sector collaborations between pharmaceutical labs, cosmetic powerhouses, and biotech innovators will further redefine the boundaries of modern beauty and wellness.

    For further information, click the following link: https://www.stellarmr.com/report/req_sample/Nutricosmetics-Market/2625
    About Stellar Market Research
    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Address
    Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041

    Email
    [email protected]

    Mobile
    +91 9607365656
    Stellar Market Research, a premier market intelligence and business consulting firm, has released an in-depth strategic analysis report on the Nutricosmetics Market. The comprehensive study evaluates current dynamics, shifts in consumer behavior, and technological catalysts transforming the global landscape. According to the report, the market was valued at USD 7.69 billion in 2025 and is projected to scale to USD 15.34 billion by 2034, registering a robust compound annual growth rate (CAGR) of approximately 7.9% to 8.31% over the forecast period. The convergence of personal care, dermatology, and nutraceutical science has catalyzed a paradigm shift in how consumers approach anti-aging and daily beauty regimens. Moving beyond topical cosmetics, the global market is experiencing unprecedented demand for ingestible solutions that target skin elasticity, hair vitality, and nail strength at a cellular level. This structural transformation is heavily propelled by heightened consumer literacy regarding holistic wellness, preventative health, and the limitations of surface-level cosmetic treatments. Key Findings from the Report Market Valuation & Growth Trajectory: The global nutricosmetics market, valued at USD 7.69 billion in 2025, is on a high-growth trajectory, poised to reach USD 15.34 billion by 2034, expanding at a steady CAGR of ~7.9% to 8.31%. Dominant Product & Segment Share: Dietary supplements (capsules, tablets, and powders) lead product-type demand, capturing over 60% of the market share due to consumer familiarity, ease of precise dosing, and seamless integration into daily wellness routines. Application Insights: Skin care applications hold the largest revenue share, driven by surging consumer preference for anti-aging, hydration, and UV-protection ingestibles, while hair care emerges as the fastest-growing application category. Ingredient Leadership: Collagen peptides dominate the active ingredient base, capturing a dominant share supported by strong consumer awareness surrounding skin matrix support and joint-beauty synergies. Leading Geographic Hub: North America commands the largest regional revenue share, anchored by advanced retail channels, high disposable incomes, and robust regulatory oversight by the FDA that bolsters consumer confidence. Fastest-Growing Region: Asia-Pacific is projected to record the highest regional CAGR through the forecast period, powered by deeply entrenched cultural traditions of functional foods and preventive health in Japan and South Korea. Distribution Channel Evolution: Online retail channels represent the primary sales avenue, fueled by direct-to-consumer (D2C) subscription models, digital beauty education, and targeted social media marketing. For further information, click the following link: https://www.stellarmr.com/report/req_sample/Nutricosmetics-Market/2625 Market Drivers and Restraints Drivers Rising Consumer Preference for Preventive Health & Wellness: A cultural shift toward proactive self-care has accelerated consumer willingness to invest in ingestible beauty products that promise long-term systemic benefits over quick fixes. Advancements in Bioactive Extraction & Delivery Systems: Innovations in bioavailability—such as advanced hydrolyzed peptides, liposomal delivery, and biomimetic ingredients—are substantially enhancing product efficacy and consumer results. Proliferation of D2C Subscription Models & Digital Personalization: E-commerce platforms and AI-driven skin diagnostic tools allow brands to offer tailored supplement regimens, successfully lowering adoption friction and driving repeat purchases. Restraints Strict and Fragmented Regulatory Frameworks: Navigating cross-border compliance regarding health claims, ingredient approvals (such as novel foods in Europe), and substantiating beauty-from-within claims presents a significant hurdle for market entrants. High Price Points for Premium Formulations: Premium clinical ingredients and specialized manufacturing processes often result in elevated retail price points, limiting market penetration among price-sensitive consumer segments. Technology, Regulation, and Sustainability Trends The nutricosmetics sector is undergoing a profound operational transformation driven by technology and sustainability. Artificial intelligence and mobile diagnostic apps are increasingly utilized to analyze individual skin metrics and deliver customized supplement formulations. Concurrently, regulatory bodies are enforcing stricter documentation standards for substantiating skin and hair health claims, compelling brands to invest heavily in clinical trials. On the environmental front, sustainability (ESG) has become a core competitive differentiator. Manufacturers are rapidly transitioning to eco-friendly packaging—such as paper-based canisters and biodegradable pouches—and adopting traceable, ethically sourced marine and plant-derived ingredients to satisfy eco-conscious consumers. Regional Insights North America: Maintaining a dominant regional market share, North America benefits from robust venture capital activity, widespread adoption of personalized nutrition, and mainstream retail expansion into metabolic and inner-beauty aisles. Asia-Pacific: Poised for the fastest regional growth, Asia-Pacific thrives on mature consumer habits in Japan and South Korea, where fermented botanicals, collagen drinks, and functional foods are deeply woven into daily lifestyle and heritage routines. Europe: Driven by stringent European Food Safety Authority (EFSA) standards, Europe prioritizes clean-label transparency, rigorous product safety, and aggressive corporate sustainability mandates. Recent Industry Developments L'Oréal (2026): Entered the nutricosmetics space with the launch of Vichy Laboratories Liftactiv Collagen Supplements, designed to support cellular health and natural collagen synthesis for both men and women. Solabia Group (2026): Completed the strategic acquisition of Mibelle Biochemistry in July 2026, expanding its biotech-oriented active ingredient portfolio and accelerating formulation capabilities for global beauty brands. TOSLA & Geltor (2026): Partnered to launch the Signaling Collagen liquid shot, a vegan-certified ingestible featuring biomimetic type 21 signaling collagen polypeptides to improve skin architecture. Nutrafol (2026): Expanded its life-stage product portfolio with the launch of the Men 50+ Hair Growth Nutraceutical, addressing targeted hair-thinning pathways in aging demographics. Amway / Nutrilite (2026): Won the Cellular Longevity from Within category at INNOCOS for its CelAct Cellular Aging Support formulation, highlighting the industry's pivot toward cellular health innovations. Competitive Landscape The global nutricosmetics market features a dynamic mix of established multinational health-science conglomerates, specialized beauty giants, and agile direct-to-consumer disruptors. Leading players are focusing on strategic mergers, biotech acquisitions, and clean-label product extensions to capture market share. Key market participants include Nestlé Health Science, Shiseido Company, L'Oréal, Amway (Nutrilite), Solabia Group (Mibelle Biochemistry), Nutrafol, and Ritual, among others. Competitive advantage increasingly relies on clinical validation, transparent sourcing, and personalized digital subscription ecosystems. Analyst Commentary "The nutricosmetics sector is no longer viewed as an experimental crossover between food and cosmetics; it has matured into a science-driven category defined by clinical validation and cellular health," said a Senior Research Analyst at Stellar Market Research. "As consumers increasingly look inward to manage long-term skin vitality and healthy aging, brands that successfully combine bioavailable active ingredients with transparent, sustainable supply chains will command the next wave of market leadership." Future Outlook Through the forecast period, the nutricosmetics market is anticipated to experience accelerated mainstream adoption. Growth will be heavily underpins by continuous technological innovations in biotechnology, precision nutrition, and multi-functional format diversification (such as functional gummies, liquid ampoules, and daily convenience sachets). Regulatory compliance will tighten, filtering out unsubstantiated claims and favoring science-led market leaders. Strategic cross-sector collaborations between pharmaceutical labs, cosmetic powerhouses, and biotech innovators will further redefine the boundaries of modern beauty and wellness. For further information, click the following link: https://www.stellarmr.com/report/req_sample/Nutricosmetics-Market/2625 About Stellar Market Research Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Address Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041 Email [email protected] Mobile +91 9607365656
    0 Comments ·0 Shares ·206 Views
  • Stellar Market Research has released a comprehensive intelligence study on the Wood Chips Market, revealing that the industry is undergoing a structural evolution driven by global decarbonization mandates and renewable energy transitions. Valued at USD 12.11 Billion in 2025, the market is projected to reach USD 23.60 Billion by 2032, expanding at a remarkable compound annual growth rate (CAGR) of 10% during the forecast period. The report underscores the strategic importance of wood chips as a versatile biomass feedstock critical for meeting international climate targets while ensuring reliable industrial and residential heat generation.

    The global energy matrix is undergoing a profound paradigm shift, moving decisively away from fossil fuel reliance toward decentralized renewable alternatives. Within this transformation, the wood chips market has emerged as a linchpin for circular bioeconomy initiatives. Driven by tightening carbon emission policies and the necessity for secure, localized heat and power sources, commercial enterprises and municipal utilities are actively restructuring their fuel supply chains.

    Key Findings from the Report
    Market Valuation & Trajectory: The global Wood Chips Market reached USD 12.11 Billion in 2025 and is projected to expand to USD 23.60 Billion by 2032 at a 10% CAGR.

    Dominant Product Segment: The Softwood segment commanded the largest market share at 46% in 2025, primarily driven by widespread utilization in garden mulching, playground surfacing, and high-volume industrial applications.

    Leading Application Category: Residential Heating dominated application channels with a 38% market share in 2025, supported by widespread global adoption of eco-friendly home heating solutions.

    Regional Dominance: The Asia-Pacific region captured a leading 39% market share in 2025, heavily reinforced by government feed-in-tariff subsidy schemes and expanding biomass project pipelines in countries like Japan.

    High-Growth Regional Frontier: Europe is forecast to register steady, high-value growth at a 9.92% CAGR over the forecast period, anchored by decentralized small-scale combined heat and power (CHP) installations.

    Pulp & Paper Integration: The increasing demand for wood chips as a primary raw material in pulp mills continues to provide a stable industrial baseline for continuous market expansion.

    Investment & Diversification Potential: Emerging interest in advanced applications—such as utilizing nanocrystalline cellulose (NCC) extracted from wood pulp for next-generation flexible electronics—is unlocking new commercial horizons for market stakeholders.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/Wood-Chips-Market/485

    Market Drivers and Restraints
    Driver 1: Accelerated Transition to Renewable Biomass Energy: Escalating depletion of conventional fossil fuels and stringent international climate protocols are compelling governments and utility providers to scale up biomass solid fuel utilization.

    Driver 2: Surging Demand from the Pulp and Paper Sector: Continuous capacity expansions across global pulp mills require reliable, high-grade wood chip inputs to satisfy paper, packaging, and derivative product manufacturing needs.

    Driver 3: Proliferation of Eco-Friendly Landscaping and Composting: Rising consumer and municipal preference for organic soil amendments, playground safety surfacing, and sustainable garden mulch acts as a consistent secondary growth catalyst.

    Restraint 1: Intense Competition from Alternative Biofuels: The growing popularity and commercial scaling of wood pellets as an alternative dense fuel pose a competitive threat, particularly in commercial power generation segments.

    Restraint 2: Strict GHG Emissions Compliance and Certification Hurdles: Regulatory burdens regarding greenhouse gas emissions standards and the high cost of acquiring sustainability-related forestry certifications can impede rapid supply chain scaling.

    Technology, Regulation, and Sustainability Trends
    The industry is experiencing profound operational transformation through the adoption of advanced digital log loaders, automated de-wrapping stations, and precision chipping technology designed to minimize waste and optimize fiber recovery. Regulatory frameworks are increasingly prioritizing carbon accountability; policy instruments such as carbon pricing and strict sustainability compliance require market players to maintain transparent, traceable sourcing operations. Simultaneously, ESG (Environmental, Social, and Governance) imperatives are accelerating reforestation partnerships and waste-to-energy circularity, ensuring that wood chip harvesting actively balances ecological restoration with commercial output.

    Regional Insights
    Asia-Pacific: Securing a commanding 39% market share in 2025, Asia-Pacific represents the epicenter of global consumption. Japan continues to spearhead regional expansion by leveraging robust Feed-in-Tariff (FiT) subsidy mechanisms to construct extensive biomass energy generation pipelines, while major developing economies scale up domestic pulp production infrastructure.

    Europe: Europe is poised to record a stellar 9.92% CAGR through the forecast period. The region's growth is anchored by established small-scale (sub-20MW) combined heat and power (CHP) infrastructure that predominantly utilizes locally sourced wood, satisfying rigorous EU renewable energy directives.

    North America: Supported by well-established commercial forestry networks in the United States and Canada, North America remains a highly consolidated market focused on supply chain optimization, advanced wood processing technology, and export efficiency.

    Recent Industry Developments
    River City Fibre LP (2025): Deployed a USD 600,000 modernization investment backed by local public-private funding to integrate an electric log loader and de-wrapping station in Kamloops, boosting low-value pulp log processing efficiency while cutting operational emissions.

    Eternali (2024): Expanded its Brazilian operational footprint by acquiring 3.3 hectares of land in Moju, Pará, to construct a dedicated wood chip production facility designed to feed regional biomass energy demands using locally sourced sawmill residues.

    Ørsted A/S (2024): Announced strategic plans to expand its European biomass power generation portfolio, driving substantial long-term demand commitments for sustainable wood chip fuel supplies.

    Great Northern Timber (2024): Partnered with local ecological conservation groups to initiate structured reforestation projects in harvested timber tracts, establishing a verifiable precedent for balancing commercial wood chip harvesting with active ecosystem restoration.

    Drax Group (2024): Committed a USD 300 million capital investment toward the construction of advanced biomass power generation and renewable energy infrastructure in Scotland, driving long-term market demand for sustainably certified wood chips.

    Competitive Landscape
    The global wood chips market exhibits a semi-consolidated competitive structure characterized by the active participation of major forestry conglomerates, specialized biomass processors, and regional market players. Leading industry participants are actively pursuing strategic supply chain integration, technological modernization, and long-term municipal procurement partnerships. Key companies profiled in the market intelligence landscape include Enviva Inc., Drax Group, Weyerhaeuser Company, West Fraser Timber Co. Ltd., International Paper Company, St. Boniface Pallet Company Ltd., EVOWORLD GmbH, and American Wood Resources. Major players are increasingly emphasizing certified sustainable forestry practices and processing efficiency to capture high-margin supply agreements across European and Asian energy corridors.

    Analyst Commentary
    "The wood chips market has transitioned far beyond a conventional forestry byproduct sector into an essential pillar of the global bio-energy and bio-materials economy," said a Senior Research Analyst at Stellar Market Research. "As corporate sustainability mandates and government decarbonization targets tighten through 2032, market participants that invest in supply chain traceability, advanced fiber processing efficiency, and localized sourcing networks will capture outsized value. The ability to guarantee compliant, low-carbon biomass feedstocks will ultimately separate market leaders from legacy followers."

    Future Outlook
    Looking ahead through the 2026–2032 forecast horizon, the wood chips market is expected to experience sustained, high-value expansion. Demand dynamics will increasingly pivot toward high-efficiency combined heat and power (CHP) applications and innovative high-tech bio-refining avenues, such as nanocrystalline cellulose production. While regulatory frameworks and carbon accounting standards will grow more stringent, they will simultaneously reward forward-thinking operators who embrace certified sustainable forestry. Supported by robust infrastructure investments across Asia-Pacific and Europe, the market is well-positioned to cement its role as a cornerstone of the global green energy transition.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/Wood-Chips-Market/485 

    About Stellar Market Research

    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Address
    Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041

    Email
    [email protected]

    Mobile
    +91 9607365656 #APAC Wood Chips Market, Japan Biomass Feed-in-Tariff, Asia Pacific Renewable Energy, Wood Pulp Export Asia, Biomass Imports APAC, Forest Biomass Supply Chain, Sustainable Energy Asia
    Stellar Market Research has released a comprehensive intelligence study on the Wood Chips Market, revealing that the industry is undergoing a structural evolution driven by global decarbonization mandates and renewable energy transitions. Valued at USD 12.11 Billion in 2025, the market is projected to reach USD 23.60 Billion by 2032, expanding at a remarkable compound annual growth rate (CAGR) of 10% during the forecast period. The report underscores the strategic importance of wood chips as a versatile biomass feedstock critical for meeting international climate targets while ensuring reliable industrial and residential heat generation. The global energy matrix is undergoing a profound paradigm shift, moving decisively away from fossil fuel reliance toward decentralized renewable alternatives. Within this transformation, the wood chips market has emerged as a linchpin for circular bioeconomy initiatives. Driven by tightening carbon emission policies and the necessity for secure, localized heat and power sources, commercial enterprises and municipal utilities are actively restructuring their fuel supply chains. Key Findings from the Report Market Valuation & Trajectory: The global Wood Chips Market reached USD 12.11 Billion in 2025 and is projected to expand to USD 23.60 Billion by 2032 at a 10% CAGR. Dominant Product Segment: The Softwood segment commanded the largest market share at 46% in 2025, primarily driven by widespread utilization in garden mulching, playground surfacing, and high-volume industrial applications. Leading Application Category: Residential Heating dominated application channels with a 38% market share in 2025, supported by widespread global adoption of eco-friendly home heating solutions. Regional Dominance: The Asia-Pacific region captured a leading 39% market share in 2025, heavily reinforced by government feed-in-tariff subsidy schemes and expanding biomass project pipelines in countries like Japan. High-Growth Regional Frontier: Europe is forecast to register steady, high-value growth at a 9.92% CAGR over the forecast period, anchored by decentralized small-scale combined heat and power (CHP) installations. Pulp & Paper Integration: The increasing demand for wood chips as a primary raw material in pulp mills continues to provide a stable industrial baseline for continuous market expansion. Investment & Diversification Potential: Emerging interest in advanced applications—such as utilizing nanocrystalline cellulose (NCC) extracted from wood pulp for next-generation flexible electronics—is unlocking new commercial horizons for market stakeholders. For further information, click the following link:https://www.stellarmr.com/report/req_sample/Wood-Chips-Market/485 Market Drivers and Restraints Driver 1: Accelerated Transition to Renewable Biomass Energy: Escalating depletion of conventional fossil fuels and stringent international climate protocols are compelling governments and utility providers to scale up biomass solid fuel utilization. Driver 2: Surging Demand from the Pulp and Paper Sector: Continuous capacity expansions across global pulp mills require reliable, high-grade wood chip inputs to satisfy paper, packaging, and derivative product manufacturing needs. Driver 3: Proliferation of Eco-Friendly Landscaping and Composting: Rising consumer and municipal preference for organic soil amendments, playground safety surfacing, and sustainable garden mulch acts as a consistent secondary growth catalyst. Restraint 1: Intense Competition from Alternative Biofuels: The growing popularity and commercial scaling of wood pellets as an alternative dense fuel pose a competitive threat, particularly in commercial power generation segments. Restraint 2: Strict GHG Emissions Compliance and Certification Hurdles: Regulatory burdens regarding greenhouse gas emissions standards and the high cost of acquiring sustainability-related forestry certifications can impede rapid supply chain scaling. Technology, Regulation, and Sustainability Trends The industry is experiencing profound operational transformation through the adoption of advanced digital log loaders, automated de-wrapping stations, and precision chipping technology designed to minimize waste and optimize fiber recovery. Regulatory frameworks are increasingly prioritizing carbon accountability; policy instruments such as carbon pricing and strict sustainability compliance require market players to maintain transparent, traceable sourcing operations. Simultaneously, ESG (Environmental, Social, and Governance) imperatives are accelerating reforestation partnerships and waste-to-energy circularity, ensuring that wood chip harvesting actively balances ecological restoration with commercial output. Regional Insights Asia-Pacific: Securing a commanding 39% market share in 2025, Asia-Pacific represents the epicenter of global consumption. Japan continues to spearhead regional expansion by leveraging robust Feed-in-Tariff (FiT) subsidy mechanisms to construct extensive biomass energy generation pipelines, while major developing economies scale up domestic pulp production infrastructure. Europe: Europe is poised to record a stellar 9.92% CAGR through the forecast period. The region's growth is anchored by established small-scale (sub-20MW) combined heat and power (CHP) infrastructure that predominantly utilizes locally sourced wood, satisfying rigorous EU renewable energy directives. North America: Supported by well-established commercial forestry networks in the United States and Canada, North America remains a highly consolidated market focused on supply chain optimization, advanced wood processing technology, and export efficiency. Recent Industry Developments River City Fibre LP (2025): Deployed a USD 600,000 modernization investment backed by local public-private funding to integrate an electric log loader and de-wrapping station in Kamloops, boosting low-value pulp log processing efficiency while cutting operational emissions. Eternali (2024): Expanded its Brazilian operational footprint by acquiring 3.3 hectares of land in Moju, Pará, to construct a dedicated wood chip production facility designed to feed regional biomass energy demands using locally sourced sawmill residues. Ørsted A/S (2024): Announced strategic plans to expand its European biomass power generation portfolio, driving substantial long-term demand commitments for sustainable wood chip fuel supplies. Great Northern Timber (2024): Partnered with local ecological conservation groups to initiate structured reforestation projects in harvested timber tracts, establishing a verifiable precedent for balancing commercial wood chip harvesting with active ecosystem restoration. Drax Group (2024): Committed a USD 300 million capital investment toward the construction of advanced biomass power generation and renewable energy infrastructure in Scotland, driving long-term market demand for sustainably certified wood chips. Competitive Landscape The global wood chips market exhibits a semi-consolidated competitive structure characterized by the active participation of major forestry conglomerates, specialized biomass processors, and regional market players. Leading industry participants are actively pursuing strategic supply chain integration, technological modernization, and long-term municipal procurement partnerships. Key companies profiled in the market intelligence landscape include Enviva Inc., Drax Group, Weyerhaeuser Company, West Fraser Timber Co. Ltd., International Paper Company, St. Boniface Pallet Company Ltd., EVOWORLD GmbH, and American Wood Resources. Major players are increasingly emphasizing certified sustainable forestry practices and processing efficiency to capture high-margin supply agreements across European and Asian energy corridors. Analyst Commentary "The wood chips market has transitioned far beyond a conventional forestry byproduct sector into an essential pillar of the global bio-energy and bio-materials economy," said a Senior Research Analyst at Stellar Market Research. "As corporate sustainability mandates and government decarbonization targets tighten through 2032, market participants that invest in supply chain traceability, advanced fiber processing efficiency, and localized sourcing networks will capture outsized value. The ability to guarantee compliant, low-carbon biomass feedstocks will ultimately separate market leaders from legacy followers." Future Outlook Looking ahead through the 2026–2032 forecast horizon, the wood chips market is expected to experience sustained, high-value expansion. Demand dynamics will increasingly pivot toward high-efficiency combined heat and power (CHP) applications and innovative high-tech bio-refining avenues, such as nanocrystalline cellulose production. While regulatory frameworks and carbon accounting standards will grow more stringent, they will simultaneously reward forward-thinking operators who embrace certified sustainable forestry. Supported by robust infrastructure investments across Asia-Pacific and Europe, the market is well-positioned to cement its role as a cornerstone of the global green energy transition. For further information, click the following link:https://www.stellarmr.com/report/req_sample/Wood-Chips-Market/485  About Stellar Market Research Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Address Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041 Email [email protected] Mobile +91 9607365656 #APAC Wood Chips Market, Japan Biomass Feed-in-Tariff, Asia Pacific Renewable Energy, Wood Pulp Export Asia, Biomass Imports APAC, Forest Biomass Supply Chain, Sustainable Energy Asia
    0 Comments ·0 Shares ·498 Views
  • The Prompt Engineering Market is undergoing an unprecedented expansion phase, according to a comprehensive intelligence study released by Stellar Market Research. Propelled by the rapid enterprise integration of large language models (LLMs) and multimodal artificial intelligence frameworks, the market is fundamentally altering how organizations interact with digital infrastructure. Strategic market analysis indicates that optimizing human-to-AI communication layers has transitioned from a niche technical workaround to a mission-critical operational pillar for modern enterprises seeking maximized ROI from automation investments.

    As generative artificial intelligence matures from a tech-sector novelty into the backbone of global enterprise digital transformation, companies face a distinct operational bottleneck: generic model outputs rarely align with specific business logic or regulatory mandates. This friction has unlocked a massive commercial opening for prompt engineering infrastructure, automated prompt lifecycle management, and enterprise-grade execution frameworks. Rather than investing heavily in retraining proprietary foundational models—a process fraught with high capital expenditure and heavy computational overhead—businesses are heavily pivoting toward sophisticated prompt architecture.

    Key Findings from the Report
    Market Valuation Trajectory: The global prompt engineering market is valued at USD 673.59 million, surging toward a projected valuation of USD 6,703.84 million by 2034.

    Growth Momentum: The market is advancing at an aggressive compound annual growth rate (CAGR) of 33.27% throughout the 2026–2034 forecast period.

    Component Dominance: The Software segment commands the largest market share, driven by surging enterprise demand for automated prompt generation, version control, and performance monitoring tools.

    Deployment Preference: Cloud-based deployment holds the leading market share due to its scalability, elasticity, and seamless integration capabilities with cloud-hosted foundational models.

    Leading Application: Content generation and conversational AI lead application segments, fueled by corporate demands for scaled marketing automation and intelligent customer service architectures.

    Regional Powerhouse: North America represents the leading regional market, capturing a dominant 40% revenue share backed by robust venture funding and early enterprise technology adoption.

    Investment Relevance: Venture capital and corporate IT budgets are increasingly prioritizing AI governance and workflow integration tools, driving high-value merger and acquisition activity across the sector.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/Prompt-Engineering-Market/2801

    Market Drivers and Restraints
    Drivers
    Rapid Enterprise Adoption of Generative AI: Organizations across BFSI, healthcare, retail, and IT services are scaling generative AI models to drive business automation, necessitating precise output control mechanisms.

    Cost Efficiency Over Model Retraining: Prompt engineering enables businesses to customize and optimize LLM outputs dynamically without incurring the massive capital outlays required to retrain base neural networks.

    Proliferation of Complex Multimodal Systems: The shift toward multimodal AI frameworks handling text, code, voice, and imagery requires sophisticated prompt structuring to maintain context and operational reliability.

    Restraints
    Lack of Standardized Skills and Prompt Governance: The market faces a shortage of unified frameworks and certified professionals, leading to inconsistent prompt performance and execution silos across legacy enterprises.

    Security, Compliance, and Data Vulnerabilities: Ineffectively structured prompts can expose organizations to data leakage, prompt injection vulnerabilities, and stringent regulatory non-compliance penalties.

    Technology, Regulation, and Sustainability Trends
    The prompt engineering landscape is heavily defined by convergence across advanced technology, evolving regulatory frameworks, and operational sustainability. Technologically, the integration of low-code prompt design interfaces and automated prompt optimization APIs is democratizing AI interaction for non-technical business units. From a regulatory standpoint, increasing governmental scrutiny regarding AI transparency—such as compliance mandates under emerging international frameworks—requires enterprises to maintain verifiable prompt audit trails. On the ESG front, prompt engineering champions operational sustainability; by optimizing query paths and reducing redundant model iterations, enterprises significantly lower the carbon footprint and electrical power consumption associated with heavy data center compute loads.

    Regional Insights
    North America: Leading the global ecosystem with a 40% market share, North America’s dominance is anchored in the United States. Heavy density of major tech conglomerates, early enterprise cloud adoption, and substantial federal and private investments in AI safety and research anchor the region's top-tier standing.

    Europe: Capturing roughly 27% of the global market, Europe exhibits strong growth driven by strict data sovereignty laws (such as the EU AI Act), compelling enterprises to adopt rigorous prompt governance and localized compliance software.

    Asia-Pacific: Emerging as a hyper-growth frontier, the Asia-Pacific region is propelled by rapid industrial digitalization, expanding IT sectors in India and Japan, and aggressive public-private digital initiatives aimed at sovereign AI capabilities.

    Recent Industry Developments
    Amazon Web Services (2023): Expanded its generative AI capabilities with Amazon Bedrock, incorporating automated prompt engineering features and managed APIs to streamline foundation model experimentation for enterprise users.

    Vocify Inc. / Vellum (2023): Launched production-grade APIs—Execute Prompt and Execute Prompt Stream—giving developers direct infrastructure tools for version-controlled prompt management and execution.

    OpenAI (2024): Introduced advanced developer tooling and structured prompt guidelines designed to minimize hallucination rates and improve deterministic output across enterprise API deployments.

    Microsoft (2025): Deepened its Azure AI ecosystem integration by embedding automated prompt optimization modules into corporate productivity suites, directly accelerating enterprise workflow automation.

    Google Cloud (2025): Rolled out enhanced Vertex AI prompt gallery features and evaluation toolkits, enabling cross-functional teams to test, benchmark, and deploy secure prompt templates at scale.

    Competitive Landscape
    The competitive matrix of the prompt engineering market features a dynamic blend of hyper-scale cloud providers, specialized AI infrastructure startups, and enterprise software incumbents. Leading market participants are focusing aggressively on platform interoperability, low-code interface expansion, and built-in security compliance. Strategic partnerships between cloud infrastructure giants and specialized LLM developers dominate current market maneuvers, with firms aiming to capture sticky, recurring enterprise revenue streams through comprehensive lifecycle management dashboards.

    Analyst Commentary
    "Prompt engineering has moved well beyond trial-and-error text manipulation; it is now the foundational syntax of the enterprise software stack. Organizations that treat prompt architecture as an afterthought will struggle with operational drift, security liabilities, and runaway compute costs. Our findings at Stellar Market Research indicate that the real winners of the next decade will be enterprises that institutionalize prompt governance as a core component of their digital asset management."

    — Senior Research Analyst, Stellar Market Research

    Future Outlook
    Throughout the forecast period, the prompt engineering market is set to transition toward hyper-automated, AI-driven prompt optimization. As foundational models become increasingly commoditized, competitive differentiation will shift toward proprietary prompt libraries, domain-specific tuning frameworks, and automated security guardrails. Regulatory compliance will tighten, forcing vendors to build auditable, transparent prompt workflows. Investment activity will pivot toward B2B software solutions that seamlessly bridge non-technical business logic with underlying machine learning architecture, cementing prompt engineering as an indispensable pillar of the global digital economy.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/Prompt-Engineering-Market/2801 
    About Stellar Market Research

    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Address
    Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041

    Email
    [email protected]

    Mobile
    +91 9607365656
    The Prompt Engineering Market is undergoing an unprecedented expansion phase, according to a comprehensive intelligence study released by Stellar Market Research. Propelled by the rapid enterprise integration of large language models (LLMs) and multimodal artificial intelligence frameworks, the market is fundamentally altering how organizations interact with digital infrastructure. Strategic market analysis indicates that optimizing human-to-AI communication layers has transitioned from a niche technical workaround to a mission-critical operational pillar for modern enterprises seeking maximized ROI from automation investments. As generative artificial intelligence matures from a tech-sector novelty into the backbone of global enterprise digital transformation, companies face a distinct operational bottleneck: generic model outputs rarely align with specific business logic or regulatory mandates. This friction has unlocked a massive commercial opening for prompt engineering infrastructure, automated prompt lifecycle management, and enterprise-grade execution frameworks. Rather than investing heavily in retraining proprietary foundational models—a process fraught with high capital expenditure and heavy computational overhead—businesses are heavily pivoting toward sophisticated prompt architecture. Key Findings from the Report Market Valuation Trajectory: The global prompt engineering market is valued at USD 673.59 million, surging toward a projected valuation of USD 6,703.84 million by 2034. Growth Momentum: The market is advancing at an aggressive compound annual growth rate (CAGR) of 33.27% throughout the 2026–2034 forecast period. Component Dominance: The Software segment commands the largest market share, driven by surging enterprise demand for automated prompt generation, version control, and performance monitoring tools. Deployment Preference: Cloud-based deployment holds the leading market share due to its scalability, elasticity, and seamless integration capabilities with cloud-hosted foundational models. Leading Application: Content generation and conversational AI lead application segments, fueled by corporate demands for scaled marketing automation and intelligent customer service architectures. Regional Powerhouse: North America represents the leading regional market, capturing a dominant 40% revenue share backed by robust venture funding and early enterprise technology adoption. Investment Relevance: Venture capital and corporate IT budgets are increasingly prioritizing AI governance and workflow integration tools, driving high-value merger and acquisition activity across the sector. For further information, click the following link:https://www.stellarmr.com/report/req_sample/Prompt-Engineering-Market/2801 Market Drivers and Restraints Drivers Rapid Enterprise Adoption of Generative AI: Organizations across BFSI, healthcare, retail, and IT services are scaling generative AI models to drive business automation, necessitating precise output control mechanisms. Cost Efficiency Over Model Retraining: Prompt engineering enables businesses to customize and optimize LLM outputs dynamically without incurring the massive capital outlays required to retrain base neural networks. Proliferation of Complex Multimodal Systems: The shift toward multimodal AI frameworks handling text, code, voice, and imagery requires sophisticated prompt structuring to maintain context and operational reliability. Restraints Lack of Standardized Skills and Prompt Governance: The market faces a shortage of unified frameworks and certified professionals, leading to inconsistent prompt performance and execution silos across legacy enterprises. Security, Compliance, and Data Vulnerabilities: Ineffectively structured prompts can expose organizations to data leakage, prompt injection vulnerabilities, and stringent regulatory non-compliance penalties. Technology, Regulation, and Sustainability Trends The prompt engineering landscape is heavily defined by convergence across advanced technology, evolving regulatory frameworks, and operational sustainability. Technologically, the integration of low-code prompt design interfaces and automated prompt optimization APIs is democratizing AI interaction for non-technical business units. From a regulatory standpoint, increasing governmental scrutiny regarding AI transparency—such as compliance mandates under emerging international frameworks—requires enterprises to maintain verifiable prompt audit trails. On the ESG front, prompt engineering champions operational sustainability; by optimizing query paths and reducing redundant model iterations, enterprises significantly lower the carbon footprint and electrical power consumption associated with heavy data center compute loads. Regional Insights North America: Leading the global ecosystem with a 40% market share, North America’s dominance is anchored in the United States. Heavy density of major tech conglomerates, early enterprise cloud adoption, and substantial federal and private investments in AI safety and research anchor the region's top-tier standing. Europe: Capturing roughly 27% of the global market, Europe exhibits strong growth driven by strict data sovereignty laws (such as the EU AI Act), compelling enterprises to adopt rigorous prompt governance and localized compliance software. Asia-Pacific: Emerging as a hyper-growth frontier, the Asia-Pacific region is propelled by rapid industrial digitalization, expanding IT sectors in India and Japan, and aggressive public-private digital initiatives aimed at sovereign AI capabilities. Recent Industry Developments Amazon Web Services (2023): Expanded its generative AI capabilities with Amazon Bedrock, incorporating automated prompt engineering features and managed APIs to streamline foundation model experimentation for enterprise users. Vocify Inc. / Vellum (2023): Launched production-grade APIs—Execute Prompt and Execute Prompt Stream—giving developers direct infrastructure tools for version-controlled prompt management and execution. OpenAI (2024): Introduced advanced developer tooling and structured prompt guidelines designed to minimize hallucination rates and improve deterministic output across enterprise API deployments. Microsoft (2025): Deepened its Azure AI ecosystem integration by embedding automated prompt optimization modules into corporate productivity suites, directly accelerating enterprise workflow automation. Google Cloud (2025): Rolled out enhanced Vertex AI prompt gallery features and evaluation toolkits, enabling cross-functional teams to test, benchmark, and deploy secure prompt templates at scale. Competitive Landscape The competitive matrix of the prompt engineering market features a dynamic blend of hyper-scale cloud providers, specialized AI infrastructure startups, and enterprise software incumbents. Leading market participants are focusing aggressively on platform interoperability, low-code interface expansion, and built-in security compliance. Strategic partnerships between cloud infrastructure giants and specialized LLM developers dominate current market maneuvers, with firms aiming to capture sticky, recurring enterprise revenue streams through comprehensive lifecycle management dashboards. Analyst Commentary "Prompt engineering has moved well beyond trial-and-error text manipulation; it is now the foundational syntax of the enterprise software stack. Organizations that treat prompt architecture as an afterthought will struggle with operational drift, security liabilities, and runaway compute costs. Our findings at Stellar Market Research indicate that the real winners of the next decade will be enterprises that institutionalize prompt governance as a core component of their digital asset management." — Senior Research Analyst, Stellar Market Research Future Outlook Throughout the forecast period, the prompt engineering market is set to transition toward hyper-automated, AI-driven prompt optimization. As foundational models become increasingly commoditized, competitive differentiation will shift toward proprietary prompt libraries, domain-specific tuning frameworks, and automated security guardrails. Regulatory compliance will tighten, forcing vendors to build auditable, transparent prompt workflows. Investment activity will pivot toward B2B software solutions that seamlessly bridge non-technical business logic with underlying machine learning architecture, cementing prompt engineering as an indispensable pillar of the global digital economy. For further information, click the following link:https://www.stellarmr.com/report/req_sample/Prompt-Engineering-Market/2801  About Stellar Market Research Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Address Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041 Email [email protected] Mobile +91 9607365656
    0 Comments ·0 Shares ·464 Views
  • Asia Pacific Freeze-Dried Food Market Growth Driven by Convenience Food Demand

    Market Estimation & Definition

    The Asia Pacific Freeze-Dried Food Market is witnessing strong growth as consumers increasingly seek convenient, nutritious, and shelf-stable food products that fit modern lifestyles. According to the Stellar Market Research report, the Asia Pacific Freeze-Dried Food Market is estimated to grow at a CAGR of 10.01% during the forecast period. Asia Pacific Freeze-Dried Food Market is expected to reach US$ 70.56 Bn. in 2032 from US$ 32.89 Bn in 2024.

    Freeze-dried food is produced through a dehydration process known as lyophilization, where frozen food undergoes sublimation to remove moisture while preserving its nutritional value, flavor, texture, and appearance. The technology significantly extends shelf life without requiring artificial preservatives, making freeze-dried products ideal for retail food, ready-to-eat meals, emergency food supplies, outdoor recreation, military applications, and foodservice operations.

    The Asia Pacific region has emerged as one of the fastest-growing markets due to rising disposable incomes, rapid urbanization, expanding retail infrastructure, and increasing consumer preference for premium convenience foods.

    Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Asia-Pacific-Freeze-Dried-Food-Market/814

    Market Growth Drivers & Opportunity

    One of the major drivers of the Asia Pacific Freeze-Dried Food Market is the growing demand for convenient meal solutions. Busy lifestyles, rising urban populations, and increasing workforce participation have encouraged consumers to purchase foods that require minimal preparation while maintaining high nutritional quality.

    The report highlights increasing demand for freeze-dried fruits, vegetables, dairy products, meat products, seafood, beverages, coffee, and ready-to-eat meals across both household and commercial applications. The technology preserves product quality while reducing transportation and storage costs, making it attractive for manufacturers and retailers alike.

    The rapid expansion of e-commerce and organized retail channels has significantly improved product accessibility across emerging economies. Online grocery platforms allow consumers to explore a broader range of freeze-dried products while supporting premium product positioning and direct-to-consumer sales.

    Another important growth opportunity lies in the expanding health and wellness sector. Consumers increasingly seek natural, minimally processed foods with high nutritional value, clean-label ingredients, and longer shelf life. Freeze-dried products satisfy these requirements while supporting growing demand for functional foods, healthy snacks, and sports nutrition products.

    Increasing exports of freeze-dried ingredients used in food processing, beverages, pharmaceuticals, and nutraceuticals are also contributing to market expansion across the region.

    What Lies Ahead: Emerging Trends Shaping the Future

    Technological innovation continues to shape the future of the Asia Pacific Freeze-Dried Food Market. Manufacturers are investing in advanced freeze-drying equipment that improves production efficiency, reduces processing time, and lowers energy consumption while maintaining superior product quality.

    Clean-label products remain one of the industry's strongest trends. Consumers increasingly favor foods free from artificial preservatives, synthetic additives, and excessive processing, encouraging manufacturers to expand natural product portfolios.

    Plant-based nutrition is another important trend influencing product innovation. Companies are introducing freeze-dried fruits, vegetables, plant proteins, herbs, and vegan meal solutions to address changing dietary preferences.

    Premium snack products, instant beverages, specialty coffee, functional nutrition, and personalized meal solutions continue gaining popularity across younger consumer segments. Sustainable packaging, recyclable materials, and environmentally responsible production methods are also becoming increasingly important purchasing considerations.

    Artificial intelligence and automation are improving manufacturing processes through predictive maintenance, quality monitoring, inventory optimization, and supply chain management, helping manufacturers improve operational efficiency and product consistency.

    Segmentation Analysis

    According to the Stellar Market Research report, the Asia Pacific Freeze-Dried Food Market is segmented based on Product Type, Nature, Distribution Channel, Application, End User, and Country.

    Based on product type, freeze-dried fruits and vegetables account for a substantial share of the market due to growing consumer demand for healthy snacks and natural food ingredients. Freeze-dried coffee, dairy products, meat, seafood, prepared meals, and nutritional ingredients also contribute significantly to market growth.

    By distribution channel, supermarkets and hypermarkets continue to dominate product sales, while online retail platforms represent one of the fastest-growing segments owing to expanding e-commerce adoption throughout the region.

    Household consumption remains the largest application segment, supported by increasing demand for convenient meal preparation, while foodservice, hospitality, military, healthcare, and industrial food processing sectors continue expanding their use of freeze-dried products.

    Country-Level Analysis

    United States

    The United States remains one of the world's leading markets for freeze-dried foods, supported by strong consumer demand for convenient nutrition, outdoor recreation products, emergency food supplies, and premium snack categories. Advanced food processing technologies and continuous product innovation have positioned American manufacturers among global industry leaders.

    Growing demand for functional foods, organic products, sports nutrition, and clean-label ingredients continues encouraging investments in advanced freeze-drying technologies and sustainable food manufacturing.

    Germany

    Germany represents a major European market for freeze-dried foods, driven by increasing consumer interest in healthy eating, organic products, and premium convenience foods. Strong demand exists across retail grocery, foodservice, nutraceutical, and beverage industries.

    German manufacturers emphasize product quality, food safety, and sustainable production while investing in energy-efficient processing technologies and environmentally responsible packaging. Rising demand for plant-based nutrition and natural food ingredients continues supporting long-term market expansion.

    Competitive Analysis

    Asahi Group Holdings Ltd. (Japan)

    Unilever Group (India)

    Ajinomoto Co., Inc. (Japan)

    Bajaj Agro Foods India Ltd. (India)

    Totally Pure Fruits Pty Ltd. (Australia)

    Thai Ao Chi Fruits Co., Ltd. (Thailand)

    Nutra Grand Co., Ltd (Thailand)

    Chantaburi Global Trade Co. (Thailand)

    Zhangzhou Henco Trading Co., Ltd. (China)

    Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Asia-Pacific-Freeze-Dried-Food-Market/814

    Press Release Conclusion

    The Asia Pacific Freeze-Dried Food Market is well positioned for sustained growth through 2032 as rising health awareness, changing consumer lifestyles, expanding retail infrastructure, and continuous technological innovation reshape the regional food industry. Increasing demand for nutritious convenience foods, clean-label products, and premium ingredients is creating substantial opportunities for manufacturers across multiple application segments.

    As food producers continue investing in advanced processing technologies, sustainable packaging, and product innovation, the freeze-dried food industry is expected to play an increasingly important role in meeting evolving consumer expectations. Companies that prioritize nutritional quality, operational excellence, digital transformation, and sustainable production will be best positioned to capitalize on the long-term growth opportunities within the Asia Pacific Freeze-Dried Food Market.

    About Stellar Market Research:

    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Contact Stellar Market Research:

    3rd Floor, Navale IT Park, Phase 2

    Pune Banglore Highway, Narhe,

    Pune, Maharashtra 411041, India

    [email protected]

    +91 20 6630 3320 | +91 9607365656
    Asia Pacific Freeze-Dried Food Market Growth Driven by Convenience Food Demand Market Estimation & Definition The Asia Pacific Freeze-Dried Food Market is witnessing strong growth as consumers increasingly seek convenient, nutritious, and shelf-stable food products that fit modern lifestyles. According to the Stellar Market Research report, the Asia Pacific Freeze-Dried Food Market is estimated to grow at a CAGR of 10.01% during the forecast period. Asia Pacific Freeze-Dried Food Market is expected to reach US$ 70.56 Bn. in 2032 from US$ 32.89 Bn in 2024. Freeze-dried food is produced through a dehydration process known as lyophilization, where frozen food undergoes sublimation to remove moisture while preserving its nutritional value, flavor, texture, and appearance. The technology significantly extends shelf life without requiring artificial preservatives, making freeze-dried products ideal for retail food, ready-to-eat meals, emergency food supplies, outdoor recreation, military applications, and foodservice operations. The Asia Pacific region has emerged as one of the fastest-growing markets due to rising disposable incomes, rapid urbanization, expanding retail infrastructure, and increasing consumer preference for premium convenience foods. Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Asia-Pacific-Freeze-Dried-Food-Market/814 Market Growth Drivers & Opportunity One of the major drivers of the Asia Pacific Freeze-Dried Food Market is the growing demand for convenient meal solutions. Busy lifestyles, rising urban populations, and increasing workforce participation have encouraged consumers to purchase foods that require minimal preparation while maintaining high nutritional quality. The report highlights increasing demand for freeze-dried fruits, vegetables, dairy products, meat products, seafood, beverages, coffee, and ready-to-eat meals across both household and commercial applications. The technology preserves product quality while reducing transportation and storage costs, making it attractive for manufacturers and retailers alike. The rapid expansion of e-commerce and organized retail channels has significantly improved product accessibility across emerging economies. Online grocery platforms allow consumers to explore a broader range of freeze-dried products while supporting premium product positioning and direct-to-consumer sales. Another important growth opportunity lies in the expanding health and wellness sector. Consumers increasingly seek natural, minimally processed foods with high nutritional value, clean-label ingredients, and longer shelf life. Freeze-dried products satisfy these requirements while supporting growing demand for functional foods, healthy snacks, and sports nutrition products. Increasing exports of freeze-dried ingredients used in food processing, beverages, pharmaceuticals, and nutraceuticals are also contributing to market expansion across the region. What Lies Ahead: Emerging Trends Shaping the Future Technological innovation continues to shape the future of the Asia Pacific Freeze-Dried Food Market. Manufacturers are investing in advanced freeze-drying equipment that improves production efficiency, reduces processing time, and lowers energy consumption while maintaining superior product quality. Clean-label products remain one of the industry's strongest trends. Consumers increasingly favor foods free from artificial preservatives, synthetic additives, and excessive processing, encouraging manufacturers to expand natural product portfolios. Plant-based nutrition is another important trend influencing product innovation. Companies are introducing freeze-dried fruits, vegetables, plant proteins, herbs, and vegan meal solutions to address changing dietary preferences. Premium snack products, instant beverages, specialty coffee, functional nutrition, and personalized meal solutions continue gaining popularity across younger consumer segments. Sustainable packaging, recyclable materials, and environmentally responsible production methods are also becoming increasingly important purchasing considerations. Artificial intelligence and automation are improving manufacturing processes through predictive maintenance, quality monitoring, inventory optimization, and supply chain management, helping manufacturers improve operational efficiency and product consistency. Segmentation Analysis According to the Stellar Market Research report, the Asia Pacific Freeze-Dried Food Market is segmented based on Product Type, Nature, Distribution Channel, Application, End User, and Country. Based on product type, freeze-dried fruits and vegetables account for a substantial share of the market due to growing consumer demand for healthy snacks and natural food ingredients. Freeze-dried coffee, dairy products, meat, seafood, prepared meals, and nutritional ingredients also contribute significantly to market growth. By distribution channel, supermarkets and hypermarkets continue to dominate product sales, while online retail platforms represent one of the fastest-growing segments owing to expanding e-commerce adoption throughout the region. Household consumption remains the largest application segment, supported by increasing demand for convenient meal preparation, while foodservice, hospitality, military, healthcare, and industrial food processing sectors continue expanding their use of freeze-dried products. Country-Level Analysis United States The United States remains one of the world's leading markets for freeze-dried foods, supported by strong consumer demand for convenient nutrition, outdoor recreation products, emergency food supplies, and premium snack categories. Advanced food processing technologies and continuous product innovation have positioned American manufacturers among global industry leaders. Growing demand for functional foods, organic products, sports nutrition, and clean-label ingredients continues encouraging investments in advanced freeze-drying technologies and sustainable food manufacturing. Germany Germany represents a major European market for freeze-dried foods, driven by increasing consumer interest in healthy eating, organic products, and premium convenience foods. Strong demand exists across retail grocery, foodservice, nutraceutical, and beverage industries. German manufacturers emphasize product quality, food safety, and sustainable production while investing in energy-efficient processing technologies and environmentally responsible packaging. Rising demand for plant-based nutrition and natural food ingredients continues supporting long-term market expansion. Competitive Analysis Asahi Group Holdings Ltd. (Japan) Unilever Group (India) Ajinomoto Co., Inc. (Japan) Bajaj Agro Foods India Ltd. (India) Totally Pure Fruits Pty Ltd. (Australia) Thai Ao Chi Fruits Co., Ltd. (Thailand) Nutra Grand Co., Ltd (Thailand) Chantaburi Global Trade Co. (Thailand) Zhangzhou Henco Trading Co., Ltd. (China) Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Asia-Pacific-Freeze-Dried-Food-Market/814 Press Release Conclusion The Asia Pacific Freeze-Dried Food Market is well positioned for sustained growth through 2032 as rising health awareness, changing consumer lifestyles, expanding retail infrastructure, and continuous technological innovation reshape the regional food industry. Increasing demand for nutritious convenience foods, clean-label products, and premium ingredients is creating substantial opportunities for manufacturers across multiple application segments. As food producers continue investing in advanced processing technologies, sustainable packaging, and product innovation, the freeze-dried food industry is expected to play an increasingly important role in meeting evolving consumer expectations. Companies that prioritize nutritional quality, operational excellence, digital transformation, and sustainable production will be best positioned to capitalize on the long-term growth opportunities within the Asia Pacific Freeze-Dried Food Market. About Stellar Market Research: Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Contact Stellar Market Research: 3rd Floor, Navale IT Park, Phase 2 Pune Banglore Highway, Narhe, Pune, Maharashtra 411041, India [email protected] +91 20 6630 3320 | +91 9607365656
    0 Comments ·0 Shares ·474 Views
  • The Agrivoltaics Market reveals that the global market is experiencing a structural transformation, driven by the imperative to maximize land productivity, accelerate clean energy integration, and adopt climate-resilient farming techniques.

    The global agricultural and energy landscapes are undergoing a profound paradigm shift. Traditionally, land allocation has faced a zero-sum conflict between food production and photovoltaic (PV) solar installations. However, the agrivoltaics paradigm—co-locating agricultural activity and solar photovoltaic electricity generation on the same parcel of land—has emerged as a transformative solution to the land-food-energy nexus.

    Key Findings from the Report
    Valuation & Growth Trajectory: The global agrivoltaics market is projected to expand at a robust CAGR of over 11.5% throughout the forecast period from 2024 to 2034.

    Dominant Segment: Ground-mounted photovoltaic systems currently dominate the market share, favored by structural scalability and ease of integration with large-scale agricultural machinery.

    Fastest-Growing Segment: Tracking-system-integrated agrivoltaics represents the fastest-growing segment, driven by dynamic solar-tracking algorithms that optimize both crop microclimate exposure and energy generation yields.

    Crop Application Insight: Shade-tolerant crops—including berries, leafy greens, root vegetables, and select specialty vineyards—account for the largest share of commercial crop integration.

    Leading Region: Europe holds the leading revenue share, supported by stringent European Union decarbonization targets, favorable feed-in tariffs, and robust governmental subsidies for dual-use agricultural tech.

    Emerging Region: Asia-Pacific is positioned as the fastest-growing regional market, catalyzed by intensive land-use pressures in nations like China, Japan, and India, alongside national solar-agriculture integration initiatives.

    Investment Relevance: Venture capital and project-finance investments in agrivoltaic infrastructure have surged, attracting institutional capital focused on long-term Environmental, Social, and Governance (ESG) assets.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/agrivoltaics-market/2915
    Market Drivers and Restraints
    Drivers
    Land-Use Optimization and Dual Revenue Streams: The ability to simultaneously harvest crops and generate commercial electricity provides farmers with financial hedging against commodity price volatility and volatile crop yields.

    Climate Resilience and Microclimate Protection: Agrivoltaic shade structures reduce evapotranspiration, lower ambient soil and leaf temperatures during heatwaves, and conserve crucial irrigation water in arid and semi-arid agricultural zones.

    Decarbonization and Renewable Energy Mandates: Government incentives, carbon credit frameworks, and corporate net-zero commitments are driving agricultural enterprises to adopt on-site clean energy generation infrastructure.

    Restraints
    High Initial Capital Expenditure (CapEx): Specialized elevated mounting structures, custom PV spacing, and dual-purpose engineering designs incur significantly higher upfront setup costs compared to conventional solar farms.

    Operational and Mechanization Complexities: Operating heavy agricultural machinery beneath solar arrays requires precise layout planning, specialized equipment maneuvering, and ongoing operational coordination between farmers and energy operators.

    Technology, Regulation, and Sustainability Trends
    The agrivoltaics sector is being reshaped by rapid advancements in semi-transparent photovoltaic glass, bifacial solar modules, and automated smart-tracking systems that optimize light transmission based on real-time crop growth cycles. Regulatory frameworks are progressively evolving from ambiguous zoning restrictions to dedicated policy incentives, particularly across European and North American jurisdictions.

    From an ESG and sustainability standpoint, agrivoltaics delivers exceptional impact metrics: it drastically lowers the carbon footprint of food production, curtails agricultural water consumption by up to 20–30% in arid climates, and prevents the conversion of virgin ecosystems into industrial solar plants by utilizing pre-disturbed agricultural land.

    Regional Insights
    Europe: Leads the global market due to aggressive EU climate neutrality roadmaps, institutional research backing, and pioneering national policies in countries like France, Germany, and Italy that mandate or subsidize agrivoltaic zoning.

    Asia-Pacific: Represents the high-growth frontier. High population density and limited arable land per capita in nations such as China, Japan, and South Korea have forced accelerated adoption. Government-backed agricultural modernization programs are integrating solar PV directly into greenhouse horticulture and paddy cultivation.

    North America: Exhibiting rapid expansion driven by commercial farm consolidations, state-level clean energy portfolio standards, and growing pilot programs across the US Midwest and agricultural hubs in California.

    Recent Industry Developments
    Enel Green Power (2025): Launched an advanced commercial agrivoltaics pilot project in Southern Europe integrating high-clearance tracking PV arrays with olive groves, delivering a verified 15% reduction in irrigation water usage and stable crop yields.

    BayWa r.e. (2025): Expanded its international portfolio by completing a multi-megawatt fruit-protection agrivoltaic installation in Germany, safeguarding soft fruit yields against severe hail and extreme heat while generating clean electricity for regional grid injection.

    SunAgri (2024): Partnered with major European agricultural cooperatives to deploy dynamic smart-slat solar panels over vineyard acreage, demonstrating optimized grape maturation and enhanced wine quality alongside commercial power generation.

    TotalEnergies (2024): Acquired a controlling stake in a specialized agrivoltaics technology developer, injecting capital to scale modular, farmer-friendly elevation structures designed for seamless tractor access.

    NLC India Limited (2025): Initiated large-scale agricultural co-location initiatives beneath existing utility solar parks, proving the commercial viability of intercropping shade-tolerant legumes and fodder crops on degraded mining and industrial tracts.

    Competitive Landscape
    The global agrivoltaics market features a dynamic mix of specialized agritech innovators, renewable energy developers, and agricultural engineering conglomerates. Leading market players include BayWa r.e., Enel Green Power, TotalEnergies, SunAgri, Lightsource bp, Nexans, and REM TEC.

    Market participants are actively engaging in strategic joint ventures, proprietary mounting-structure patent filings, and collaboration agreements with agricultural universities to validate crop-specific yield models and de-risk investments for commercial farming enterprises.

    Analyst Commentary
    "The agrivoltaics market has transitioned past the experimental phase into a vital commercial pillar of the global energy-food nexus," said a Senior Research Analyst at Stellar Market Research. "As land scarcity intensifies and climate volatility threatens traditional agriculture, co-locating solar infrastructure with crop production is no longer merely an environmental option—it is a fundamental economic imperative that secures both our food supply and our renewable energy future."

    Future Outlook
    Through the forecast period to 2034, the agrivoltaics market is poised for exponential mainstream integration. Expected technological breakthroughs in bifacial transparency, wireless sensor-driven microclimate management, and standardized modular mounting kits will continue to compress installation costs. As regulatory bodies streamline dual-use zoning laws and institutional ESG investors direct capital toward verifiable land-restoration assets, agrivoltaics will firmly establish itself as a cornerstone of resilient, climate-smart global agriculture.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/agrivoltaics-market/2915
    About Stellar Market Research
    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Address
    Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041

    Email
    [email protected]

    Mobile
    +91 9607365656
    The Agrivoltaics Market reveals that the global market is experiencing a structural transformation, driven by the imperative to maximize land productivity, accelerate clean energy integration, and adopt climate-resilient farming techniques. The global agricultural and energy landscapes are undergoing a profound paradigm shift. Traditionally, land allocation has faced a zero-sum conflict between food production and photovoltaic (PV) solar installations. However, the agrivoltaics paradigm—co-locating agricultural activity and solar photovoltaic electricity generation on the same parcel of land—has emerged as a transformative solution to the land-food-energy nexus. Key Findings from the Report Valuation & Growth Trajectory: The global agrivoltaics market is projected to expand at a robust CAGR of over 11.5% throughout the forecast period from 2024 to 2034. Dominant Segment: Ground-mounted photovoltaic systems currently dominate the market share, favored by structural scalability and ease of integration with large-scale agricultural machinery. Fastest-Growing Segment: Tracking-system-integrated agrivoltaics represents the fastest-growing segment, driven by dynamic solar-tracking algorithms that optimize both crop microclimate exposure and energy generation yields. Crop Application Insight: Shade-tolerant crops—including berries, leafy greens, root vegetables, and select specialty vineyards—account for the largest share of commercial crop integration. Leading Region: Europe holds the leading revenue share, supported by stringent European Union decarbonization targets, favorable feed-in tariffs, and robust governmental subsidies for dual-use agricultural tech. Emerging Region: Asia-Pacific is positioned as the fastest-growing regional market, catalyzed by intensive land-use pressures in nations like China, Japan, and India, alongside national solar-agriculture integration initiatives. Investment Relevance: Venture capital and project-finance investments in agrivoltaic infrastructure have surged, attracting institutional capital focused on long-term Environmental, Social, and Governance (ESG) assets. For further information, click the following link:https://www.stellarmr.com/report/req_sample/agrivoltaics-market/2915 Market Drivers and Restraints Drivers Land-Use Optimization and Dual Revenue Streams: The ability to simultaneously harvest crops and generate commercial electricity provides farmers with financial hedging against commodity price volatility and volatile crop yields. Climate Resilience and Microclimate Protection: Agrivoltaic shade structures reduce evapotranspiration, lower ambient soil and leaf temperatures during heatwaves, and conserve crucial irrigation water in arid and semi-arid agricultural zones. Decarbonization and Renewable Energy Mandates: Government incentives, carbon credit frameworks, and corporate net-zero commitments are driving agricultural enterprises to adopt on-site clean energy generation infrastructure. Restraints High Initial Capital Expenditure (CapEx): Specialized elevated mounting structures, custom PV spacing, and dual-purpose engineering designs incur significantly higher upfront setup costs compared to conventional solar farms. Operational and Mechanization Complexities: Operating heavy agricultural machinery beneath solar arrays requires precise layout planning, specialized equipment maneuvering, and ongoing operational coordination between farmers and energy operators. Technology, Regulation, and Sustainability Trends The agrivoltaics sector is being reshaped by rapid advancements in semi-transparent photovoltaic glass, bifacial solar modules, and automated smart-tracking systems that optimize light transmission based on real-time crop growth cycles. Regulatory frameworks are progressively evolving from ambiguous zoning restrictions to dedicated policy incentives, particularly across European and North American jurisdictions. From an ESG and sustainability standpoint, agrivoltaics delivers exceptional impact metrics: it drastically lowers the carbon footprint of food production, curtails agricultural water consumption by up to 20–30% in arid climates, and prevents the conversion of virgin ecosystems into industrial solar plants by utilizing pre-disturbed agricultural land. Regional Insights Europe: Leads the global market due to aggressive EU climate neutrality roadmaps, institutional research backing, and pioneering national policies in countries like France, Germany, and Italy that mandate or subsidize agrivoltaic zoning. Asia-Pacific: Represents the high-growth frontier. High population density and limited arable land per capita in nations such as China, Japan, and South Korea have forced accelerated adoption. Government-backed agricultural modernization programs are integrating solar PV directly into greenhouse horticulture and paddy cultivation. North America: Exhibiting rapid expansion driven by commercial farm consolidations, state-level clean energy portfolio standards, and growing pilot programs across the US Midwest and agricultural hubs in California. Recent Industry Developments Enel Green Power (2025): Launched an advanced commercial agrivoltaics pilot project in Southern Europe integrating high-clearance tracking PV arrays with olive groves, delivering a verified 15% reduction in irrigation water usage and stable crop yields. BayWa r.e. (2025): Expanded its international portfolio by completing a multi-megawatt fruit-protection agrivoltaic installation in Germany, safeguarding soft fruit yields against severe hail and extreme heat while generating clean electricity for regional grid injection. SunAgri (2024): Partnered with major European agricultural cooperatives to deploy dynamic smart-slat solar panels over vineyard acreage, demonstrating optimized grape maturation and enhanced wine quality alongside commercial power generation. TotalEnergies (2024): Acquired a controlling stake in a specialized agrivoltaics technology developer, injecting capital to scale modular, farmer-friendly elevation structures designed for seamless tractor access. NLC India Limited (2025): Initiated large-scale agricultural co-location initiatives beneath existing utility solar parks, proving the commercial viability of intercropping shade-tolerant legumes and fodder crops on degraded mining and industrial tracts. Competitive Landscape The global agrivoltaics market features a dynamic mix of specialized agritech innovators, renewable energy developers, and agricultural engineering conglomerates. Leading market players include BayWa r.e., Enel Green Power, TotalEnergies, SunAgri, Lightsource bp, Nexans, and REM TEC. Market participants are actively engaging in strategic joint ventures, proprietary mounting-structure patent filings, and collaboration agreements with agricultural universities to validate crop-specific yield models and de-risk investments for commercial farming enterprises. Analyst Commentary "The agrivoltaics market has transitioned past the experimental phase into a vital commercial pillar of the global energy-food nexus," said a Senior Research Analyst at Stellar Market Research. "As land scarcity intensifies and climate volatility threatens traditional agriculture, co-locating solar infrastructure with crop production is no longer merely an environmental option—it is a fundamental economic imperative that secures both our food supply and our renewable energy future." Future Outlook Through the forecast period to 2034, the agrivoltaics market is poised for exponential mainstream integration. Expected technological breakthroughs in bifacial transparency, wireless sensor-driven microclimate management, and standardized modular mounting kits will continue to compress installation costs. As regulatory bodies streamline dual-use zoning laws and institutional ESG investors direct capital toward verifiable land-restoration assets, agrivoltaics will firmly establish itself as a cornerstone of resilient, climate-smart global agriculture. For further information, click the following link:https://www.stellarmr.com/report/req_sample/agrivoltaics-market/2915 About Stellar Market Research Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Address Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041 Email [email protected] Mobile +91 9607365656
    0 Comments ·0 Shares ·421 Views
  • Private Tutoring Market Shifts Toward One-to-One Digital Learning

    Market Estimation & Definition

    The global Private Tutoring Market is experiencing significant expansion as students, parents, and educational institutions increasingly recognize the value of personalized learning. According to Stellar Market Research, the market was valued at USD 151.3 billion in 2025 and is projected to reach USD 266.1 billion by 2032, registering a CAGR of 8.4% during the forecast period.

    Private tutoring refers to supplementary educational services delivered outside the formal classroom environment. These services are offered through one-to-one sessions, group classes, online platforms, and hybrid learning models to help students improve academic performance, prepare for competitive examinations, strengthen subject knowledge, and develop specialized skills. The market serves learners across K-12 education, higher education, language learning, professional certification, and test preparation.

    Growing academic competition, rising parental investment in education, and rapid digital transformation are making private tutoring an integral component of the global education ecosystem.

    Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Private-Tutoring-Market/971

    Market Growth Drivers & Opportunity

    Increasing competition for university admissions and professional careers continues to be one of the strongest drivers of the private tutoring market. Students are seeking additional academic support to improve grades, prepare for standardized examinations, and strengthen their understanding of complex subjects. According to the report, demand remains particularly strong in the K-12 segment, while STEM education accounts for a significant share of industry revenue.

    The rapid expansion of online education platforms has further accelerated market growth. Digital tutoring enables students to access qualified instructors regardless of location while offering flexible scheduling, interactive learning tools, and personalized study plans.

    Artificial intelligence is creating new opportunities across the tutoring industry. AI-powered learning platforms can evaluate student performance, identify learning gaps, recommend customized study materials, and provide real-time progress tracking. These capabilities improve learning outcomes while enabling tutoring providers to serve larger student populations efficiently. The report also highlights the growing adoption of AI-driven personalization and business-to-business tutoring partnerships with schools and educational institutions.

    Get Writing Tools
    Emerging economies present considerable growth opportunities as increasing disposable incomes, expanding internet connectivity, and greater awareness of educational advancement encourage families to invest in supplementary learning services.

    What Lies Ahead: Emerging Trends Shaping the Future

    The future of the private tutoring market is being shaped by technology-enabled personalized education. One of the industry's most influential trends is the emergence of hyper-personalized hybrid tutoring, where artificial intelligence complements experienced educators to deliver customized learning experiences. AI serves as a continuous learning assistant while tutors provide mentorship, motivation, and conceptual guidance.

    Hybrid learning models combining online convenience with offline instruction are becoming increasingly popular among students seeking flexibility without compromising educational quality.

    Gamification, adaptive learning software, virtual classrooms, and data-driven performance analytics are also transforming tutoring services by making learning more engaging and measurable. Institutions are increasingly adopting tutoring solutions as part of broader student success initiatives, creating additional opportunities for education technology providers.

    As lifelong learning becomes increasingly important, demand for professional certification courses, language training, coding education, and career-focused tutoring is expected to rise steadily throughout the forecast period.

    Segmentation Analysis

    According to the Stellar Market Research report, the Private Tutoring Market is segmented based on Type, Course, Mode, Application, End User, and Region.

    Among course categories, academic tutoring continues to dominate due to increasing emphasis on examination preparation and curriculum support. STEM subjects represent one of the fastest-growing areas as students pursue careers in science, technology, engineering, and mathematics.

    Based on mode, online and hybrid tutoring solutions are expanding rapidly because they provide greater accessibility, scheduling flexibility, and cost efficiency. Offline tutoring continues to maintain a significant presence, particularly for individualized coaching and high-stakes examination preparation.

    By application, the K-12 segment accounts for the largest market share as parents increasingly invest in supplementary education to enhance academic achievement and competitive performance.

    Country-Level Analysis

    United States

    The United States remains a leading market for private tutoring, supported by increasing academic competition, standardized testing requirements, and widespread adoption of digital education technologies. Parents continue investing in personalized tutoring services to strengthen student performance in mathematics, science, language learning, and college entrance examinations.

    Growing demand for virtual tutoring, AI-powered educational platforms, and flexible learning schedules is expected to support long-term market growth across the country.

    Germany

    Germany's private tutoring market is expanding steadily as students seek additional academic support for school examinations, university entrance preparation, and foreign language proficiency. Rising digitalization within the education sector and increasing acceptance of online learning platforms are contributing to market development.

    Government emphasis on educational quality and workforce skill development is encouraging greater adoption of specialized tutoring services for technical and vocational education, creating new opportunities for education providers.

    Get Writing Tools
    Competitive Analysis

    Chegg, Inc. (USA)
    Varsity Tutors (Nerdy Inc., USA)
    The Princeton Review (USA)
    Sylvan Learning (USA)
    Kumon Institute of Education (Japan/Global)
    Kaplan, Inc. (USA)
    Mathnasium (USA)
    Huntington Learning Center (USA)
    Pearson Plc (UK/Global)
    Tutor.com (USA)
    Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Private-Tutoring-Market/971

    Press Release Conclusion

    The global Private Tutoring Market is entering a new phase of growth driven by rising educational aspirations, technological innovation, and increasing demand for personalized learning solutions. As digital transformation reshapes education, tutoring providers are evolving from traditional classroom support to comprehensive, technology-enabled learning ecosystems.

    With strong demand across K-12 education, higher education, professional development, and lifelong learning, the market offers substantial opportunities for educators, investors, and technology companies. Organizations that successfully integrate AI-powered personalization, flexible delivery models, and high-quality instructional services will be well positioned to capitalize on the market's continued expansion through 2032.

    About Stellar Market Research:

    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Contact Stellar Market Research:

    3rd Floor, Navale IT Park, Phase 2

    Pune Banglore Highway, Narhe,

    Pune, Maharashtra 411041, India

    [email protected]

    +91 20 6630 3320 | +91 9607365656
    Private Tutoring Market Shifts Toward One-to-One Digital Learning Market Estimation & Definition The global Private Tutoring Market is experiencing significant expansion as students, parents, and educational institutions increasingly recognize the value of personalized learning. According to Stellar Market Research, the market was valued at USD 151.3 billion in 2025 and is projected to reach USD 266.1 billion by 2032, registering a CAGR of 8.4% during the forecast period. Private tutoring refers to supplementary educational services delivered outside the formal classroom environment. These services are offered through one-to-one sessions, group classes, online platforms, and hybrid learning models to help students improve academic performance, prepare for competitive examinations, strengthen subject knowledge, and develop specialized skills. The market serves learners across K-12 education, higher education, language learning, professional certification, and test preparation. Growing academic competition, rising parental investment in education, and rapid digital transformation are making private tutoring an integral component of the global education ecosystem. Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Private-Tutoring-Market/971 Market Growth Drivers & Opportunity Increasing competition for university admissions and professional careers continues to be one of the strongest drivers of the private tutoring market. Students are seeking additional academic support to improve grades, prepare for standardized examinations, and strengthen their understanding of complex subjects. According to the report, demand remains particularly strong in the K-12 segment, while STEM education accounts for a significant share of industry revenue. The rapid expansion of online education platforms has further accelerated market growth. Digital tutoring enables students to access qualified instructors regardless of location while offering flexible scheduling, interactive learning tools, and personalized study plans. Artificial intelligence is creating new opportunities across the tutoring industry. AI-powered learning platforms can evaluate student performance, identify learning gaps, recommend customized study materials, and provide real-time progress tracking. These capabilities improve learning outcomes while enabling tutoring providers to serve larger student populations efficiently. The report also highlights the growing adoption of AI-driven personalization and business-to-business tutoring partnerships with schools and educational institutions. Get Writing Tools Emerging economies present considerable growth opportunities as increasing disposable incomes, expanding internet connectivity, and greater awareness of educational advancement encourage families to invest in supplementary learning services. What Lies Ahead: Emerging Trends Shaping the Future The future of the private tutoring market is being shaped by technology-enabled personalized education. One of the industry's most influential trends is the emergence of hyper-personalized hybrid tutoring, where artificial intelligence complements experienced educators to deliver customized learning experiences. AI serves as a continuous learning assistant while tutors provide mentorship, motivation, and conceptual guidance. Hybrid learning models combining online convenience with offline instruction are becoming increasingly popular among students seeking flexibility without compromising educational quality. Gamification, adaptive learning software, virtual classrooms, and data-driven performance analytics are also transforming tutoring services by making learning more engaging and measurable. Institutions are increasingly adopting tutoring solutions as part of broader student success initiatives, creating additional opportunities for education technology providers. As lifelong learning becomes increasingly important, demand for professional certification courses, language training, coding education, and career-focused tutoring is expected to rise steadily throughout the forecast period. Segmentation Analysis According to the Stellar Market Research report, the Private Tutoring Market is segmented based on Type, Course, Mode, Application, End User, and Region. Among course categories, academic tutoring continues to dominate due to increasing emphasis on examination preparation and curriculum support. STEM subjects represent one of the fastest-growing areas as students pursue careers in science, technology, engineering, and mathematics. Based on mode, online and hybrid tutoring solutions are expanding rapidly because they provide greater accessibility, scheduling flexibility, and cost efficiency. Offline tutoring continues to maintain a significant presence, particularly for individualized coaching and high-stakes examination preparation. By application, the K-12 segment accounts for the largest market share as parents increasingly invest in supplementary education to enhance academic achievement and competitive performance. Country-Level Analysis United States The United States remains a leading market for private tutoring, supported by increasing academic competition, standardized testing requirements, and widespread adoption of digital education technologies. Parents continue investing in personalized tutoring services to strengthen student performance in mathematics, science, language learning, and college entrance examinations. Growing demand for virtual tutoring, AI-powered educational platforms, and flexible learning schedules is expected to support long-term market growth across the country. Germany Germany's private tutoring market is expanding steadily as students seek additional academic support for school examinations, university entrance preparation, and foreign language proficiency. Rising digitalization within the education sector and increasing acceptance of online learning platforms are contributing to market development. Government emphasis on educational quality and workforce skill development is encouraging greater adoption of specialized tutoring services for technical and vocational education, creating new opportunities for education providers. Get Writing Tools Competitive Analysis Chegg, Inc. (USA) Varsity Tutors (Nerdy Inc., USA) The Princeton Review (USA) Sylvan Learning (USA) Kumon Institute of Education (Japan/Global) Kaplan, Inc. (USA) Mathnasium (USA) Huntington Learning Center (USA) Pearson Plc (UK/Global) Tutor.com (USA) Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Private-Tutoring-Market/971 Press Release Conclusion The global Private Tutoring Market is entering a new phase of growth driven by rising educational aspirations, technological innovation, and increasing demand for personalized learning solutions. As digital transformation reshapes education, tutoring providers are evolving from traditional classroom support to comprehensive, technology-enabled learning ecosystems. With strong demand across K-12 education, higher education, professional development, and lifelong learning, the market offers substantial opportunities for educators, investors, and technology companies. Organizations that successfully integrate AI-powered personalization, flexible delivery models, and high-quality instructional services will be well positioned to capitalize on the market's continued expansion through 2032. About Stellar Market Research: Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Contact Stellar Market Research: 3rd Floor, Navale IT Park, Phase 2 Pune Banglore Highway, Narhe, Pune, Maharashtra 411041, India [email protected] +91 20 6630 3320 | +91 9607365656
    0 Comments ·0 Shares ·484 Views
  • The global Supercomputer Market is undergoing a profound architectural transformation, transitioning from traditional numerical simulation to complex artificial intelligence training, generative AI workloads, and real-time scientific modeling. According to a comprehensive market intelligence report published by Stellar Market Research, the market is valued at USD 13.29 billion in 2026 and is projected to scale to approximately USD 33.48 billion by 2035, expanding at a robust compound annual growth rate (CAGR) of 10.82% over the forecast period.


    Today, enterprise buyers and government bodies are moving beyond legacy CPU-centric clusters, prioritizing massively parallel architectures powered by advanced GPUs, custom AI accelerators, and high-bandwidth memory (HBM). This shift is dismantling historical barriers to entry, moving supercomputers out of exclusive national laboratory environments and into commercial data centers, cloud infrastructure providers, and specialized research facilities. As organizations race to secure computational supremacy, the market is witnessing an intense race for exascale capabilities, where hardware performance, energy-efficient liquid cooling, and modular scalability dictate competitive advantage.

    Key Findings from the Report
    Valuation Trajectory: The global supercomputer market is anchored at USD 13.29 billion in 2026, advancing toward a projected milestone of USD 33.48 billion by 2035 at a 10.82% CAGR.

    Segment Dominance: By technology type, vector processing and tightly connected cluster computer machines accounted for the highest revenue share, capturing approximately 43.4% of the market in 2025 due to their unmatched parallel processing density.

    Fastest-Growing Application: Government entities and defense sectors represent dominant end-use verticals, with government-backed HPC deployments expanding at a rapid CAGR of 9.6% through the forecast period.

    Commercial Diversification: Commercial industries—including financial services risk modeling, automotive crash simulations, and pharmaceutical drug discovery—now represent the fastest-growing demand tier outside traditional public sector procurement.

    Regional Leadership: North America commands the largest regional market share (approximately 41%), propelled by aggressive national research initiatives and heavy private-sector investments in generative AI infrastructure.

    Emerging Hotspot: The Asia-Pacific region is registering the fastest growth rate globally, driven by sovereign AI initiatives, massive public-private partnerships, and rapid data center expansions in India, Japan, and China.

    Infrastructure Shifts: Advanced direct-liquid-cooling (DLC) and intelligent power orchestration are emerging as mandatory integration criteria, directly addressing the soaring thermal and energy footprints of next-gen exascale racks.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/supercomputer-market/2647
    Market Drivers and Restraints
    Drivers
    Proliferation of AI/ML and Generative Workloads: The integration of AI inference and training into traditional HPC workflows has fundamentally altered performance benchmarks, compelling data center operators to deploy high-bandwidth GPU clusters to handle multi-parameter neural networks.

    Surge in Sovereign AI and National HPC Initiatives: Governments worldwide are heavily subsidizing domestic supercomputing ecosystems to safeguard national security, reduce foreign semiconductor supply chain dependencies, and foster regional technological autonomy.

    Complex Simulation Needs in Commercial Verticals: Automotive, aerospace, and energy enterprises are increasingly reliant on digital twins, high-fidelity CFD (Computational Fluid Dynamics), and seismic data processing to compress product development cycles.

    Restraints
    Exorbitant Capital Expenditure and Maintenance Costs: The immense upfront costs associated with procuring leadership-class supercomputers, coupled with specialized facility renovation requirements, restrict adoption among mid-sized enterprises.

    Severe Power Consumption and Thermal Management Challenges: High-density server racks generate extreme thermal output, creating significant infrastructural bottlenecks and regulatory scrutiny regarding data center carbon footprints.

    Technology, Regulation, and Sustainability Trends
    The supercomputer ecosystem is undergoing radical operational transformation to meet modern ESG mandates and efficiency targets. Modern infrastructure designs have shifted focus from raw FLOP delivery to energy-to-solution metrics. Operators are widely adopting intelligent power orchestration, dynamic voltage scaling, and advanced direct-liquid-cooling technologies to neutralize thermal bottlenecks.

    Concurrently, regulatory frameworks across major economies are tightening energy-efficiency standards for large-scale data centers, forcing vendors to build modular, sustainably powered computing clusters. Furthermore, the advent of Hybrid HPC—bridging on-premise supercomputers with cloud-based High-Performance Computing-as-a-Service (HPCaaS)—is democratizing access while minimizing capital depreciation risks.

    Regional Insights
    North America: Retains its stronghold as the primary regional market, underpinned by robust public-private initiatives such as the U.S. Department of Energy’s exascale programs and massive infrastructure commitments from hyperscale technology titans. Strategic investments in localized semiconductor packaging continue to reinforce regional supply chain resilience.

    Asia-Pacific: Exhibits the fastest growth velocity, spearheaded by extensive government funding in national supercomputing grids, smart city digitalization, and quantum-hybrid computing integration. Countries like Japan and India are rapidly scaling indigenous processing architectures to support regional scientific research and industrial competitiveness.

    Recent Industry Developments
    Nvidia Corporation (2026): Introduced the Rubin advanced platform and deployed over 35 new AI-HPC supercomputing installations across Europe, significantly accelerating large-scale model training and scientific simulations.

    Hewlett Packard Enterprise (2026): Maintained market leadership by securing six of the top ten positions in the TOP500 list of the world's fastest supercomputers—including Frontier, El Capitan, and Aurora—while scaling direct-liquid-cooling innovations.

    Dell Technologies Inc. (2026): Launched the PowerEdge XE8812 featuring NVIDIA Vera Rubin NVL4 architecture supporting up to 144 GPUs per rack, alongside collaborative development of the Department of Energy's Doudna supercomputer.

    Lenovo Group Limited (2024): Expanded its global enterprise footprint with the commercial rollout of advanced liquid-cooled high-performance computing systems tailored for energy-efficient data center operations.

    Atos SE (2025): Expanded European exascale computing collaborations under the EuroHPC Joint Undertaking, fortifying regional research autonomy and sovereign cloud infrastructure.

    Competitive Landscape
    The global supercomputer market features a highly consolidated and competitive vendor landscape characterized by strategic tier-1 technological alliances. Major market participants are focusing on turnkey system integration, proprietary interconnect fabrics, and comprehensive software toolchains to capture high-margin service contracts.

    Key market leaders—including Hewlett Packard Enterprise (HPE), Nvidia Corporation, Dell Technologies, Advanced Micro Devices (AMD), Intel Corporation, Lenovo Group, Fujitsu Limited, and NEC Corporation—are actively deploying strategic M&A, vertical integration, and joint-venture frameworks to maintain competitive superiority in the race to exascale and quantum-hybrid computing.

    Analyst Commentary
    "The supercomputer market has evolved past the traditional boundaries of academic research and defense modeling into the core engine of global commercial innovation," said a Senior Research Analyst at Stellar Market Research. "As organizations race to train complex generative AI models and execute real-time digital simulations, the competitive advantage no longer belongs solely to those with raw processing power, but to those who can master energy-efficient architectures, heterogeneous software stacks, and sustainable liquid-cooling infrastructures at scale."

    Future Outlook
    Through the forecast period to 2035, the supercomputer market is poised for sustained, high-velocity expansion. Demand will increasingly be catalyzed by the convergence of classical HPC with quantum computing accelerators, edge supercomputing nodes, and advanced AI frameworks.

    While supply chain resilience and power management will remain critical board-level considerations, continuous innovations in modular system design and cloud-native HPC delivery models will lower barriers to entry, unlocking broad-based commercial adoption across life sciences, financial engineering, and smart manufacturing.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/supercomputer-market/2647
    About Stellar Market Research
    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Address
    Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041

    Email
    [email protected]

    Mobile
    +91 9607365656


    #Energy Sector HPC, Seismic Data Processing, Smart Grid Optimization, Oil Gas Reservoir Simulation, Renewable Integration Supercomputing
    The global Supercomputer Market is undergoing a profound architectural transformation, transitioning from traditional numerical simulation to complex artificial intelligence training, generative AI workloads, and real-time scientific modeling. According to a comprehensive market intelligence report published by Stellar Market Research, the market is valued at USD 13.29 billion in 2026 and is projected to scale to approximately USD 33.48 billion by 2035, expanding at a robust compound annual growth rate (CAGR) of 10.82% over the forecast period. Today, enterprise buyers and government bodies are moving beyond legacy CPU-centric clusters, prioritizing massively parallel architectures powered by advanced GPUs, custom AI accelerators, and high-bandwidth memory (HBM). This shift is dismantling historical barriers to entry, moving supercomputers out of exclusive national laboratory environments and into commercial data centers, cloud infrastructure providers, and specialized research facilities. As organizations race to secure computational supremacy, the market is witnessing an intense race for exascale capabilities, where hardware performance, energy-efficient liquid cooling, and modular scalability dictate competitive advantage. Key Findings from the Report Valuation Trajectory: The global supercomputer market is anchored at USD 13.29 billion in 2026, advancing toward a projected milestone of USD 33.48 billion by 2035 at a 10.82% CAGR. Segment Dominance: By technology type, vector processing and tightly connected cluster computer machines accounted for the highest revenue share, capturing approximately 43.4% of the market in 2025 due to their unmatched parallel processing density. Fastest-Growing Application: Government entities and defense sectors represent dominant end-use verticals, with government-backed HPC deployments expanding at a rapid CAGR of 9.6% through the forecast period. Commercial Diversification: Commercial industries—including financial services risk modeling, automotive crash simulations, and pharmaceutical drug discovery—now represent the fastest-growing demand tier outside traditional public sector procurement. Regional Leadership: North America commands the largest regional market share (approximately 41%), propelled by aggressive national research initiatives and heavy private-sector investments in generative AI infrastructure. Emerging Hotspot: The Asia-Pacific region is registering the fastest growth rate globally, driven by sovereign AI initiatives, massive public-private partnerships, and rapid data center expansions in India, Japan, and China. Infrastructure Shifts: Advanced direct-liquid-cooling (DLC) and intelligent power orchestration are emerging as mandatory integration criteria, directly addressing the soaring thermal and energy footprints of next-gen exascale racks. For further information, click the following link:https://www.stellarmr.com/report/req_sample/supercomputer-market/2647 Market Drivers and Restraints Drivers Proliferation of AI/ML and Generative Workloads: The integration of AI inference and training into traditional HPC workflows has fundamentally altered performance benchmarks, compelling data center operators to deploy high-bandwidth GPU clusters to handle multi-parameter neural networks. Surge in Sovereign AI and National HPC Initiatives: Governments worldwide are heavily subsidizing domestic supercomputing ecosystems to safeguard national security, reduce foreign semiconductor supply chain dependencies, and foster regional technological autonomy. Complex Simulation Needs in Commercial Verticals: Automotive, aerospace, and energy enterprises are increasingly reliant on digital twins, high-fidelity CFD (Computational Fluid Dynamics), and seismic data processing to compress product development cycles. Restraints Exorbitant Capital Expenditure and Maintenance Costs: The immense upfront costs associated with procuring leadership-class supercomputers, coupled with specialized facility renovation requirements, restrict adoption among mid-sized enterprises. Severe Power Consumption and Thermal Management Challenges: High-density server racks generate extreme thermal output, creating significant infrastructural bottlenecks and regulatory scrutiny regarding data center carbon footprints. Technology, Regulation, and Sustainability Trends The supercomputer ecosystem is undergoing radical operational transformation to meet modern ESG mandates and efficiency targets. Modern infrastructure designs have shifted focus from raw FLOP delivery to energy-to-solution metrics. Operators are widely adopting intelligent power orchestration, dynamic voltage scaling, and advanced direct-liquid-cooling technologies to neutralize thermal bottlenecks. Concurrently, regulatory frameworks across major economies are tightening energy-efficiency standards for large-scale data centers, forcing vendors to build modular, sustainably powered computing clusters. Furthermore, the advent of Hybrid HPC—bridging on-premise supercomputers with cloud-based High-Performance Computing-as-a-Service (HPCaaS)—is democratizing access while minimizing capital depreciation risks. Regional Insights North America: Retains its stronghold as the primary regional market, underpinned by robust public-private initiatives such as the U.S. Department of Energy’s exascale programs and massive infrastructure commitments from hyperscale technology titans. Strategic investments in localized semiconductor packaging continue to reinforce regional supply chain resilience. Asia-Pacific: Exhibits the fastest growth velocity, spearheaded by extensive government funding in national supercomputing grids, smart city digitalization, and quantum-hybrid computing integration. Countries like Japan and India are rapidly scaling indigenous processing architectures to support regional scientific research and industrial competitiveness. Recent Industry Developments Nvidia Corporation (2026): Introduced the Rubin advanced platform and deployed over 35 new AI-HPC supercomputing installations across Europe, significantly accelerating large-scale model training and scientific simulations. Hewlett Packard Enterprise (2026): Maintained market leadership by securing six of the top ten positions in the TOP500 list of the world's fastest supercomputers—including Frontier, El Capitan, and Aurora—while scaling direct-liquid-cooling innovations. Dell Technologies Inc. (2026): Launched the PowerEdge XE8812 featuring NVIDIA Vera Rubin NVL4 architecture supporting up to 144 GPUs per rack, alongside collaborative development of the Department of Energy's Doudna supercomputer. Lenovo Group Limited (2024): Expanded its global enterprise footprint with the commercial rollout of advanced liquid-cooled high-performance computing systems tailored for energy-efficient data center operations. Atos SE (2025): Expanded European exascale computing collaborations under the EuroHPC Joint Undertaking, fortifying regional research autonomy and sovereign cloud infrastructure. Competitive Landscape The global supercomputer market features a highly consolidated and competitive vendor landscape characterized by strategic tier-1 technological alliances. Major market participants are focusing on turnkey system integration, proprietary interconnect fabrics, and comprehensive software toolchains to capture high-margin service contracts. Key market leaders—including Hewlett Packard Enterprise (HPE), Nvidia Corporation, Dell Technologies, Advanced Micro Devices (AMD), Intel Corporation, Lenovo Group, Fujitsu Limited, and NEC Corporation—are actively deploying strategic M&A, vertical integration, and joint-venture frameworks to maintain competitive superiority in the race to exascale and quantum-hybrid computing. Analyst Commentary "The supercomputer market has evolved past the traditional boundaries of academic research and defense modeling into the core engine of global commercial innovation," said a Senior Research Analyst at Stellar Market Research. "As organizations race to train complex generative AI models and execute real-time digital simulations, the competitive advantage no longer belongs solely to those with raw processing power, but to those who can master energy-efficient architectures, heterogeneous software stacks, and sustainable liquid-cooling infrastructures at scale." Future Outlook Through the forecast period to 2035, the supercomputer market is poised for sustained, high-velocity expansion. Demand will increasingly be catalyzed by the convergence of classical HPC with quantum computing accelerators, edge supercomputing nodes, and advanced AI frameworks. While supply chain resilience and power management will remain critical board-level considerations, continuous innovations in modular system design and cloud-native HPC delivery models will lower barriers to entry, unlocking broad-based commercial adoption across life sciences, financial engineering, and smart manufacturing. For further information, click the following link:https://www.stellarmr.com/report/req_sample/supercomputer-market/2647 About Stellar Market Research Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Address Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041 Email [email protected] Mobile +91 9607365656 #Energy Sector HPC, Seismic Data Processing, Smart Grid Optimization, Oil Gas Reservoir Simulation, Renewable Integration Supercomputing
    0 Comments ·0 Shares ·268 Views
  • The global Vacuum Therapy Devices Market is experiencing a structural paradigm shift toward accelerated healing technologies, according to a comprehensive market intelligence report released by Stellar Market Research. Valued at USD 2.01 billion in 2024, the market is projected to expand steadily to USD 2.73 billion by 2032. This trajectory is strategically underpinned by rising healthcare expenditures, increasing demand for non-invasive wound management solutions, and the surging prevalence of chronic conditions such as diabetic foot ulcers and surgical site infections across global health systems.

    The modern healthcare ecosystem is under intense pressure to reduce hospital readmission rates, shorten patient recovery times, and optimize nursing labor efficiency. Negative Pressure Wound Therapy (NPWT) and vacuum-assisted closure systems have evolved from specialized hospital interventions into essential multi-setting modalities spanning acute care facilities, outpatient clinics, and home healthcare environments. As healthcare providers pivot toward value-based care models, manufacturers are heavily investing in ultra-portable, disposable, and digitally integrated vacuum therapy units. This transformation is eliminating clinical bottlenecks, enabling patient-centric ambulatory care, and unlocking high-margin commercial opportunities for device innovators and medical technology distributors.

    Key Findings from the Report
    Market Valuation & Growth: The global vacuum therapy devices market reached USD 2.01 billion in 2024 and is projected to scale to USD 2.73 billion by 2032, registering a compound annual growth rate (CAGR) of 3.9% over the forecast period.

    Dominant Modality: Traditional and conventional stationary NPWT systems maintained the largest revenue share in 2024 due to high-volume applications in critical care wards and complex trauma centers.

    Fastest-Growing Segment: Single-use, disposable vacuum therapy devices are exhibiting the highest CAGR, propelled by patient preference for ambulatory freedom and institutional cost containment.

    Application Insights: Wound care management—specifically targeting diabetic ulcers, pressure sores, and burns—dominates clinical adoption, accounting for the lion's share of market demand.

    Regional Dominance: North America secured the leading revenue share in 2024, supported by sophisticated healthcare reimbursement frameworks and high adoption of advanced medical devices.

    Emerging Hotspot: Asia Pacific is identified as the fastest-growing regional market, driven by expanding healthcare infrastructure in China and India, alongside a rising diabetic population.

    Investment & Partnership Relevance: Strategic mergers, acquisitions, and regional distributor partnerships are the primary competitive levers for market entrants seeking to expand geographic footprints.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/monkey-pox-vaccine-and-treatment-market/2670

    Market Drivers and Restraints
    Driver 1: Surge in Chronic Wounds and Diabetes Prevalence: The global escalation of diabetes mellitus and lifestyle-associated metabolic disorders has triggered a dramatic rise in hard-to-heal chronic wounds, such as diabetic foot ulcers, directly fueling continuous demand for vacuum therapy systems.

    Driver 2: Shift Toward Portable and Homecare Medical Devices: Technological innovations yielding lightweight, pocket-sized, and disposable NPWT pumps allow patients to self-manage treatments outside hospitals, significantly boosting ambulatory adoption.

    Driver 3: Superior Clinical Efficacy and Faster Healing Rates: Clinical validation demonstrating that vacuum therapy reduces edema, promotes granulation tissue formation, and decreases bacterial colonization accelerates clinical guideline endorsement.

    Restraint 1: High Equipment and Consumable Costs: The premium pricing associated with advanced electronic vacuum pumps, proprietary canisters, and sterile dressing kits restricts rapid adoption in resource-constrained developing healthcare systems.

    Restraint 2: Stringent Reimbursement and Regulatory Hurdles: Complex clearance pathways from agencies like the US FDA alongside restrictive reimbursement codes for home-based NPWT create commercialization friction for emerging manufacturers.

    Technology, Regulation, and Sustainability Trends
    The vacuum therapy devices sector is undergoing a profound technological and operational evolution. The integration of smart sensors into NPWT units now enables real-time monitoring of exudate volume, pressure leaks, and dressing saturation, feeding clinical data directly into electronic health record (EHR) systems. Regulatory bodies are concurrently enforcing stricter biocompatibility and sterilization validation standards, compelling manufacturers to upgrade manufacturing cleanrooms. Simultaneously, environmental sustainability (ESG) pressures are steering R&D teams toward eco-friendly, recyclable chassis materials and minimizing single-use plastic waste in disposable pump product lines without compromising patient safety or sterility.

    Regional Insights
    North America commands the leading revenue share in the global market, reinforced by widespread medical device reimbursement policies, early clinical adoption of advanced wound care products, and prominent domestic medtech headquarters. Meanwhile, the Asia Pacific region represents the most lucrative emerging market frontier. Accelerated by government-backed universal health coverage initiatives in India, rapid hospital infrastructure buildouts across Southeast Asia, and a vast geriatric demographic base in Japan and China, APAC is witnessing robust double-digit expansion in clinical procurement volumes.

    Recent Industry Developments
    3M Company (2025): Launched an advanced connected-care iteration of its V.A.C. Therapy system, integrating wireless compliance tracking that reduced clinician follow-up times by 18% in outpatient trials.

    Smith & Nephew plc (2024): Expanded its PICO single-use negative pressure wound therapy manufacturing capacity in Europe, securing a 12% boost in regional supply chain responsiveness for ambulatory devices.

    Coloplast A/S (2024): Completed the strategic acquisition of a specialized advanced wound care portfolio, expanding its footprint in European institutional procurement networks.

    Medela AG (2023): Introduced next-generation quiet-pump technology for its Invia Liberty NPWT system, improving patient sleep quality and clinical comfort scores during extended hospital stays.

    ConvaTec Inc. (2023): Received expanded FDA 510(k) clearance for a redesigned portable vacuum therapy dressing kit, streamlining application procedures for visiting nurse services.

    Competitive Landscape
    The global competitive arena is characterized by intense rivalry among established medical technology conglomerates and nimble domestic innovators. Leading market participants—including 3M (KCI), Smith & Nephew, ConvaTec, Medela, and B. Braun Melsungen—are actively fortifying their market positions through strategic product extensions, patent acquisitions, and direct-to-clinic distribution agreements. Major players focus heavily on portfolio diversification, combining mechanical pump reliability with smart-digital user interfaces to capture institutional customer loyalty.

    Analyst Commentary
    "The vacuum therapy devices market is transitioning from a niche hospital intervention into an essential cornerstone of global ambulatory and chronic care management," said a Senior Research Analyst at Stellar Market Research. "As healthcare systems prioritize cost-efficiency and reduced length-of-stay metrics, innovators who successfully blend clinical efficacy with user-friendly, portable, and digitally connected NPWT designs will capture outsized market share through the next decade."

    Future Outlook
    Looking ahead to 2032, the vacuum therapy devices market is forecast to maintain steady momentum. Growth will increasingly be catalyzed by artificial intelligence-driven wound assessment algorithms, automated pressure adjustments, and broader insurance coverage for home-based therapies. While pricing pressures in emerging regions will challenge margin expansion, ongoing R&D focused on cost-effective disposable devices and strategic cross-border partnerships will ensure sustained industry growth and improved patient outcomes worldwide.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/monkey-pox-vaccine-and-treatment-market/2670


    About Stellar Market Research:

    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Address
    Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041

    Email
    [email protected]

    Mobile
    +91 9607365656
    The global Vacuum Therapy Devices Market is experiencing a structural paradigm shift toward accelerated healing technologies, according to a comprehensive market intelligence report released by Stellar Market Research. Valued at USD 2.01 billion in 2024, the market is projected to expand steadily to USD 2.73 billion by 2032. This trajectory is strategically underpinned by rising healthcare expenditures, increasing demand for non-invasive wound management solutions, and the surging prevalence of chronic conditions such as diabetic foot ulcers and surgical site infections across global health systems. The modern healthcare ecosystem is under intense pressure to reduce hospital readmission rates, shorten patient recovery times, and optimize nursing labor efficiency. Negative Pressure Wound Therapy (NPWT) and vacuum-assisted closure systems have evolved from specialized hospital interventions into essential multi-setting modalities spanning acute care facilities, outpatient clinics, and home healthcare environments. As healthcare providers pivot toward value-based care models, manufacturers are heavily investing in ultra-portable, disposable, and digitally integrated vacuum therapy units. This transformation is eliminating clinical bottlenecks, enabling patient-centric ambulatory care, and unlocking high-margin commercial opportunities for device innovators and medical technology distributors. Key Findings from the Report Market Valuation & Growth: The global vacuum therapy devices market reached USD 2.01 billion in 2024 and is projected to scale to USD 2.73 billion by 2032, registering a compound annual growth rate (CAGR) of 3.9% over the forecast period. Dominant Modality: Traditional and conventional stationary NPWT systems maintained the largest revenue share in 2024 due to high-volume applications in critical care wards and complex trauma centers. Fastest-Growing Segment: Single-use, disposable vacuum therapy devices are exhibiting the highest CAGR, propelled by patient preference for ambulatory freedom and institutional cost containment. Application Insights: Wound care management—specifically targeting diabetic ulcers, pressure sores, and burns—dominates clinical adoption, accounting for the lion's share of market demand. Regional Dominance: North America secured the leading revenue share in 2024, supported by sophisticated healthcare reimbursement frameworks and high adoption of advanced medical devices. Emerging Hotspot: Asia Pacific is identified as the fastest-growing regional market, driven by expanding healthcare infrastructure in China and India, alongside a rising diabetic population. Investment & Partnership Relevance: Strategic mergers, acquisitions, and regional distributor partnerships are the primary competitive levers for market entrants seeking to expand geographic footprints. For further information, click the following link:https://www.stellarmr.com/report/req_sample/monkey-pox-vaccine-and-treatment-market/2670 Market Drivers and Restraints Driver 1: Surge in Chronic Wounds and Diabetes Prevalence: The global escalation of diabetes mellitus and lifestyle-associated metabolic disorders has triggered a dramatic rise in hard-to-heal chronic wounds, such as diabetic foot ulcers, directly fueling continuous demand for vacuum therapy systems. Driver 2: Shift Toward Portable and Homecare Medical Devices: Technological innovations yielding lightweight, pocket-sized, and disposable NPWT pumps allow patients to self-manage treatments outside hospitals, significantly boosting ambulatory adoption. Driver 3: Superior Clinical Efficacy and Faster Healing Rates: Clinical validation demonstrating that vacuum therapy reduces edema, promotes granulation tissue formation, and decreases bacterial colonization accelerates clinical guideline endorsement. Restraint 1: High Equipment and Consumable Costs: The premium pricing associated with advanced electronic vacuum pumps, proprietary canisters, and sterile dressing kits restricts rapid adoption in resource-constrained developing healthcare systems. Restraint 2: Stringent Reimbursement and Regulatory Hurdles: Complex clearance pathways from agencies like the US FDA alongside restrictive reimbursement codes for home-based NPWT create commercialization friction for emerging manufacturers. Technology, Regulation, and Sustainability Trends The vacuum therapy devices sector is undergoing a profound technological and operational evolution. The integration of smart sensors into NPWT units now enables real-time monitoring of exudate volume, pressure leaks, and dressing saturation, feeding clinical data directly into electronic health record (EHR) systems. Regulatory bodies are concurrently enforcing stricter biocompatibility and sterilization validation standards, compelling manufacturers to upgrade manufacturing cleanrooms. Simultaneously, environmental sustainability (ESG) pressures are steering R&D teams toward eco-friendly, recyclable chassis materials and minimizing single-use plastic waste in disposable pump product lines without compromising patient safety or sterility. Regional Insights North America commands the leading revenue share in the global market, reinforced by widespread medical device reimbursement policies, early clinical adoption of advanced wound care products, and prominent domestic medtech headquarters. Meanwhile, the Asia Pacific region represents the most lucrative emerging market frontier. Accelerated by government-backed universal health coverage initiatives in India, rapid hospital infrastructure buildouts across Southeast Asia, and a vast geriatric demographic base in Japan and China, APAC is witnessing robust double-digit expansion in clinical procurement volumes. Recent Industry Developments 3M Company (2025): Launched an advanced connected-care iteration of its V.A.C. Therapy system, integrating wireless compliance tracking that reduced clinician follow-up times by 18% in outpatient trials. Smith & Nephew plc (2024): Expanded its PICO single-use negative pressure wound therapy manufacturing capacity in Europe, securing a 12% boost in regional supply chain responsiveness for ambulatory devices. Coloplast A/S (2024): Completed the strategic acquisition of a specialized advanced wound care portfolio, expanding its footprint in European institutional procurement networks. Medela AG (2023): Introduced next-generation quiet-pump technology for its Invia Liberty NPWT system, improving patient sleep quality and clinical comfort scores during extended hospital stays. ConvaTec Inc. (2023): Received expanded FDA 510(k) clearance for a redesigned portable vacuum therapy dressing kit, streamlining application procedures for visiting nurse services. Competitive Landscape The global competitive arena is characterized by intense rivalry among established medical technology conglomerates and nimble domestic innovators. Leading market participants—including 3M (KCI), Smith & Nephew, ConvaTec, Medela, and B. Braun Melsungen—are actively fortifying their market positions through strategic product extensions, patent acquisitions, and direct-to-clinic distribution agreements. Major players focus heavily on portfolio diversification, combining mechanical pump reliability with smart-digital user interfaces to capture institutional customer loyalty. Analyst Commentary "The vacuum therapy devices market is transitioning from a niche hospital intervention into an essential cornerstone of global ambulatory and chronic care management," said a Senior Research Analyst at Stellar Market Research. "As healthcare systems prioritize cost-efficiency and reduced length-of-stay metrics, innovators who successfully blend clinical efficacy with user-friendly, portable, and digitally connected NPWT designs will capture outsized market share through the next decade." Future Outlook Looking ahead to 2032, the vacuum therapy devices market is forecast to maintain steady momentum. Growth will increasingly be catalyzed by artificial intelligence-driven wound assessment algorithms, automated pressure adjustments, and broader insurance coverage for home-based therapies. While pricing pressures in emerging regions will challenge margin expansion, ongoing R&D focused on cost-effective disposable devices and strategic cross-border partnerships will ensure sustained industry growth and improved patient outcomes worldwide. For further information, click the following link:https://www.stellarmr.com/report/req_sample/monkey-pox-vaccine-and-treatment-market/2670 About Stellar Market Research: Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Address Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041 Email [email protected] Mobile +91 9607365656
    0 Comments ·0 Shares ·590 Views
  • How Will Technological Advancements Shape the Gas Detection Equipment Market by 2034?

    Gas Detection Equipment Market Overview

    The Gas Detection Equipment Market report provides an in-depth analysis that is required to make informed industry decisions and develop strategic growth plans. Regardless of the production method or cost structures, the Gas Detection Equipment market report provides a comprehensive understanding of advanced tactics and strategies.

    Gas Detection Equipment Market Forecast

    The Gas Detection Equipment size was valued at USD 8.08 Bn in 2025, and the Gas Detection Equipment revenue is growing at a CAGR of 9.5% from 2026 to 2034, reaching USD 18.29 Bn by 2034.

    Please connect with our representative, who will ensure you to get a report sample here @https://www.maximizemarketresearch.com/request-sample/32518/

    Gas Detection Equipment Market Report Scope and Research Methodology

    The report offers an extensive examination of top players' strategies within the Gas Detection Equipment industry, coupled with an in-depth analysis of market segments and regional dynamics. In-depth insights into market dynamics, encompassing drivers, restraints, opportunities, and challenges, are provided both on a regional and segmental basis within the Gas Detection Equipment Market report. Additionally, the report presents import/export consumption, supply and demand, pricing, costs, revenue, and gross margins data, serving as an invaluable guide for investors.

    The data for the Gas Detection Equipment Market report was meticulously gathered through a combination of primary and secondary research methods, ensuring its authenticity. Primary research methods employed encompassed questionnaire distribution, surveys, and telephone interviews with Gas Detection Equipment industry experts, market leaders, marketing professionals, and entrepreneurs. The report's estimates of global and regional Gas Detection Equipment market size were derived using a bottom-up approach. Furthermore, the strengths and weaknesses of Gas Detection Equipment key players within the industry are outlined using SWOT analysis.

    Gas Detection Equipment Market Regional Insights

    The report delves into the Gas Detection Equipment business in great depth, segmenting it into numerous locations. North America, South America, Europe, Asia Pacific (APAC), Africa, and the Middle East are evaluated by region and country in the study. In the Gas Detection Equipment market report, regional markets are thoroughly investigated in order to uncover regional market trends, restrictions, and possible prospects.

    Gas Detection Equipment Market Segmentation

    by Type

    Fixed Gas Detector
    Portable Gas Detector

    by Technology

    Semiconductor
    Infrared (IR)
    Laser-based Detection
    Catalytic

    by End Use Type

    Oil and Gas
    Chemicals and Petrochemicals
    Water and Wastewater
    Metal and Mining
    Utilities
    Other

    Request Free Sample Copy:https://www.maximizemarketresearch.com/request-sample/32518/

    Gas Detection Equipment Market Key Players

    North America

    1. Honeywell International, Inc. – Charlotte, North Carolina, U.S.
    2. Emerson Electric Co. – St. Louis, Missouri, U.S.
    3. Industrial Scientific Corporation – Pittsburgh, Pennsylvania, U.S.
    4. MSA Safety Incorporated – Cranberry Township, Pennsylvania, U.S.
    5. Teledyne Technologies Incorporated – Thousand Oaks, California, U.S.

    Europe

    1. Drägerwerk AG & Co. KGaA – Lübeck, Germany
    2. Siemens AG – Munich, Germany
    3. Halma plc (Crowcon Detection Instruments) – Amersham, United Kingdom
    4. GfG Gesellschaft für Gerätebau mbH – Dortmund, Germany
    5. Sensitron S.r.l. – Cornaredo, Italy

    Asia-Pacific

    1. Hanwei Electronics Group Corporation – Zhengzhou, China
    2. New Cosmos Electric Co., Ltd. – Osaka, Japan
    3. Figaro Engineering Inc. – Osaka, Japan
    4. Riken Keiki Co., Ltd. – Tokyo, Japan
    5. Nissha Co., Ltd. – Kyoto, Japan

    Key Offerings:

    A detailed market overview
    Market Share, Size & Forecast by Revenue | 2026−2034
    Market Dynamics – Growth Drivers, Restraints, Investment Opportunities, and Key Trends
    Market Segmentation – A detailed analysis by segments and sub-segments
    Regional Insights
    Competitive Landscape – Top Key Vendors and Other Prominent Vendors
    More Trending From MMR:

    Global ImmuNotherapy Drugs Market https://www.maximizemarketresearch.com/market-report/global-immuNotherapy-drugs-market/6859/
    Global Embryo Incubator Market https://www.maximizemarketresearch.com/market-report/global-embryo-incubator-market/25403/
    Digestive Health Market https://www.maximizemarketresearch.com/market-report/digestive-health-market/165193/

    About Maximize Market Research:

    Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Contact Maximize Market Research:

    3rd Floor, Naval IT Park, Phase 2

    Pune Banglore Highway, Narhe

    Pune, Maharashtra 411041, India

    [email protected]

    +91 96071 95908, +91 9607365656
    How Will Technological Advancements Shape the Gas Detection Equipment Market by 2034? Gas Detection Equipment Market Overview The Gas Detection Equipment Market report provides an in-depth analysis that is required to make informed industry decisions and develop strategic growth plans. Regardless of the production method or cost structures, the Gas Detection Equipment market report provides a comprehensive understanding of advanced tactics and strategies. Gas Detection Equipment Market Forecast The Gas Detection Equipment size was valued at USD 8.08 Bn in 2025, and the Gas Detection Equipment revenue is growing at a CAGR of 9.5% from 2026 to 2034, reaching USD 18.29 Bn by 2034. Please connect with our representative, who will ensure you to get a report sample here @https://www.maximizemarketresearch.com/request-sample/32518/ Gas Detection Equipment Market Report Scope and Research Methodology The report offers an extensive examination of top players' strategies within the Gas Detection Equipment industry, coupled with an in-depth analysis of market segments and regional dynamics. In-depth insights into market dynamics, encompassing drivers, restraints, opportunities, and challenges, are provided both on a regional and segmental basis within the Gas Detection Equipment Market report. Additionally, the report presents import/export consumption, supply and demand, pricing, costs, revenue, and gross margins data, serving as an invaluable guide for investors. The data for the Gas Detection Equipment Market report was meticulously gathered through a combination of primary and secondary research methods, ensuring its authenticity. Primary research methods employed encompassed questionnaire distribution, surveys, and telephone interviews with Gas Detection Equipment industry experts, market leaders, marketing professionals, and entrepreneurs. The report's estimates of global and regional Gas Detection Equipment market size were derived using a bottom-up approach. Furthermore, the strengths and weaknesses of Gas Detection Equipment key players within the industry are outlined using SWOT analysis. Gas Detection Equipment Market Regional Insights The report delves into the Gas Detection Equipment business in great depth, segmenting it into numerous locations. North America, South America, Europe, Asia Pacific (APAC), Africa, and the Middle East are evaluated by region and country in the study. In the Gas Detection Equipment market report, regional markets are thoroughly investigated in order to uncover regional market trends, restrictions, and possible prospects. Gas Detection Equipment Market Segmentation by Type Fixed Gas Detector Portable Gas Detector by Technology Semiconductor Infrared (IR) Laser-based Detection Catalytic by End Use Type Oil and Gas Chemicals and Petrochemicals Water and Wastewater Metal and Mining Utilities Other Request Free Sample Copy:https://www.maximizemarketresearch.com/request-sample/32518/ Gas Detection Equipment Market Key Players North America 1. Honeywell International, Inc. – Charlotte, North Carolina, U.S. 2. Emerson Electric Co. – St. Louis, Missouri, U.S. 3. Industrial Scientific Corporation – Pittsburgh, Pennsylvania, U.S. 4. MSA Safety Incorporated – Cranberry Township, Pennsylvania, U.S. 5. Teledyne Technologies Incorporated – Thousand Oaks, California, U.S. Europe 1. Drägerwerk AG & Co. KGaA – Lübeck, Germany 2. Siemens AG – Munich, Germany 3. Halma plc (Crowcon Detection Instruments) – Amersham, United Kingdom 4. GfG Gesellschaft für Gerätebau mbH – Dortmund, Germany 5. Sensitron S.r.l. – Cornaredo, Italy Asia-Pacific 1. Hanwei Electronics Group Corporation – Zhengzhou, China 2. New Cosmos Electric Co., Ltd. – Osaka, Japan 3. Figaro Engineering Inc. – Osaka, Japan 4. Riken Keiki Co., Ltd. – Tokyo, Japan 5. Nissha Co., Ltd. – Kyoto, Japan Key Offerings: A detailed market overview Market Share, Size & Forecast by Revenue | 2026−2034 Market Dynamics – Growth Drivers, Restraints, Investment Opportunities, and Key Trends Market Segmentation – A detailed analysis by segments and sub-segments Regional Insights Competitive Landscape – Top Key Vendors and Other Prominent Vendors More Trending From MMR: Global ImmuNotherapy Drugs Market https://www.maximizemarketresearch.com/market-report/global-immuNotherapy-drugs-market/6859/ Global Embryo Incubator Market https://www.maximizemarketresearch.com/market-report/global-embryo-incubator-market/25403/ Digestive Health Market https://www.maximizemarketresearch.com/market-report/digestive-health-market/165193/ About Maximize Market Research: Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Contact Maximize Market Research: 3rd Floor, Naval IT Park, Phase 2 Pune Banglore Highway, Narhe Pune, Maharashtra 411041, India [email protected] +91 96071 95908, +91 9607365656
    0 Comments ·0 Shares ·482 Views
More Results