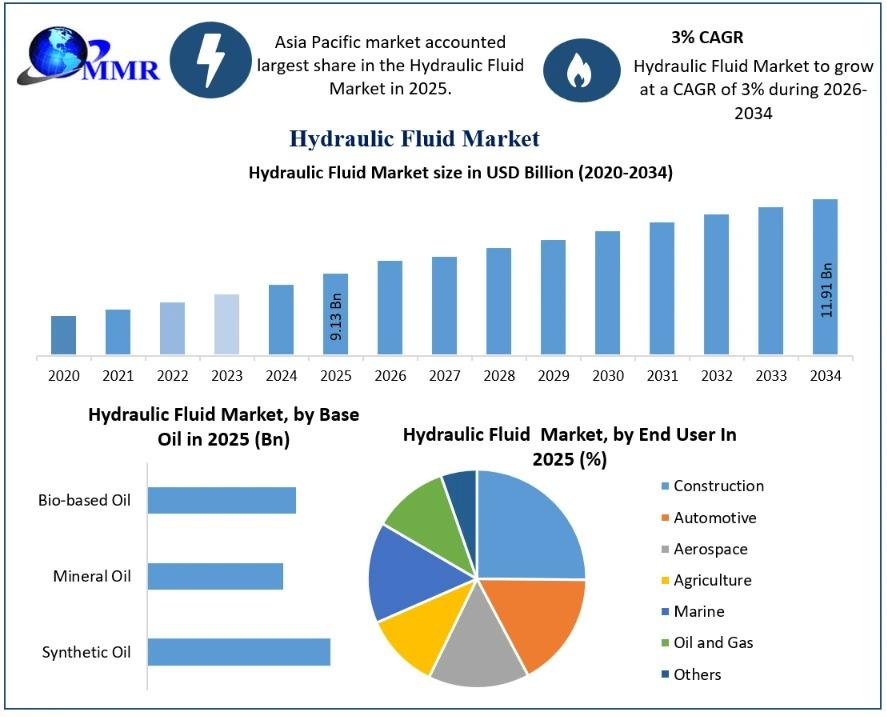
• Hydraulic Fluid Market 2034 Outlook: USD 11.91 Billion Revenue Forecast at 3% CAGR
    Overview:

    The global Hydraulic Fluid Market was valued at USD 9.13 billion in 2025 and is projected to reach USD 11.91 billion by 2034, expanding at a CAGR of 3% during 2026–2034, according to Maximize Market Research. Increasing construction activities, industrial automation, agricultural mechanization, and demand for energy-efficient hydraulic systems are supporting industry expansion.

    The Hydraulic Fluid Market plays a critical role in transmitting power, reducing friction, controlling operating temperatures, and protecting hydraulic machinery from corrosion and wear. Hydraulic fluids are widely utilized in excavators, cranes, tractors, manufacturing equipment, marine machinery, and industrial power systems.

    Download a Free Sample Report Today:

    https://www.maximizemarketresearch.com/request-sample/32740/
    Hydraulic Fluid Market 2034 Outlook: USD 11.91 Billion Revenue Forecast at 3% CAGR Overview: The global Hydraulic Fluid Market was valued at USD 9.13 billion in 2025 and is projected to reach USD 11.91 billion by 2034, expanding at a CAGR of 3% during 2026–2034, according to Maximize Market Research. Increasing construction activities, industrial automation, agricultural mechanization, and demand for energy-efficient hydraulic systems are supporting industry expansion. The Hydraulic Fluid Market plays a critical role in transmitting power, reducing friction, controlling operating temperatures, and protecting hydraulic machinery from corrosion and wear. Hydraulic fluids are widely utilized in excavators, cranes, tractors, manufacturing equipment, marine machinery, and industrial power systems. Download a Free Sample Report Today: https://www.maximizemarketresearch.com/request-sample/32740/
    0 Comments ·0 Shares ·51 Views
  • The Carbon Capture, Utilization, and Storage (CCUS) Market According to the latest research insights from Stellar Market Research, the global CCUS market is experiencing a paradigm shift, crossing critical valuation milestones as heavy industries accelerate decarbonization roadmaps to comply with stringent global emission frameworks.

    The global industrial landscape is undergoing a massive structural transformation, shifting from voluntary carbon-reduction pledges to mandatory, compliance-driven decarbonization. As international regulatory bodies enforce tighter carbon pricing mechanisms—such as the European Union’s Emissions Trading System (ETS) and Carbon Border Adjustment Mechanism (CBAM)—heavy-emitting sectors like power generation, cement, steel, and chemicals can no longer treat carbon management as an afterthought.

    Key Findings from the Report
    Valuation & Growth Trajectory: The global Carbon Capture, Utilization, and Storage Market is projected to exceed USD 25.3 Billion by 2033, registering a compound annual growth rate (CAGR) of 23.8% from the base year.

    Dominant Segment: The Capture service segment commands the largest market share, serving as the essential upstream entry point for all downstream utilization and permanent geologic storage workflows.

    High-Growth Industrial End-Use: The Chemicals & Petrochemicals sector stands out as a leading end-use vertical, propelled by inherent high-concentration CO2 byproduct streams and direct integration into existing petrochemical gas-separation infrastructure.

    Regional Powerhouse: North America retains the leading regional market share, heavily supported by robust federal tax credits (such as the expanded 45Q tax incentives) and well-established pipeline networks.

    Emerging Growth Epicenter: Europe is recognized as the fastest-growing regional market, catalyzed by the EU Green Deal, cross-border infrastructure projects (like Northern Lights), and rigorous carbon pricing enforcement.

    Technology Adoption Shifts: Membrane and advanced solvent-based absorption technologies are gaining rapid commercial preference over legacy systems due to lower operational footprints and superior energy efficiency.

    Investment Relevance: Venture capital and institutional investments in CCUS infrastructure projects have surged past multi-billion-dollar thresholds, attracting major energy majors and sovereign wealth funds.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/carbon-capture-utilization-storage-market/2817
    Market Drivers and Restraints
    Drivers
    Stringent Environmental Regulations and Carbon Pricing: Global implementation of rigorous carbon taxes, net-zero mandates, and emission caps compel corporations to adopt CCUS to evade heavy financial penalties.

    Lucrative Government Subsidies and Tax Credits: Generous fiscal frameworks—most notably the U.S. 45Q tax credit and European green industrial funding—significantly improve project internal rates of return (IRR).

    Corporate Net-Zero Commitments and ESG Pressures: Institutional investors and consumer markets increasingly demand verified Scope 1 and Scope 2 emission reductions, compelling heavy industries to scale up carbon capture adoption.

    Restraints
    Prohibitive Capital Expenditure (CapEx): High upfront costs associated with engineering, designing, and constructing industrial-scale capture facilities and dedicated pipeline grids can deter mid-sized market participants.

    Complex Regulatory and Permitting Bottlenecks: Lengthy approval processes for underground CO2 storage sites and cross-border transport rights frequently cause project development delays.

    Technology, Regulation, and Sustainability Trends
    The evolution of the CCUS ecosystem is fundamentally anchored in next-generation technology and regulatory convergence. Innovations in modular, scalable solid sorbents and direct air capture (DAC) systems are driving down per-ton capture costs. Simultaneously, regulatory frameworks are evolving past simple emissions reporting into liability frameworks for permanent carbon storage, ensuring long-term environmental integrity. From an ESG standpoint, integrating CCUS into heavy industrial clusters is now viewed as the ultimate corporate safeguard against stranded assets, ensuring regulatory compliance while opening doors to green-certified product premiumization.

    Regional Insights
    North America: Dominates the global landscape, underpinned by proactive federal policies, abundant enhanced oil recovery (EOR) infrastructure, and deep-pocketed energy conglomerates accelerating commercial-scale hubs in the U.S. Gulf Coast and Western Canada.

    Europe: Serves as the fastest-growing market, led by aggressive decarbonization targets in the UK, Norway, the Netherlands, and Germany. The rapid development of North Sea offshore storage formations and cross-border transport agreements is establishing Europe as a global benchmark for industrial carbon management.

    Asia-Pacific: Exhibits substantial long-term potential, led by emerging industrial hubs in India, China, and Japan, where expanding manufacturing bases are gradually implementing early-stage CCUS feasibility pilots and national carbon-trading frameworks.

    Recent Industry Developments
    ExxonMobil (2025): Expanded its low-carbon solutions portfolio by securing major industrial carbon capture and offtake agreements along the U.S. Gulf Coast, scaling regional sequestration capacity by over 5 million metric tons per annum.

    Linde plc (2025): Partnered with key clean-energy developers to engineer modular carbon capture units for chemical processing plants, reducing customer retrofitting downtime by 30%.

    Mitsubishi Heavy Industries, Ltd. (2026): Deployed its proprietary advanced KS-21 solvent technology at a commercial waste-to-energy facility in Europe, achieving record-high CO2 recovery rates exceeding 98%.

    Shell Plc (2025): Advanced construction milestones on the Northern Lights offshore CO2 transport and storage project in Norway, successfully securing cross-border industrial storage contracts across multiple European manufacturing sectors.

    Aker Solutions (2026): Secured a major engineering contract for a large-scale cement plant decarbonization project, utilizing standardized carbon capture modules to slash lifecycle operational costs.

    Competitive Landscape
    The global CCUS market features a highly competitive ecosystem populated by major oil and gas multinationals, industrial gas giants, specialized clean-tech engineering firms, and oilfield service providers. Key market leaders—including Exxon Mobil Corporation, Fluor Corporation, Linde plc, Shell Plc, Mitsubishi Heavy Industries, Ltd., Schlumberger Limited, Aker Solutions, and Honeywell International—are actively expanding their market presence through strategic joint ventures, cross-border infrastructure partnerships, and aggressive intellectual property acquisitions. Competitors are heavily focusing on modular scalability and end-to-end service integration, offering turnkey solutions from point-source capture to secure underground storage.

    Analyst Commentary
    "The carbon capture, utilization, and storage market has decisively transitioned from experimental pilot testing to a multi-billion-dollar commercial asset class," said a Senior Research Analyst at Stellar Market Research. "As regulatory compliance costs rise and green premiums take hold, industrial players can no longer view decarbonization as a compliance cost center. The companies successfully navigating the next decade will be those that treat captured carbon not as waste, but as a strategic feedstock and a core pillar of sustainable industrial profitability."

    Future Outlook
    Through the forecast period, the CCUS market is poised for exponential expansion. Driven by declining technology costs, expanding shared pipeline networks, and tightening global emissions caps, adoption is expected to branch out from oil, gas, and chemicals into hard-to-abate sectors like maritime shipping, cement, and primary steelmaking. Public-private partnerships will remain instrumental in de-risking early-stage megaprojects, ultimately embedding CCUS as an indispensable structural pillar of the global low-carbon economy.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/carbon-capture-utilization-storage-market/2817
    About Stellar Market Research
    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Address
    Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041

    Email
    [email protected]

    Mobile
    +91 9607365656
    The Carbon Capture, Utilization, and Storage (CCUS) Market According to the latest research insights from Stellar Market Research, the global CCUS market is experiencing a paradigm shift, crossing critical valuation milestones as heavy industries accelerate decarbonization roadmaps to comply with stringent global emission frameworks. The global industrial landscape is undergoing a massive structural transformation, shifting from voluntary carbon-reduction pledges to mandatory, compliance-driven decarbonization. As international regulatory bodies enforce tighter carbon pricing mechanisms—such as the European Union’s Emissions Trading System (ETS) and Carbon Border Adjustment Mechanism (CBAM)—heavy-emitting sectors like power generation, cement, steel, and chemicals can no longer treat carbon management as an afterthought. Key Findings from the Report Valuation & Growth Trajectory: The global Carbon Capture, Utilization, and Storage Market is projected to exceed USD 25.3 Billion by 2033, registering a compound annual growth rate (CAGR) of 23.8% from the base year. Dominant Segment: The Capture service segment commands the largest market share, serving as the essential upstream entry point for all downstream utilization and permanent geologic storage workflows. High-Growth Industrial End-Use: The Chemicals & Petrochemicals sector stands out as a leading end-use vertical, propelled by inherent high-concentration CO2 byproduct streams and direct integration into existing petrochemical gas-separation infrastructure. Regional Powerhouse: North America retains the leading regional market share, heavily supported by robust federal tax credits (such as the expanded 45Q tax incentives) and well-established pipeline networks. Emerging Growth Epicenter: Europe is recognized as the fastest-growing regional market, catalyzed by the EU Green Deal, cross-border infrastructure projects (like Northern Lights), and rigorous carbon pricing enforcement. Technology Adoption Shifts: Membrane and advanced solvent-based absorption technologies are gaining rapid commercial preference over legacy systems due to lower operational footprints and superior energy efficiency. Investment Relevance: Venture capital and institutional investments in CCUS infrastructure projects have surged past multi-billion-dollar thresholds, attracting major energy majors and sovereign wealth funds. For further information, click the following link:https://www.stellarmr.com/report/req_sample/carbon-capture-utilization-storage-market/2817 Market Drivers and Restraints Drivers Stringent Environmental Regulations and Carbon Pricing: Global implementation of rigorous carbon taxes, net-zero mandates, and emission caps compel corporations to adopt CCUS to evade heavy financial penalties. Lucrative Government Subsidies and Tax Credits: Generous fiscal frameworks—most notably the U.S. 45Q tax credit and European green industrial funding—significantly improve project internal rates of return (IRR). Corporate Net-Zero Commitments and ESG Pressures: Institutional investors and consumer markets increasingly demand verified Scope 1 and Scope 2 emission reductions, compelling heavy industries to scale up carbon capture adoption. Restraints Prohibitive Capital Expenditure (CapEx): High upfront costs associated with engineering, designing, and constructing industrial-scale capture facilities and dedicated pipeline grids can deter mid-sized market participants. Complex Regulatory and Permitting Bottlenecks: Lengthy approval processes for underground CO2 storage sites and cross-border transport rights frequently cause project development delays. Technology, Regulation, and Sustainability Trends The evolution of the CCUS ecosystem is fundamentally anchored in next-generation technology and regulatory convergence. Innovations in modular, scalable solid sorbents and direct air capture (DAC) systems are driving down per-ton capture costs. Simultaneously, regulatory frameworks are evolving past simple emissions reporting into liability frameworks for permanent carbon storage, ensuring long-term environmental integrity. From an ESG standpoint, integrating CCUS into heavy industrial clusters is now viewed as the ultimate corporate safeguard against stranded assets, ensuring regulatory compliance while opening doors to green-certified product premiumization. Regional Insights North America: Dominates the global landscape, underpinned by proactive federal policies, abundant enhanced oil recovery (EOR) infrastructure, and deep-pocketed energy conglomerates accelerating commercial-scale hubs in the U.S. Gulf Coast and Western Canada. Europe: Serves as the fastest-growing market, led by aggressive decarbonization targets in the UK, Norway, the Netherlands, and Germany. The rapid development of North Sea offshore storage formations and cross-border transport agreements is establishing Europe as a global benchmark for industrial carbon management. Asia-Pacific: Exhibits substantial long-term potential, led by emerging industrial hubs in India, China, and Japan, where expanding manufacturing bases are gradually implementing early-stage CCUS feasibility pilots and national carbon-trading frameworks. Recent Industry Developments ExxonMobil (2025): Expanded its low-carbon solutions portfolio by securing major industrial carbon capture and offtake agreements along the U.S. Gulf Coast, scaling regional sequestration capacity by over 5 million metric tons per annum. Linde plc (2025): Partnered with key clean-energy developers to engineer modular carbon capture units for chemical processing plants, reducing customer retrofitting downtime by 30%. Mitsubishi Heavy Industries, Ltd. (2026): Deployed its proprietary advanced KS-21 solvent technology at a commercial waste-to-energy facility in Europe, achieving record-high CO2 recovery rates exceeding 98%. Shell Plc (2025): Advanced construction milestones on the Northern Lights offshore CO2 transport and storage project in Norway, successfully securing cross-border industrial storage contracts across multiple European manufacturing sectors. Aker Solutions (2026): Secured a major engineering contract for a large-scale cement plant decarbonization project, utilizing standardized carbon capture modules to slash lifecycle operational costs. Competitive Landscape The global CCUS market features a highly competitive ecosystem populated by major oil and gas multinationals, industrial gas giants, specialized clean-tech engineering firms, and oilfield service providers. Key market leaders—including Exxon Mobil Corporation, Fluor Corporation, Linde plc, Shell Plc, Mitsubishi Heavy Industries, Ltd., Schlumberger Limited, Aker Solutions, and Honeywell International—are actively expanding their market presence through strategic joint ventures, cross-border infrastructure partnerships, and aggressive intellectual property acquisitions. Competitors are heavily focusing on modular scalability and end-to-end service integration, offering turnkey solutions from point-source capture to secure underground storage. Analyst Commentary "The carbon capture, utilization, and storage market has decisively transitioned from experimental pilot testing to a multi-billion-dollar commercial asset class," said a Senior Research Analyst at Stellar Market Research. "As regulatory compliance costs rise and green premiums take hold, industrial players can no longer view decarbonization as a compliance cost center. The companies successfully navigating the next decade will be those that treat captured carbon not as waste, but as a strategic feedstock and a core pillar of sustainable industrial profitability." Future Outlook Through the forecast period, the CCUS market is poised for exponential expansion. Driven by declining technology costs, expanding shared pipeline networks, and tightening global emissions caps, adoption is expected to branch out from oil, gas, and chemicals into hard-to-abate sectors like maritime shipping, cement, and primary steelmaking. Public-private partnerships will remain instrumental in de-risking early-stage megaprojects, ultimately embedding CCUS as an indispensable structural pillar of the global low-carbon economy. For further information, click the following link:https://www.stellarmr.com/report/req_sample/carbon-capture-utilization-storage-market/2817 About Stellar Market Research Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Address Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041 Email [email protected] Mobile +91 9607365656
    0 Comments ·0 Shares ·54 Views

  • Motor Control Center Market Opportunities Grow Across Manufacturing Industries

    Market Estimation & Definition

    The global Motor Control Center (MCC) Market is gaining momentum as industries invest in automation, electrical safety, and efficient motor management. According to Stellar Market Research, the market was valued at USD 6.55 billion in 2025 and is projected to reach USD 9.86 billion by 2032, registering a compound annual growth rate (CAGR) of 6.02% during 2026–2032.

    A motor control center is an assembly of enclosed electrical sections connected through a common power bus. It houses equipment used to control, protect, and monitor electric motors, including circuit breakers, relays, variable speed drives, and programmable controllers. MCCs are widely used in industrial plants, commercial facilities, oil and gas operations, mining, and manufacturing, where reliable motor performance is essential for continuous operations.

    Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/motor-control-center-market/2606

    Market Growth Drivers & Opportunity

    Industrial automation is a major driver of the Motor Control Center Market. Manufacturing facilities increasingly require integrated systems that improve productivity, reduce downtime, and protect electrical equipment. MCCs combine motor control and protection functions within a centralized arrangement, helping operators manage complex industrial processes more efficiently.

    Demand from the oil and gas industry also supports market expansion. Refineries and processing facilities use electric motors to operate pumps, compressors, drilling equipment, and production systems. Mining, food and beverage, automotive, and metal-processing industries similarly depend on reliable motor control solutions.

    The growing adoption of intelligent motor control centers creates additional opportunities. These systems offer advanced diagnostics, remote monitoring, improved communication, and more precise control. However, fluctuations in raw material prices and competition from alternative technologies can affect purchasing decisions. Manufacturers that provide reliable equipment, advanced protection features, and cost-effective solutions are well positioned to address evolving industrial requirements.

    What Lies Ahead: Emerging Trends Shaping the Future

    Intelligent motor control centers are expected to gain importance as industries move toward connected manufacturing environments. Microprocessor-based controls, communication networks, and diagnostic tools enable operators to identify potential equipment problems earlier and reduce unplanned downtime.

    Energy efficiency is another important trend. Variable speed drives help regulate motor speeds according to operational requirements, potentially reducing unnecessary energy consumption. As industries seek to improve operating efficiency and meet sustainability objectives, demand for integrated motor management solutions is expected to increase.

    Industrial infrastructure modernization also presents opportunities. Investments in manufacturing facilities, utilities, power generation, and process industries can support demand for both new installations and replacement systems. Modular designs and enhanced monitoring capabilities may further improve installation flexibility and maintenance planning.

    Get More Report Details: https://www.stellarmr.com/report/motor-control-center-market/2606

    Segmentation Analysis

    According to Stellar Market Research, the Motor Control Center Market is segmented by standard, component, type, end-user, and region.

    By Standard: NEMA, IEC.
    By Component: Busbars, Circuit Breakers and Fuses, Overload Relays, Variable Speed Drives, Soft Starters.
    By Type: Conventional Motor Control Center, Intelligent Motor Control Center.
    By End-User: Oil & Gas, Iron & Steel, Minerals & Mining, Food & Beverage, Automotive, Commercial, Others.
    By Region: North America, Europe, Asia Pacific, South America, Middle East & Africa.
    Intelligent motor control centers are gaining traction because of their advanced safety, diagnostic, and communication capabilities. Circuit breakers and fuses are important components for electrical protection, while variable speed drives support motor regulation and efficiency. Oil and gas represents the leading end-user segment due to its extensive use of motor-driven equipment. Asia Pacific held the largest regional share in 2025, supported by industrial development and investment in infrastructure.

    Country-Level Analysis: USA and Germany

    United States: The United States is an important market for motor control centers, supported by industrial automation, oil and gas operations, and demand for modern electrical infrastructure. General Electric Company, Rockwell Automation, Tesco Controls, and Powell Industries are among the US-based companies listed in the report. Investment in industrial facilities and equipment modernization provides opportunities for advanced motor control technologies.

    Germany: Germany plays an important role in the European market due to its established manufacturing and industrial engineering sectors. Siemens AG and Rittal are among the Germany-based companies identified in the report. Demand for automation, electrical protection, and efficient motor management supports the adoption of motor control solutions. The report includes Germany in its regional coverage but does not provide separate headline market valuations for either country.

    Competitive Analysis

    The Motor Control Center Market features global electrical equipment manufacturers and specialized industrial automation providers. Key players identified by Stellar Market Research include ABB, Siemens AG, General Electric Company, Schneider Electric SE, Rockwell Automation, Mitsubishi Electric Corporation, Eaton, Fuji Electric, WEG, Larsen & Toubro, Rittal, Ingeteam, LSIS, and Powell Industries.

    Competition is shaped by equipment reliability, electrical safety, energy efficiency, digital monitoring, and compatibility with industrial automation systems. Companies that combine advanced control capabilities with dependable technical support and flexible product configurations may strengthen their competitive position.

    Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/motor-control-center-market/2606

    Press Release Conclusion

    The Motor Control Center Market is positioned for steady growth as industries prioritize automation, energy efficiency, and reliable electrical operations. With the market projected to reach USD 9.86 billion by 2032, opportunities are emerging across oil and gas, manufacturing, mining, automotive, and commercial applications.

    Although raw material price fluctuations and evolving technologies present challenges, intelligent motor control centers, advanced diagnostics, and improved motor management are expected to support future demand. Companies investing in reliable, efficient, and connected control solutions will be well positioned to benefit from continuing industrial modernization.

    About Stellar Market Research:

    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Contact Stellar Market Research:

    3rd Floor, Navale IT Park, Phase 2

    Pune Banglore Highway, Narhe,

    Pune, Maharashtra 411041, India

    [email protected]

    +91 20 6630 3320 | +91 9607365656
    Motor Control Center Market Opportunities Grow Across Manufacturing Industries Market Estimation & Definition The global Motor Control Center (MCC) Market is gaining momentum as industries invest in automation, electrical safety, and efficient motor management. According to Stellar Market Research, the market was valued at USD 6.55 billion in 2025 and is projected to reach USD 9.86 billion by 2032, registering a compound annual growth rate (CAGR) of 6.02% during 2026–2032. A motor control center is an assembly of enclosed electrical sections connected through a common power bus. It houses equipment used to control, protect, and monitor electric motors, including circuit breakers, relays, variable speed drives, and programmable controllers. MCCs are widely used in industrial plants, commercial facilities, oil and gas operations, mining, and manufacturing, where reliable motor performance is essential for continuous operations. Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/motor-control-center-market/2606 Market Growth Drivers & Opportunity Industrial automation is a major driver of the Motor Control Center Market. Manufacturing facilities increasingly require integrated systems that improve productivity, reduce downtime, and protect electrical equipment. MCCs combine motor control and protection functions within a centralized arrangement, helping operators manage complex industrial processes more efficiently. Demand from the oil and gas industry also supports market expansion. Refineries and processing facilities use electric motors to operate pumps, compressors, drilling equipment, and production systems. Mining, food and beverage, automotive, and metal-processing industries similarly depend on reliable motor control solutions. The growing adoption of intelligent motor control centers creates additional opportunities. These systems offer advanced diagnostics, remote monitoring, improved communication, and more precise control. However, fluctuations in raw material prices and competition from alternative technologies can affect purchasing decisions. Manufacturers that provide reliable equipment, advanced protection features, and cost-effective solutions are well positioned to address evolving industrial requirements. What Lies Ahead: Emerging Trends Shaping the Future Intelligent motor control centers are expected to gain importance as industries move toward connected manufacturing environments. Microprocessor-based controls, communication networks, and diagnostic tools enable operators to identify potential equipment problems earlier and reduce unplanned downtime. Energy efficiency is another important trend. Variable speed drives help regulate motor speeds according to operational requirements, potentially reducing unnecessary energy consumption. As industries seek to improve operating efficiency and meet sustainability objectives, demand for integrated motor management solutions is expected to increase. Industrial infrastructure modernization also presents opportunities. Investments in manufacturing facilities, utilities, power generation, and process industries can support demand for both new installations and replacement systems. Modular designs and enhanced monitoring capabilities may further improve installation flexibility and maintenance planning. Get More Report Details: https://www.stellarmr.com/report/motor-control-center-market/2606 Segmentation Analysis According to Stellar Market Research, the Motor Control Center Market is segmented by standard, component, type, end-user, and region. By Standard: NEMA, IEC. By Component: Busbars, Circuit Breakers and Fuses, Overload Relays, Variable Speed Drives, Soft Starters. By Type: Conventional Motor Control Center, Intelligent Motor Control Center. By End-User: Oil & Gas, Iron & Steel, Minerals & Mining, Food & Beverage, Automotive, Commercial, Others. By Region: North America, Europe, Asia Pacific, South America, Middle East & Africa. Intelligent motor control centers are gaining traction because of their advanced safety, diagnostic, and communication capabilities. Circuit breakers and fuses are important components for electrical protection, while variable speed drives support motor regulation and efficiency. Oil and gas represents the leading end-user segment due to its extensive use of motor-driven equipment. Asia Pacific held the largest regional share in 2025, supported by industrial development and investment in infrastructure. Country-Level Analysis: USA and Germany United States: The United States is an important market for motor control centers, supported by industrial automation, oil and gas operations, and demand for modern electrical infrastructure. General Electric Company, Rockwell Automation, Tesco Controls, and Powell Industries are among the US-based companies listed in the report. Investment in industrial facilities and equipment modernization provides opportunities for advanced motor control technologies. Germany: Germany plays an important role in the European market due to its established manufacturing and industrial engineering sectors. Siemens AG and Rittal are among the Germany-based companies identified in the report. Demand for automation, electrical protection, and efficient motor management supports the adoption of motor control solutions. The report includes Germany in its regional coverage but does not provide separate headline market valuations for either country. Competitive Analysis The Motor Control Center Market features global electrical equipment manufacturers and specialized industrial automation providers. Key players identified by Stellar Market Research include ABB, Siemens AG, General Electric Company, Schneider Electric SE, Rockwell Automation, Mitsubishi Electric Corporation, Eaton, Fuji Electric, WEG, Larsen & Toubro, Rittal, Ingeteam, LSIS, and Powell Industries. Competition is shaped by equipment reliability, electrical safety, energy efficiency, digital monitoring, and compatibility with industrial automation systems. Companies that combine advanced control capabilities with dependable technical support and flexible product configurations may strengthen their competitive position. Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/motor-control-center-market/2606 Press Release Conclusion The Motor Control Center Market is positioned for steady growth as industries prioritize automation, energy efficiency, and reliable electrical operations. With the market projected to reach USD 9.86 billion by 2032, opportunities are emerging across oil and gas, manufacturing, mining, automotive, and commercial applications. Although raw material price fluctuations and evolving technologies present challenges, intelligent motor control centers, advanced diagnostics, and improved motor management are expected to support future demand. Companies investing in reliable, efficient, and connected control solutions will be well positioned to benefit from continuing industrial modernization. About Stellar Market Research: Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Contact Stellar Market Research: 3rd Floor, Navale IT Park, Phase 2 Pune Banglore Highway, Narhe, Pune, Maharashtra 411041, India [email protected] +91 20 6630 3320 | +91 9607365656
    0 Comments ·0 Shares ·65 Views
  • The Industrial Boiler Market, projecting explosive valuation milestones through the next decade. According to the report, the market was valued at USD 17.12 billion in 2025 and is poised to scale up to USD 24.01 billion by 2032, expanding at a compound annual growth rate (CAGR) of 4.07%. This strategic growth trajectory underscores the critical role of high-efficiency thermal energy systems in enabling global industrial decarbonization, chemical processing, and smart manufacturing transformations.

    The global industrial landscape is undergoing a profound structural pivot. Driven by aggressive net-zero commitments and escalating carbon taxation, heavy industries are moving away from legacy, carbon-heavy coal-fired infrastructure toward advanced hybrid, hydrogen-ready, and ultra-efficient natural gas boilers. Simultaneously, the deployment of IoT-enabled automated combustion controls is redefining plant operations, turning traditional boilers from mere energy units into intelligent data nodes that optimize fuel efficiency and minimize downtime. This dual transition toward sustainability and digitization is opening lucrative avenues for equipment retrofitting, greenfield manufacturing expansions, and integrated smart-boiler services worldwide.

    Key Findings from the Report
    Valuation Milestone: The industrial boiler market reached a baseline valuation of USD 17.12 billion in 2025.

    Growth Trajectory: The market is projected to expand steadily at a 4.07% CAGR throughout the forecast period from 2026 to 2032.

    Dominant Segment (Type/Capacity): Water-tube and package boilers command the largest revenue shares, backed by high thermal efficiency and rapid steam generation capabilities required in heavy continuous-duty applications.

    Leading Application: The chemicals and petrochemicals sector remains the dominant end-user vertical, accounting for over one-third of total thermal energy equipment demand.

    Fuel Preferences: Natural gas continues to capture primary adoption share due to tightening emissions legislation, though biomass and hydrogen-compatible systems are registering the fastest incremental traction.

    Regional Dominance: The Asia-Pacific region leads global consumption, powered by expansive chemical hubs, textile manufacturing, and heavy industrialization in China and India.

    Investment Relevance: Capital expenditure is heavily skewed toward energy-efficient retrofits, IoT sensor integration, and low-emission boiler replacements.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/Industrial-Boiler-Market/339
    Market Drivers and Restraints
    Drivers
    Stringent Environmental Regulations: Global mandates capping greenhouse gas emissions force legacy plants to upgrade or replace high-polluting subcritical boilers with advanced low-NOx and low-CO2 alternatives.

    Industrial Expansion in Emerging Economies: Rapid manufacturing build-outs across Asia-Pacific and Latin America amplify the baseline demand for stable, high-capacity industrial steam generation.

    Rise of Energy-Efficient & Smart Technologies: Integration of IoT, predictive maintenance algorithms, and real-time fuel-to-steam efficiency monitoring drives widespread commercial adoption.

    Restraints
    High Initial Capital Outlay: The substantial upfront capital expenditure required for premium, low-emission boilers and auxiliary retrofitting can deter small and medium-scale enterprises (SMEs).

    Supply Chain Bottlenecks for Specialized Materials: Constraints in acquiring high-grade heat-resistant alloys and specialized automation components can cause project deployment delays.

    Technology, Regulation, and Sustainability Trends
    The industrial boiler ecosystem is experiencing an unprecedented convergence of digital technology and environmental compliance. Modern units are increasingly equipped with digital twins and IoT-enabled telemetry, allowing operators to monitor thermal efficiency, predict tube failures, and automate air-fuel ratios in real time. On the regulatory front, compliance frameworks such as the European Union’s Industrial Emissions Directive (IED) and stringent regional pollution control standards are penalizing high-emission operations, accelerating the phase-out of traditional coal units. Consequently, sustainability has shifted from a corporate PR objective to a core engineering requirement, with manufacturers prioritizing hydrogen-blended combustion capabilities and biomass co-firing.

    Regional Insights
    Asia-Pacific (Leading Region): APAC maintains its crown as the dominant and fastest-growing regional market. Accelerated by massive chemical corridor expansions in India, China, and Southeast Asia, local industries are aggressively modernizing legacy thermal infrastructure to match surging domestic manufacturing output.

    North America: Driven by rigorous EPA standards and widespread availability of affordable shale gas, North American industries are prioritizing high-efficiency package boilers and smart-grid integrated thermal systems.

    Europe: Europe spearheads the sustainability charge, focusing heavily on hydrogen-ready boilers, waste-heat recovery systems, and strict compliance with ultra-low carbon frameworks.

    Recent Industry Developments
    Thermax Ltd. (2025): Launched a new line of hybrid electric-steam industrial boilers designed to help chemical plants utilize surplus renewable energy, cutting direct fossil fuel consumption by up to 30%.

    Babcock & Wilcox (2025): Secured a major multi-million dollar contract to supply advanced, low-emission biomass-fired boilers for a municipal-industrial energy project in Europe, expanding its green-energy footprint.

    Siemens AG (2026): Partnered with leading boiler manufacturers to integrate industrial IoT edge controllers, delivering real-time thermodynamic efficiency optimization across heavy manufacturing lines.

    Cleaver-Brooks (2025): Expanded its North American manufacturing capacity with a specialized production line dedicated to ultra-low NOx packaged firetube boilers to meet strict regional clean air standards.

    Mitsubishi Heavy Industries (2026): Achieved successful commercial validation of its 100% hydrogen-ready combustion burner technology for industrial utility boilers, marking a critical milestone for net-zero heavy industry.

    Competitive Landscape
    The global industrial boiler market features a consolidated yet fiercely competitive landscape characterized by major engineering conglomerates and specialized thermal tech providers. Key players include Thermax Ltd., Siemens AG, Bharat Heavy Electricals Ltd. (BHEL), Mitsubishi Heavy Industries, Cleaver-Brooks, and Babcock & Wilcox. Leading corporations are focusing heavily on strategic mergers, acquisitions, and joint ventures to expand their geographic footprint and enhance their green-energy portfolios. Product differentiation is increasingly anchored around digital control integration, aftermarket servicing efficiency, and hydrogen fuel adaptability.

    Analyst Commentary
    "The industrial boiler market is no longer driven purely by basic steam generation capacity; it is undergoing a fundamental technological realignment centered around decarbonization and intelligence," said a Senior Research Analyst at Stellar Market Research. "As regulatory frameworks tighten globally, plant operators are moving past short-term cost-cutting. They are heavily investing in smart, fuel-flexible, and hydrogen-ready systems that future-proof their operations against both carbon taxation and volatile fuel pricing."

    Future Outlook
    Through the forecast horizon, the industrial boiler market will experience accelerated convergence between traditional heavy manufacturing and digital automation. Demand will increasingly pivot toward modular, scalable, and multi-fuel-capable systems that can seamlessly transition between natural gas, biomass, and green hydrogen. With emerging economies continuing to build out robust industrial infrastructure and developed nations prioritizing deep decarbonization retrofits, market participants that successfully embed advanced IoT diagnostics and carbon-neutral technologies into their core portfolios will capture dominant long-term market share.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/Industrial-Boiler-Market/339
    About Stellar Market Research
    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Address
    Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041

    Email
    [email protected]

    Mobile
    +91 9607365656
    The Industrial Boiler Market, projecting explosive valuation milestones through the next decade. According to the report, the market was valued at USD 17.12 billion in 2025 and is poised to scale up to USD 24.01 billion by 2032, expanding at a compound annual growth rate (CAGR) of 4.07%. This strategic growth trajectory underscores the critical role of high-efficiency thermal energy systems in enabling global industrial decarbonization, chemical processing, and smart manufacturing transformations. The global industrial landscape is undergoing a profound structural pivot. Driven by aggressive net-zero commitments and escalating carbon taxation, heavy industries are moving away from legacy, carbon-heavy coal-fired infrastructure toward advanced hybrid, hydrogen-ready, and ultra-efficient natural gas boilers. Simultaneously, the deployment of IoT-enabled automated combustion controls is redefining plant operations, turning traditional boilers from mere energy units into intelligent data nodes that optimize fuel efficiency and minimize downtime. This dual transition toward sustainability and digitization is opening lucrative avenues for equipment retrofitting, greenfield manufacturing expansions, and integrated smart-boiler services worldwide. Key Findings from the Report Valuation Milestone: The industrial boiler market reached a baseline valuation of USD 17.12 billion in 2025. Growth Trajectory: The market is projected to expand steadily at a 4.07% CAGR throughout the forecast period from 2026 to 2032. Dominant Segment (Type/Capacity): Water-tube and package boilers command the largest revenue shares, backed by high thermal efficiency and rapid steam generation capabilities required in heavy continuous-duty applications. Leading Application: The chemicals and petrochemicals sector remains the dominant end-user vertical, accounting for over one-third of total thermal energy equipment demand. Fuel Preferences: Natural gas continues to capture primary adoption share due to tightening emissions legislation, though biomass and hydrogen-compatible systems are registering the fastest incremental traction. Regional Dominance: The Asia-Pacific region leads global consumption, powered by expansive chemical hubs, textile manufacturing, and heavy industrialization in China and India. Investment Relevance: Capital expenditure is heavily skewed toward energy-efficient retrofits, IoT sensor integration, and low-emission boiler replacements. For further information, click the following link:https://www.stellarmr.com/report/req_sample/Industrial-Boiler-Market/339 Market Drivers and Restraints Drivers Stringent Environmental Regulations: Global mandates capping greenhouse gas emissions force legacy plants to upgrade or replace high-polluting subcritical boilers with advanced low-NOx and low-CO2 alternatives. Industrial Expansion in Emerging Economies: Rapid manufacturing build-outs across Asia-Pacific and Latin America amplify the baseline demand for stable, high-capacity industrial steam generation. Rise of Energy-Efficient & Smart Technologies: Integration of IoT, predictive maintenance algorithms, and real-time fuel-to-steam efficiency monitoring drives widespread commercial adoption. Restraints High Initial Capital Outlay: The substantial upfront capital expenditure required for premium, low-emission boilers and auxiliary retrofitting can deter small and medium-scale enterprises (SMEs). Supply Chain Bottlenecks for Specialized Materials: Constraints in acquiring high-grade heat-resistant alloys and specialized automation components can cause project deployment delays. Technology, Regulation, and Sustainability Trends The industrial boiler ecosystem is experiencing an unprecedented convergence of digital technology and environmental compliance. Modern units are increasingly equipped with digital twins and IoT-enabled telemetry, allowing operators to monitor thermal efficiency, predict tube failures, and automate air-fuel ratios in real time. On the regulatory front, compliance frameworks such as the European Union’s Industrial Emissions Directive (IED) and stringent regional pollution control standards are penalizing high-emission operations, accelerating the phase-out of traditional coal units. Consequently, sustainability has shifted from a corporate PR objective to a core engineering requirement, with manufacturers prioritizing hydrogen-blended combustion capabilities and biomass co-firing. Regional Insights Asia-Pacific (Leading Region): APAC maintains its crown as the dominant and fastest-growing regional market. Accelerated by massive chemical corridor expansions in India, China, and Southeast Asia, local industries are aggressively modernizing legacy thermal infrastructure to match surging domestic manufacturing output. North America: Driven by rigorous EPA standards and widespread availability of affordable shale gas, North American industries are prioritizing high-efficiency package boilers and smart-grid integrated thermal systems. Europe: Europe spearheads the sustainability charge, focusing heavily on hydrogen-ready boilers, waste-heat recovery systems, and strict compliance with ultra-low carbon frameworks. Recent Industry Developments Thermax Ltd. (2025): Launched a new line of hybrid electric-steam industrial boilers designed to help chemical plants utilize surplus renewable energy, cutting direct fossil fuel consumption by up to 30%. Babcock & Wilcox (2025): Secured a major multi-million dollar contract to supply advanced, low-emission biomass-fired boilers for a municipal-industrial energy project in Europe, expanding its green-energy footprint. Siemens AG (2026): Partnered with leading boiler manufacturers to integrate industrial IoT edge controllers, delivering real-time thermodynamic efficiency optimization across heavy manufacturing lines. Cleaver-Brooks (2025): Expanded its North American manufacturing capacity with a specialized production line dedicated to ultra-low NOx packaged firetube boilers to meet strict regional clean air standards. Mitsubishi Heavy Industries (2026): Achieved successful commercial validation of its 100% hydrogen-ready combustion burner technology for industrial utility boilers, marking a critical milestone for net-zero heavy industry. Competitive Landscape The global industrial boiler market features a consolidated yet fiercely competitive landscape characterized by major engineering conglomerates and specialized thermal tech providers. Key players include Thermax Ltd., Siemens AG, Bharat Heavy Electricals Ltd. (BHEL), Mitsubishi Heavy Industries, Cleaver-Brooks, and Babcock & Wilcox. Leading corporations are focusing heavily on strategic mergers, acquisitions, and joint ventures to expand their geographic footprint and enhance their green-energy portfolios. Product differentiation is increasingly anchored around digital control integration, aftermarket servicing efficiency, and hydrogen fuel adaptability. Analyst Commentary "The industrial boiler market is no longer driven purely by basic steam generation capacity; it is undergoing a fundamental technological realignment centered around decarbonization and intelligence," said a Senior Research Analyst at Stellar Market Research. "As regulatory frameworks tighten globally, plant operators are moving past short-term cost-cutting. They are heavily investing in smart, fuel-flexible, and hydrogen-ready systems that future-proof their operations against both carbon taxation and volatile fuel pricing." Future Outlook Through the forecast horizon, the industrial boiler market will experience accelerated convergence between traditional heavy manufacturing and digital automation. Demand will increasingly pivot toward modular, scalable, and multi-fuel-capable systems that can seamlessly transition between natural gas, biomass, and green hydrogen. With emerging economies continuing to build out robust industrial infrastructure and developed nations prioritizing deep decarbonization retrofits, market participants that successfully embed advanced IoT diagnostics and carbon-neutral technologies into their core portfolios will capture dominant long-term market share. For further information, click the following link:https://www.stellarmr.com/report/req_sample/Industrial-Boiler-Market/339 About Stellar Market Research Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Address Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041 Email [email protected] Mobile +91 9607365656
    0 Comments ·0 Shares ·326 Views
  • Asia Pacific UPS Battery Market Trends Highlight Advanced Battery Technologies

    Market Estimation & Definition

    The Asia Pacific UPS Battery Market is expected to expand as businesses invest in digital infrastructure, data centers, telecommunications, and reliable power backup systems. According to Stellar Market Research, the market was valued at USD 412.18 million in 2025 and is projected to reach USD 917.63 million by 2035 , registering a compound annual growth rate (CAGR) of 9.3% during 2026–2035 .

    An uninterruptible power supply (UPS) battery provides backup electricity when the main power source fails or experiences a disruption. These batteries protect critical equipment, including servers, networking devices, industrial machinery, communication systems, and financial infrastructure. By maintaining power continuity, UPS batteries help prevent data loss, equipment damage, and costly operational interruptions. Their importance is increasing as businesses across Asia Pacific become more dependent on digital services and connected infrastructure.

    Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Asia-Pacific-UPS-Battery-Market/136

    Market Growth Drivers & Opportunity

    The rapid expansion of data centers is a major driver of the Asia Pacific UPS Battery Market. Cloud computing, online transactions, artificial intelligence infrastructure, and enterprise digitalization are increasing the need for uninterrupted power. Data centers require dependable backup systems to protect servers and maintain service availability during electrical disturbances.

    Telecommunications development is another important growth factor. The expansion of 5G networks and edge computing infrastructure is creating demand for reliable backup power at communication facilities. Banking, financial services, and insurance companies also depend on UPS systems to maintain ATMs, transaction platforms, and data-processing operations.

    Government initiatives supporting smart cities, digital public services, and modern electricity infrastructure are creating additional opportunities. However, high initial investment, battery replacement costs, maintenance requirements, and differences in infrastructure development across the region can influence adoption. Suppliers that offer reliable products, efficient battery management, and competitive lifecycle costs may be better positioned to meet demand.

    What Lies Ahead: Emerging Trends Shaping the Future

    Lithium-ion technology is expected to play an increasingly important role in UPS battery applications. Compared with traditional lead-acid batteries, lithium-ion batteries can offer lower weight, a compact footprint, faster charging, and longer service life under suitable operating conditions. These characteristics make them attractive for data centers and facilities where space efficiency and reliability are priorities.

    Modular UPS systems are also gaining attention as businesses seek scalable power protection. Modular configurations can allow facilities to expand capacity as requirements increase, helping operators manage investment and operational needs.

    The development of smart grids, cloud services, and connected industrial systems will further support demand for advanced backup solutions. Battery monitoring and management technologies can help operators track battery health, identify potential failures, and plan maintenance more effectively. Manufacturers will need to balance performance, safety, affordability, and environmental considerations as battery deployment increases.

    Get More Report Details: https://www.stellarmr.com/report/Asia-Pacific-UPS-Battery-Market/136

    Segmentation Analysis

    According to Stellar Market Research, the Asia Pacific UPS Battery Market is segmented by topology, product type, and application.

    By Topology: Online, Standby, Line Interactive.
    By Product Type: Lead-acid, Lithium-Ion, Nickel Cadmium, Others.
    By Application: Residential, Commercial, Data Center, Industrial.
    Online UPS systems provide continuous power conditioning and are suitable for equipment requiring high levels of protection. Standby and line-interactive systems offer alternatives for applications with different power protection requirements.

    Within product types, lithium-ion batteries are projected to register strong growth because of their compact design, charging performance, and potential service-life advantages. By application, data centers represent a significant opportunity as cloud computing and digital services increase demand for dependable power infrastructure. The report identifies China as the leading country in the regional market, supported by its substantial digital infrastructure and investment in technology.

    Country-Level Analysis: USA and Germany

    United States: The United States is outside the geographic scope of this Asia Pacific report, but US-based companies participate in the broader UPS battery industry. Eaton Corporation and Vertiv Group Corporation are among the key players identified by Stellar Market Research. Their power management and critical-infrastructure solutions illustrate the importance of reliable backup power for data centers and industrial facilities.

    Germany: Germany is also outside the report's geographic scope. The study does not provide a separate German market valuation or forecast. For European industry context, the report identifies international suppliers operating in the wider power protection ecosystem, including Schneider Electric, although the company is headquartered in France rather than Germany. The market analysis therefore remains focused on Asia Pacific, where China, India, Japan, South Korea, Australia, ASEAN, and the rest of the region form the report's country coverage.

    Competitive Analysis

    The Asia Pacific UPS Battery Market features established battery manufacturers, electrical equipment suppliers, and power management companies. Key players identified by Stellar Market Research include CSB Battery Co., Ltd., East Penn Manufacturing Company, Eaton Corporation plc, Exide Industries Limited, FIAMM Energy Technology SpA, GS Yuasa International Ltd., Leoch International Technology Limited Inc., Schneider Electric SE, and Vertiv Group Corporation .

    Competition is shaped by battery performance, reliability, service life, safety, pricing, and compatibility with UPS systems. Companies investing in lithium-ion technology, intelligent monitoring, and scalable backup solutions may strengthen their position as data center and industrial power requirements grow.

    Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Asia-Pacific-UPS-Battery-Market/136

    Press Release Conclusion

    The Asia Pacific UPS Battery Market is projected to reach USD 917.63 million by 2034 as digital infrastructure, data center development, telecommunications expansion, and industrial automation increase demand for dependable backup power.

    Although cost and maintenance considerations remain important, lithium-ion batteries, modular UPS systems, and advanced monitoring technologies are creating new opportunities. Manufacturers that combine reliability, efficiency, and competitive lifecycle costs will be well positioned to support the region's growing need for uninterrupted electricity.

    About Stellar Market Research:

    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Contact Stellar Market Research:

    3rd Floor, Navale IT Park, Phase 2

    Pune Banglore Highway, Narhe,

    Pune, Maharashtra 411041, India

    [email protected]

    +91 20 6630 3320 | +91 9607365656
    Asia Pacific UPS Battery Market Trends Highlight Advanced Battery Technologies Market Estimation & Definition The Asia Pacific UPS Battery Market is expected to expand as businesses invest in digital infrastructure, data centers, telecommunications, and reliable power backup systems. According to Stellar Market Research, the market was valued at USD 412.18 million in 2025 and is projected to reach USD 917.63 million by 2035 , registering a compound annual growth rate (CAGR) of 9.3% during 2026–2035 . An uninterruptible power supply (UPS) battery provides backup electricity when the main power source fails or experiences a disruption. These batteries protect critical equipment, including servers, networking devices, industrial machinery, communication systems, and financial infrastructure. By maintaining power continuity, UPS batteries help prevent data loss, equipment damage, and costly operational interruptions. Their importance is increasing as businesses across Asia Pacific become more dependent on digital services and connected infrastructure. Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Asia-Pacific-UPS-Battery-Market/136 Market Growth Drivers & Opportunity The rapid expansion of data centers is a major driver of the Asia Pacific UPS Battery Market. Cloud computing, online transactions, artificial intelligence infrastructure, and enterprise digitalization are increasing the need for uninterrupted power. Data centers require dependable backup systems to protect servers and maintain service availability during electrical disturbances. Telecommunications development is another important growth factor. The expansion of 5G networks and edge computing infrastructure is creating demand for reliable backup power at communication facilities. Banking, financial services, and insurance companies also depend on UPS systems to maintain ATMs, transaction platforms, and data-processing operations. Government initiatives supporting smart cities, digital public services, and modern electricity infrastructure are creating additional opportunities. However, high initial investment, battery replacement costs, maintenance requirements, and differences in infrastructure development across the region can influence adoption. Suppliers that offer reliable products, efficient battery management, and competitive lifecycle costs may be better positioned to meet demand. What Lies Ahead: Emerging Trends Shaping the Future Lithium-ion technology is expected to play an increasingly important role in UPS battery applications. Compared with traditional lead-acid batteries, lithium-ion batteries can offer lower weight, a compact footprint, faster charging, and longer service life under suitable operating conditions. These characteristics make them attractive for data centers and facilities where space efficiency and reliability are priorities. Modular UPS systems are also gaining attention as businesses seek scalable power protection. Modular configurations can allow facilities to expand capacity as requirements increase, helping operators manage investment and operational needs. The development of smart grids, cloud services, and connected industrial systems will further support demand for advanced backup solutions. Battery monitoring and management technologies can help operators track battery health, identify potential failures, and plan maintenance more effectively. Manufacturers will need to balance performance, safety, affordability, and environmental considerations as battery deployment increases. Get More Report Details: https://www.stellarmr.com/report/Asia-Pacific-UPS-Battery-Market/136 Segmentation Analysis According to Stellar Market Research, the Asia Pacific UPS Battery Market is segmented by topology, product type, and application. By Topology: Online, Standby, Line Interactive. By Product Type: Lead-acid, Lithium-Ion, Nickel Cadmium, Others. By Application: Residential, Commercial, Data Center, Industrial. Online UPS systems provide continuous power conditioning and are suitable for equipment requiring high levels of protection. Standby and line-interactive systems offer alternatives for applications with different power protection requirements. Within product types, lithium-ion batteries are projected to register strong growth because of their compact design, charging performance, and potential service-life advantages. By application, data centers represent a significant opportunity as cloud computing and digital services increase demand for dependable power infrastructure. The report identifies China as the leading country in the regional market, supported by its substantial digital infrastructure and investment in technology. Country-Level Analysis: USA and Germany United States: The United States is outside the geographic scope of this Asia Pacific report, but US-based companies participate in the broader UPS battery industry. Eaton Corporation and Vertiv Group Corporation are among the key players identified by Stellar Market Research. Their power management and critical-infrastructure solutions illustrate the importance of reliable backup power for data centers and industrial facilities. Germany: Germany is also outside the report's geographic scope. The study does not provide a separate German market valuation or forecast. For European industry context, the report identifies international suppliers operating in the wider power protection ecosystem, including Schneider Electric, although the company is headquartered in France rather than Germany. The market analysis therefore remains focused on Asia Pacific, where China, India, Japan, South Korea, Australia, ASEAN, and the rest of the region form the report's country coverage. Competitive Analysis The Asia Pacific UPS Battery Market features established battery manufacturers, electrical equipment suppliers, and power management companies. Key players identified by Stellar Market Research include CSB Battery Co., Ltd., East Penn Manufacturing Company, Eaton Corporation plc, Exide Industries Limited, FIAMM Energy Technology SpA, GS Yuasa International Ltd., Leoch International Technology Limited Inc., Schneider Electric SE, and Vertiv Group Corporation . Competition is shaped by battery performance, reliability, service life, safety, pricing, and compatibility with UPS systems. Companies investing in lithium-ion technology, intelligent monitoring, and scalable backup solutions may strengthen their position as data center and industrial power requirements grow. Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Asia-Pacific-UPS-Battery-Market/136 Press Release Conclusion The Asia Pacific UPS Battery Market is projected to reach USD 917.63 million by 2034 as digital infrastructure, data center development, telecommunications expansion, and industrial automation increase demand for dependable backup power. Although cost and maintenance considerations remain important, lithium-ion batteries, modular UPS systems, and advanced monitoring technologies are creating new opportunities. Manufacturers that combine reliability, efficiency, and competitive lifecycle costs will be well positioned to support the region's growing need for uninterrupted electricity. About Stellar Market Research: Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Contact Stellar Market Research: 3rd Floor, Navale IT Park, Phase 2 Pune Banglore Highway, Narhe, Pune, Maharashtra 411041, India [email protected] +91 20 6630 3320 | +91 9607365656
    0 Comments ·0 Shares ·386 Views
  • Building Information Modeling Market Cloud-Based Solutions and Collaboration Tools Report by MMR

    Unveiling the Latest Trends in the Building Information Modeling Market

    Maximize Market Research, a leading business consultancy firm, has released a comprehensive analysis of the Building Information Modeling Market. The report offers valuable business insights, including demand and pricing analysis, as well as an overview of the competitive landscape. It provides a detailed examination of the current state of the Building Information Modeling market, with projections extending through 2032

    Unlock more insights—request a free sample report now :https://www.maximizemarketresearch.com/request-sample/92636/

    Defining the Building Information Modeling Market Scope Through Comprehensive Research

    The Building Information Modeling market research delivers an in-depth analysis of key factors influencing industry growth, along with potential challenges that may arise. It provides stakeholders with a comprehensive understanding of the competitive landscape, including insights into leading companies, their product offerings, and emerging investment opportunities within the market. The report integrates both qualitative and quantitative insights, offering a well-rounded perspective on the industry’s current and future trajectory. Additionally, the MMR report includes a detailed competitive analysis, examining market players, their strategies, and key trends shaping the industry. The research is based on a blend of primary and secondary data sources, such as government publications, company websites, annual reports, and expert opinions from industry professionals and academics. Furthermore, the report identifies new market demands and trends, providing a thorough explanation of their impact on the Building Information Modeling market’s evolution. By addressing consumer preferences, regulatory frameworks, and technological advancements, the study equips businesses with actionable insights to navigate the industry’s dynamic landscape effectively.

    Explore Regional Insights and Market Dynamics in the Building Information Modeling Industry

    This report provides an in-depth regional analysis, covering essential aspects such as market size, growth rate, and trade activities, including imports and exports across different regions. By examining the geographic distribution of the Building Information Modeling market, the study offers a clear understanding of industry trends and market conditions in various countries.

    The Building Information Modeling market spans across North America, Europe, Asia Pacific, Latin America, Africa, and the Middle East, with each region presenting unique opportunities and challenges. This comprehensive analysis helps businesses identify regional growth potential, competitive landscapes, and key market drivers, enabling strategic decision-making in a dynamic global market

    Unlock the Key Market Segments Powering Building Information Modeling Industry Growth :

    The Global Building Information Modelling Market is worth USD 9.42 Billion in 2025 and is estimated to grow at a CAGR of 13.05% in the forecasted period. The forecasted revenue hints at a growth of around 22.22 billion USD by 2032.

    Gain more details with a free sample report. Inquire now :https://www.maximizemarketresearch.com/request-sample/92636/

    Breaking Down the Building Information Modeling Market: Key Segments Shaping the Industry

    by Component

    Software
    Services

    by Deployment Mode

    On Premise
    Cloud

    by Project Lifecycle Phase

    Pre Construction
    Construction
    Post Construction
    Operations and Maintenance

    by Building Type

    Commercial Buildings
    Residential Buildings
    Industrial Buildings
    Infrastructure
    Institutional Buildings

    by Enterprise Type

    Large Enterprises
    Small and Medium Enterprises

    by Technology

    Artificial Intelligence Driven BIM
    Augmented Reality Integrated BIM
    Virtual Reality Integrated BIM
    Internet of Things Enabled BIM
    Digital Twin Enabled BIM
    Cloud Collaboration BIM

    by Application

    Design and Modeling
    Construction Simulation
    Scheduling
    Clash Detection
    Conflict Resolution
    Cost Estimation
    Quantity Takeoff
    Sustainability and Energy Analysis
    Facility Management
    Asset Management
    Documentation and Visualization

    by End User

    Architects
    Engineers
    Contractors
    Developers
    Facility Managers
    Construction Managers
    Owners
    Government Agencies
    Consultants

    Meet the Industry Leaders Revolutionizing the Building Information Modeling Market

    Autodesk, Inc.
    Bentley Systems, Incorporated
    Trimble Inc.
    Dassault Systèmes SE
    Nemetschek SE
    Hexagon AB
    Oracle Corporation
    AVEVA Group plc
    Procore Technologies, Inc.
    Asite Solutions Ltd.
    Glodon Company Limited
    Topcon Positioning Systems, Inc.
    ACCA Software S.p.A.
    Dalux
    CYPE Ingenieros, S.A.
    KUBUS B.V.
    Plannerly
    Planon Group
    Pinnacle Infotech Ltd.
    Catenda
    Elecosoft plc
    BIMobject AB
    SoftTech Engineers Limited
    ConstructConnect, Inc.
    Ecodomus, Inc.

    Uncover Key Insights Answering the Biggest Questions in the Building Information Modeling Market

    What is Building Information Modeling ?
    What is the growth rate of the Building Information Modeling Market?
    Which are the factors expected to drive the Building Information Modeling market growth?
    What is the CAGR at which the Building Information Modeling market will grow during the forecast period?
    What are the different segments of the Building Information Modeling Market?
    Which is the fastest growing region in the Building Information Modeling market?
    What growth strategies are the players considering to increase their presence in Building Information Modeling ?
    What are the upcoming opportunities and trends for the Building Information Modeling Market?
    What are the recent industry trends that can be implemented to generate additional revenue streams for the Building Information Modeling Market?
    Who are the leading companies and what are their portfolios in Building Information Modeling Market?
    What segments are covered in the Building Information Modeling Market?
    Who are the key players in the Building Information Modeling market?
    Gain a Competitive Edge – Access Market Insights Through the Sample Link @https://www.maximizemarketresearch.com/market-report/global-building-information-modeling-bim-market/92636/

    Explore the Revolutionary Products Powering Market Success

    Past Size and Competitive Landscape
    Past Pricing and price curve by region
    Size, Share, Size Forecast by different segment
    Dynamics Growth Drivers, Restraints, Opportunities, and Key Trends by Region
    Segmentation A detailed analysis by segment with their sub-segments and Region
    Competitive Landscape Profiles of selected key players by region from a strategic perspective
    Explore Our Trending Reports to Stay Ahead of Industry Shifts :

    Global Internal Olefins Market https://www.maximizemarketresearch.com/market-report/global-internal-olefins-market/87141/
    Epichlorohydrin Market https://www.maximizemarketresearch.com/market-report/global-epichlorohydrin-market/66800/
    Neoprene Fabric Market https://www.maximizemarketresearch.com/market-report/neoprene-fabric-market/187312/

    Connect with Maximize Market Research for Expert Insights In-Depth Analysis :

    +91 9607365656

    [email protected]
    Building Information Modeling Market Cloud-Based Solutions and Collaboration Tools Report by MMR Unveiling the Latest Trends in the Building Information Modeling Market Maximize Market Research, a leading business consultancy firm, has released a comprehensive analysis of the Building Information Modeling Market. The report offers valuable business insights, including demand and pricing analysis, as well as an overview of the competitive landscape. It provides a detailed examination of the current state of the Building Information Modeling market, with projections extending through 2032 Unlock more insights—request a free sample report now :https://www.maximizemarketresearch.com/request-sample/92636/ Defining the Building Information Modeling Market Scope Through Comprehensive Research The Building Information Modeling market research delivers an in-depth analysis of key factors influencing industry growth, along with potential challenges that may arise. It provides stakeholders with a comprehensive understanding of the competitive landscape, including insights into leading companies, their product offerings, and emerging investment opportunities within the market. The report integrates both qualitative and quantitative insights, offering a well-rounded perspective on the industry’s current and future trajectory. Additionally, the MMR report includes a detailed competitive analysis, examining market players, their strategies, and key trends shaping the industry. The research is based on a blend of primary and secondary data sources, such as government publications, company websites, annual reports, and expert opinions from industry professionals and academics. Furthermore, the report identifies new market demands and trends, providing a thorough explanation of their impact on the Building Information Modeling market’s evolution. By addressing consumer preferences, regulatory frameworks, and technological advancements, the study equips businesses with actionable insights to navigate the industry’s dynamic landscape effectively. Explore Regional Insights and Market Dynamics in the Building Information Modeling Industry This report provides an in-depth regional analysis, covering essential aspects such as market size, growth rate, and trade activities, including imports and exports across different regions. By examining the geographic distribution of the Building Information Modeling market, the study offers a clear understanding of industry trends and market conditions in various countries. The Building Information Modeling market spans across North America, Europe, Asia Pacific, Latin America, Africa, and the Middle East, with each region presenting unique opportunities and challenges. This comprehensive analysis helps businesses identify regional growth potential, competitive landscapes, and key market drivers, enabling strategic decision-making in a dynamic global market Unlock the Key Market Segments Powering Building Information Modeling Industry Growth : The Global Building Information Modelling Market is worth USD 9.42 Billion in 2025 and is estimated to grow at a CAGR of 13.05% in the forecasted period. The forecasted revenue hints at a growth of around 22.22 billion USD by 2032. Gain more details with a free sample report. Inquire now :https://www.maximizemarketresearch.com/request-sample/92636/ Breaking Down the Building Information Modeling Market: Key Segments Shaping the Industry by Component Software Services by Deployment Mode On Premise Cloud by Project Lifecycle Phase Pre Construction Construction Post Construction Operations and Maintenance by Building Type Commercial Buildings Residential Buildings Industrial Buildings Infrastructure Institutional Buildings by Enterprise Type Large Enterprises Small and Medium Enterprises by Technology Artificial Intelligence Driven BIM Augmented Reality Integrated BIM Virtual Reality Integrated BIM Internet of Things Enabled BIM Digital Twin Enabled BIM Cloud Collaboration BIM by Application Design and Modeling Construction Simulation Scheduling Clash Detection Conflict Resolution Cost Estimation Quantity Takeoff Sustainability and Energy Analysis Facility Management Asset Management Documentation and Visualization by End User Architects Engineers Contractors Developers Facility Managers Construction Managers Owners Government Agencies Consultants Meet the Industry Leaders Revolutionizing the Building Information Modeling Market Autodesk, Inc. Bentley Systems, Incorporated Trimble Inc. Dassault Systèmes SE Nemetschek SE Hexagon AB Oracle Corporation AVEVA Group plc Procore Technologies, Inc. Asite Solutions Ltd. Glodon Company Limited Topcon Positioning Systems, Inc. ACCA Software S.p.A. Dalux CYPE Ingenieros, S.A. KUBUS B.V. Plannerly Planon Group Pinnacle Infotech Ltd. Catenda Elecosoft plc BIMobject AB SoftTech Engineers Limited ConstructConnect, Inc. Ecodomus, Inc. Uncover Key Insights Answering the Biggest Questions in the Building Information Modeling Market What is Building Information Modeling ? What is the growth rate of the Building Information Modeling Market? Which are the factors expected to drive the Building Information Modeling market growth? What is the CAGR at which the Building Information Modeling market will grow during the forecast period? What are the different segments of the Building Information Modeling Market? Which is the fastest growing region in the Building Information Modeling market? What growth strategies are the players considering to increase their presence in Building Information Modeling ? What are the upcoming opportunities and trends for the Building Information Modeling Market? What are the recent industry trends that can be implemented to generate additional revenue streams for the Building Information Modeling Market? Who are the leading companies and what are their portfolios in Building Information Modeling Market? What segments are covered in the Building Information Modeling Market? Who are the key players in the Building Information Modeling market? Gain a Competitive Edge – Access Market Insights Through the Sample Link @https://www.maximizemarketresearch.com/market-report/global-building-information-modeling-bim-market/92636/ Explore the Revolutionary Products Powering Market Success Past Size and Competitive Landscape Past Pricing and price curve by region Size, Share, Size Forecast by different segment Dynamics Growth Drivers, Restraints, Opportunities, and Key Trends by Region Segmentation A detailed analysis by segment with their sub-segments and Region Competitive Landscape Profiles of selected key players by region from a strategic perspective Explore Our Trending Reports to Stay Ahead of Industry Shifts : Global Internal Olefins Market https://www.maximizemarketresearch.com/market-report/global-internal-olefins-market/87141/ Epichlorohydrin Market https://www.maximizemarketresearch.com/market-report/global-epichlorohydrin-market/66800/ Neoprene Fabric Market https://www.maximizemarketresearch.com/market-report/neoprene-fabric-market/187312/ Connect with Maximize Market Research for Expert Insights In-Depth Analysis : +91 9607365656 [email protected]
    0 Comments ·0 Shares ·151 Views
  • Propylene Oxide Market Demand, Growth Drivers, and Future Outlook Report by MMR

    Propylene Oxide Market to Reach USD 36.04 Billion by 2034, Driven by Polyurethane Demand and Industrial Applications

    Market Overview

    The Propylene Oxide Market was valued at USD 21.7 billion in 2025 and is projected to reach USD 36.04 billion by 2034, registering a compound annual growth rate (CAGR) of 5.8% during the forecast period from 2026 to 2034. Increasing demand for polyurethane foams, expanding automotive production, infrastructure development, and the growing use of propylene oxide derivatives across industrial applications are supporting market expansion. Manufacturers are also focusing on production efficiency, supply chain optimization, and advanced chemical processing technologies to strengthen their competitive positions.

    Market Estimation, Growth Drivers, and Opportunities

    Propylene oxide is an important chemical intermediate used to manufacture polyether polyols, propylene glycol, glycol ethers, and specialty surfactants. These derivatives serve multiple industries, including automotive, construction, packaging, furniture and bedding, electronics, pharmaceuticals, and personal care.

    The market's growth is primarily driven by rising demand for polyurethane materials. Polyether polyols, produced using propylene oxide, are essential ingredients in flexible and rigid polyurethane foams used in mattresses, furniture, automotive seating, building insulation, and refrigeration systems. Increasing construction activity and demand for energy-efficient buildings are creating additional opportunities for polyurethane-based insulation materials.

    The expansion of electric vehicle manufacturing also supports market development. Polyurethane materials are used in vehicle interiors, cushioning, adhesives, coatings, and selected battery-related applications. Furthermore, propylene glycol is widely used in pharmaceutical formulations, cosmetics, food processing, and industrial fluids, creating opportunities across diverse downstream markets.

    Get a Sample Insight Report Now : https://www.maximizemarketresearch.com/request-sample/2515/

    United States Market Trends and Investment Outlook

    The United States remains an important market because of its established petrochemical infrastructure, integrated feedstock supply chains, and demand from automotive, construction, and industrial manufacturing sectors. In March 2025, LyondellBasell announced an investment to expand propylene production capacity at its Channelview Complex near Houston.
    Propylene Oxide Market Demand, Growth Drivers, and Future Outlook Report by MMR Propylene Oxide Market to Reach USD 36.04 Billion by 2034, Driven by Polyurethane Demand and Industrial Applications Market Overview The Propylene Oxide Market was valued at USD 21.7 billion in 2025 and is projected to reach USD 36.04 billion by 2034, registering a compound annual growth rate (CAGR) of 5.8% during the forecast period from 2026 to 2034. Increasing demand for polyurethane foams, expanding automotive production, infrastructure development, and the growing use of propylene oxide derivatives across industrial applications are supporting market expansion. Manufacturers are also focusing on production efficiency, supply chain optimization, and advanced chemical processing technologies to strengthen their competitive positions. Market Estimation, Growth Drivers, and Opportunities Propylene oxide is an important chemical intermediate used to manufacture polyether polyols, propylene glycol, glycol ethers, and specialty surfactants. These derivatives serve multiple industries, including automotive, construction, packaging, furniture and bedding, electronics, pharmaceuticals, and personal care. The market's growth is primarily driven by rising demand for polyurethane materials. Polyether polyols, produced using propylene oxide, are essential ingredients in flexible and rigid polyurethane foams used in mattresses, furniture, automotive seating, building insulation, and refrigeration systems. Increasing construction activity and demand for energy-efficient buildings are creating additional opportunities for polyurethane-based insulation materials. The expansion of electric vehicle manufacturing also supports market development. Polyurethane materials are used in vehicle interiors, cushioning, adhesives, coatings, and selected battery-related applications. Furthermore, propylene glycol is widely used in pharmaceutical formulations, cosmetics, food processing, and industrial fluids, creating opportunities across diverse downstream markets. Get a Sample Insight Report Now : https://www.maximizemarketresearch.com/request-sample/2515/ United States Market Trends and Investment Outlook The United States remains an important market because of its established petrochemical infrastructure, integrated feedstock supply chains, and demand from automotive, construction, and industrial manufacturing sectors. In March 2025, LyondellBasell announced an investment to expand propylene production capacity at its Channelview Complex near Houston.
    0 Comments ·0 Shares ·376 Views
  • Stellar Market Research today announced the release of its comprehensive intelligence report on the Instrument Transformer Market, highlighting a pivotal industry transformation driven by smart grid investments, renewable integration, and high-voltage direct current (HVDC) transmission upgrades.

    Traditionally viewed as passive electrical components, instrument transformers are experiencing a profound technological renaissance. The rapid acceleration of smart grid deployments, industrial automation, and the proliferation of digital substations utilizing IEC 61850 communication standards are redefining the market. Utilities and heavy industrial operators are increasingly pivoting toward optical and non-conventional instrument transformers (NCITs) to eliminate saturation risks, enhance cyber-secure data transmission, and reduce environmental footprints by eliminating oil-insulated infrastructure. This report provides critical decision-makers, grid operators, and institutional investors with granular intelligence on how technological convergence and decarbonization mandates are reshaping capital allocation across transmission and distribution (T&D) networks globally.

    Key Findings from the Report
    Market Valuation & Growth Trajectory: The global Instrument Transformer Market is projected to expand at a robust compound annual growth rate (CAGR) of over 6.2% throughout the forecast period, transitioning from a robust base year valuation toward substantial multi-billion-dollar milestones by 2033.

    Dominant Product Segment: Potential/Voltage Transformers (VTs) maintain the dominant market share, anchored by their indispensable role in revenue metering, system protection, and precise voltage regulation across high-voltage transmission corridors.

    Fastest-Growing Segment: Non-conventional and optical instrument transformers (NCITs) represent the fastest-growing segment, driven by digital substation retrofits, immunity to electromagnetic interference (EMI), and enhanced personnel safety.

    Voltage Class Breakdown: High-voltage (HV) and ultra-high-voltage (UHV) applications account for the largest revenue share, fueled by cross-border interconnections and long-distance bulk power evacuation projects.

    Regional Dominance: Asia-Pacific leads the global market, propelled by massive grid expansion programs in India, China, and Southeast Asia to accommodate surging electrification and renewable capacity additions.

    Emerging Regional Pocket: North America and Europe emerge as vital high-growth pockets, driven by aggressive replacement cycles for aging grid infrastructure and stringent regulatory mandates for grid resilience.

    Investment & Capital Focus: Private equity and strategic venture capital are heavily targeting manufacturers specializing in eco-friendly gas-insulated switchgear (GIS) compatible units and IoT-enabled smart sensors.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/instrument-transformer-market/2839
    Market Drivers and Restraints
    Drivers
    Accelerating Global Smart Grid & Digital Substation Investments: Utilities worldwide are committing billions to modernize transmission networks, integrating IoT sensors, automated fault detection, and digital communication protocols that necessitate advanced instrument transformers.

    Massive Integration of Renewable Energy Sources: The exponential growth of utility-scale solar and offshore wind farms requires precise monitoring and high-accuracy measurement equipment to stabilize intermittent power generation and maintain grid frequency.

    Rigorous Grid Reliability and Safety Mandates: Strict regulatory frameworks enforced by bodies such as the Federal Energy Regulatory Commission (FERC) and international counterparts compel utilities to upgrade outmoded protection relays, minimizing catastrophic blackouts.

    Restraints
    High Capital Expenditure for Advanced Retrofits: The transition from conventional electromagnetic transformers to optical or digital NCIT systems entails substantial upfront capital investments, creating budgetary friction for smaller municipal utilities.

    Supply Chain Vulnerabilities in Raw Materials: Persistent market price volatility in critical raw materials—including electrical steel, copper winding, and specialized insulating resins—continues to compress manufacturer profit margins and extend lead times.

    Technology, Regulation, and Sustainability Trends
    The instrument transformer sector is experiencing a profound operational transformation catalyzed by evolving environmental and technological standards. The industry is rapidly phasing out sulfur hexafluoride (SF6)—a potent greenhouse gas historically used for insulation—in favor of eco-friendly, dry-type, or alternative gas-insulated technologies that align with global Environmental, Social, and Governance (ESG) mandates. Furthermore, the integration of fiber-optic sensing and IoT-enabled condition monitoring allows real-time thermal and electrical profiling, enabling predictive maintenance that drastically reduces unplanned downtime. On the regulatory front, compliance with IEC 61850 interoperability standards has become a non-negotiable benchmark for market entry, compelling manufacturers to embed advanced digital communication interfaces directly into their hardware architecture.

    Regional Insights
    Asia-Pacific (APAC): Dominating the global landscape, APAC’s growth is anchored by massive state-backed grid modernization initiatives, such as India's revamped distribution sector schemes and China's UHV transmission superhighways. Rapid industrialization and rural electrification continue to drive immense volume demand.

    North America: Characterized by brownfield modernization, North American utilities are prioritizing grid hardening against extreme weather events and cyber-physical threats, accelerating the adoption of high-accuracy optical measurement solutions.

    Europe: Driven by the European Green Deal and ambitious offshore wind buildouts in the North Sea, Europe stands out for its stringent sustainability requirements, heavily favoring SF6-free and recyclable instrument transformer designs.

    Latin America & Middle East & Africa (MEA): Emerging as high-potential growth regions, MEA and Latin America are expanding inter-regional grid interconnectors and upgrading urban distribution networks to curb technical losses and accommodate mining and industrial loads.

    Recent Industry Developments
    ABB (2025): Launched an eco-efficient portfolio of medium-voltage instrument transformers utilizing alternative insulation gases, achieving a 99% reduction in global warming potential (GWP) and helping European utilities meet strict corporate carbon-neutrality targets.

    Siemens Energy (2025): Expanded its digital substation manufacturing capacity in Nuremberg, Germany, integrating advanced optical sensor calibration lines to meet a 35% surge in European orders for IEC 61850-compliant non-conventional instrument transformers.

    Schneider Electric (2024): Formed a strategic partnership with a leading IoT analytics firm to embed real-time thermal monitoring software directly into outdoor high-voltage current transformers, boosting asset lifespan by an estimated 20%.

    GE Vernova (2024): Secured a major multi-year supply agreement with a primary North American transmission grid operator to deploy advanced fiber-optic current sensors, significantly improving fault-detection speed across critical interstate corridors.

    Mitsubishi Electric (2026): Completed a strategic production facility expansion in India, aiming to scale up domestic manufacturing of high-voltage instrument transformers to support rapid regional grid buildouts under the National Infrastructure Pipeline.

    Competitive Landscape
    The global Instrument Transformer Market features a consolidated yet fiercely competitive landscape characterized by major multinational electrical equipment manufacturers leveraging mergers, strategic joint ventures, and technological differentiation. Key market leaders—including ABB, Siemens Energy, Schneider Electric, GE Vernova, Mitsubishi Electric, Arteche, Ritz Instrument Transformers, and Eaton Corporation—are actively focusing on portfolio expansion toward digital, SF6-free, and smart-sensor-embedded solutions. Leading players are also strengthening their regional distribution networks and engaging in long-term supply agreements with transmission system operators (TSOs) to secure dominant market positioning.

    Analyst Commentary
    "The instrument transformer market is no longer defined merely by electrical accuracy; it is now the foundational nerve center of the digital grid," said a Senior Research Analyst at Stellar Market Research. "As utilities race to integrate decentralized renewables and deploy AI-driven grid management systems, the ability to deliver real-time, cyber-secure, and eco-friendly measurement data will separate market leaders from legacy laggards. Strategic investments in non-conventional and optical sensing technologies are paramount for capturing long-term value through 2033."

    Future Outlook
    Looking ahead through the forecast period, demand for instrument transformers will remain closely tied to global decarbonization trajectories and accelerated electrification. As artificial intelligence and machine learning permeate substation automation, instrument transformers will increasingly function as smart edge-computing nodes capable of autonomous anomaly detection. Investment flows are projected to heavily favor manufacturers providing modular, interoperable, and fully recyclable hardware solutions, ensuring resilient growth amidst shifting geopolitical and regulatory paradigms.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/instrument-transformer-market/2839
    About Stellar Market Research
    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Address
    Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041

    Email
    [email protected]

    Mobile
    +91 9607365656
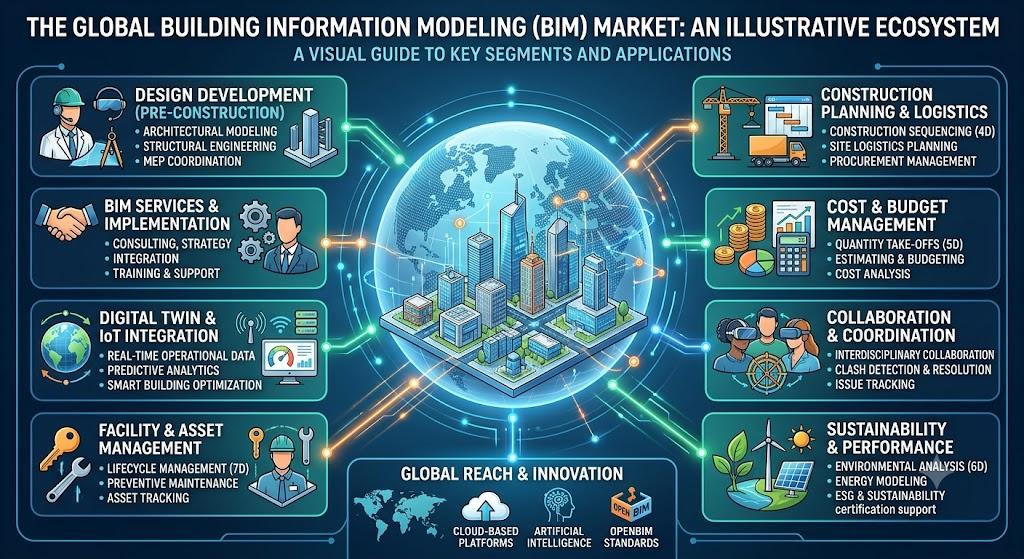
    Stellar Market Research today announced the release of its comprehensive intelligence report on the Instrument Transformer Market, highlighting a pivotal industry transformation driven by smart grid investments, renewable integration, and high-voltage direct current (HVDC) transmission upgrades. Traditionally viewed as passive electrical components, instrument transformers are experiencing a profound technological renaissance. The rapid acceleration of smart grid deployments, industrial automation, and the proliferation of digital substations utilizing IEC 61850 communication standards are redefining the market. Utilities and heavy industrial operators are increasingly pivoting toward optical and non-conventional instrument transformers (NCITs) to eliminate saturation risks, enhance cyber-secure data transmission, and reduce environmental footprints by eliminating oil-insulated infrastructure. This report provides critical decision-makers, grid operators, and institutional investors with granular intelligence on how technological convergence and decarbonization mandates are reshaping capital allocation across transmission and distribution (T&D) networks globally. Key Findings from the Report Market Valuation & Growth Trajectory: The global Instrument Transformer Market is projected to expand at a robust compound annual growth rate (CAGR) of over 6.2% throughout the forecast period, transitioning from a robust base year valuation toward substantial multi-billion-dollar milestones by 2033. Dominant Product Segment: Potential/Voltage Transformers (VTs) maintain the dominant market share, anchored by their indispensable role in revenue metering, system protection, and precise voltage regulation across high-voltage transmission corridors. Fastest-Growing Segment: Non-conventional and optical instrument transformers (NCITs) represent the fastest-growing segment, driven by digital substation retrofits, immunity to electromagnetic interference (EMI), and enhanced personnel safety. Voltage Class Breakdown: High-voltage (HV) and ultra-high-voltage (UHV) applications account for the largest revenue share, fueled by cross-border interconnections and long-distance bulk power evacuation projects. Regional Dominance: Asia-Pacific leads the global market, propelled by massive grid expansion programs in India, China, and Southeast Asia to accommodate surging electrification and renewable capacity additions. Emerging Regional Pocket: North America and Europe emerge as vital high-growth pockets, driven by aggressive replacement cycles for aging grid infrastructure and stringent regulatory mandates for grid resilience. Investment & Capital Focus: Private equity and strategic venture capital are heavily targeting manufacturers specializing in eco-friendly gas-insulated switchgear (GIS) compatible units and IoT-enabled smart sensors. For further information, click the following link:https://www.stellarmr.com/report/req_sample/instrument-transformer-market/2839 Market Drivers and Restraints Drivers Accelerating Global Smart Grid & Digital Substation Investments: Utilities worldwide are committing billions to modernize transmission networks, integrating IoT sensors, automated fault detection, and digital communication protocols that necessitate advanced instrument transformers. Massive Integration of Renewable Energy Sources: The exponential growth of utility-scale solar and offshore wind farms requires precise monitoring and high-accuracy measurement equipment to stabilize intermittent power generation and maintain grid frequency. Rigorous Grid Reliability and Safety Mandates: Strict regulatory frameworks enforced by bodies such as the Federal Energy Regulatory Commission (FERC) and international counterparts compel utilities to upgrade outmoded protection relays, minimizing catastrophic blackouts. Restraints High Capital Expenditure for Advanced Retrofits: The transition from conventional electromagnetic transformers to optical or digital NCIT systems entails substantial upfront capital investments, creating budgetary friction for smaller municipal utilities. Supply Chain Vulnerabilities in Raw Materials: Persistent market price volatility in critical raw materials—including electrical steel, copper winding, and specialized insulating resins—continues to compress manufacturer profit margins and extend lead times. Technology, Regulation, and Sustainability Trends The instrument transformer sector is experiencing a profound operational transformation catalyzed by evolving environmental and technological standards. The industry is rapidly phasing out sulfur hexafluoride (SF6)—a potent greenhouse gas historically used for insulation—in favor of eco-friendly, dry-type, or alternative gas-insulated technologies that align with global Environmental, Social, and Governance (ESG) mandates. Furthermore, the integration of fiber-optic sensing and IoT-enabled condition monitoring allows real-time thermal and electrical profiling, enabling predictive maintenance that drastically reduces unplanned downtime. On the regulatory front, compliance with IEC 61850 interoperability standards has become a non-negotiable benchmark for market entry, compelling manufacturers to embed advanced digital communication interfaces directly into their hardware architecture. Regional Insights Asia-Pacific (APAC): Dominating the global landscape, APAC’s growth is anchored by massive state-backed grid modernization initiatives, such as India's revamped distribution sector schemes and China's UHV transmission superhighways. Rapid industrialization and rural electrification continue to drive immense volume demand. North America: Characterized by brownfield modernization, North American utilities are prioritizing grid hardening against extreme weather events and cyber-physical threats, accelerating the adoption of high-accuracy optical measurement solutions. Europe: Driven by the European Green Deal and ambitious offshore wind buildouts in the North Sea, Europe stands out for its stringent sustainability requirements, heavily favoring SF6-free and recyclable instrument transformer designs. Latin America & Middle East & Africa (MEA): Emerging as high-potential growth regions, MEA and Latin America are expanding inter-regional grid interconnectors and upgrading urban distribution networks to curb technical losses and accommodate mining and industrial loads. Recent Industry Developments ABB (2025): Launched an eco-efficient portfolio of medium-voltage instrument transformers utilizing alternative insulation gases, achieving a 99% reduction in global warming potential (GWP) and helping European utilities meet strict corporate carbon-neutrality targets. Siemens Energy (2025): Expanded its digital substation manufacturing capacity in Nuremberg, Germany, integrating advanced optical sensor calibration lines to meet a 35% surge in European orders for IEC 61850-compliant non-conventional instrument transformers. Schneider Electric (2024): Formed a strategic partnership with a leading IoT analytics firm to embed real-time thermal monitoring software directly into outdoor high-voltage current transformers, boosting asset lifespan by an estimated 20%. GE Vernova (2024): Secured a major multi-year supply agreement with a primary North American transmission grid operator to deploy advanced fiber-optic current sensors, significantly improving fault-detection speed across critical interstate corridors. Mitsubishi Electric (2026): Completed a strategic production facility expansion in India, aiming to scale up domestic manufacturing of high-voltage instrument transformers to support rapid regional grid buildouts under the National Infrastructure Pipeline. Competitive Landscape The global Instrument Transformer Market features a consolidated yet fiercely competitive landscape characterized by major multinational electrical equipment manufacturers leveraging mergers, strategic joint ventures, and technological differentiation. Key market leaders—including ABB, Siemens Energy, Schneider Electric, GE Vernova, Mitsubishi Electric, Arteche, Ritz Instrument Transformers, and Eaton Corporation—are actively focusing on portfolio expansion toward digital, SF6-free, and smart-sensor-embedded solutions. Leading players are also strengthening their regional distribution networks and engaging in long-term supply agreements with transmission system operators (TSOs) to secure dominant market positioning. Analyst Commentary "The instrument transformer market is no longer defined merely by electrical accuracy; it is now the foundational nerve center of the digital grid," said a Senior Research Analyst at Stellar Market Research. "As utilities race to integrate decentralized renewables and deploy AI-driven grid management systems, the ability to deliver real-time, cyber-secure, and eco-friendly measurement data will separate market leaders from legacy laggards. Strategic investments in non-conventional and optical sensing technologies are paramount for capturing long-term value through 2033." Future Outlook Looking ahead through the forecast period, demand for instrument transformers will remain closely tied to global decarbonization trajectories and accelerated electrification. As artificial intelligence and machine learning permeate substation automation, instrument transformers will increasingly function as smart edge-computing nodes capable of autonomous anomaly detection. Investment flows are projected to heavily favor manufacturers providing modular, interoperable, and fully recyclable hardware solutions, ensuring resilient growth amidst shifting geopolitical and regulatory paradigms. For further information, click the following link:https://www.stellarmr.com/report/req_sample/instrument-transformer-market/2839 About Stellar Market Research Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Address Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041 Email [email protected] Mobile +91 9607365656
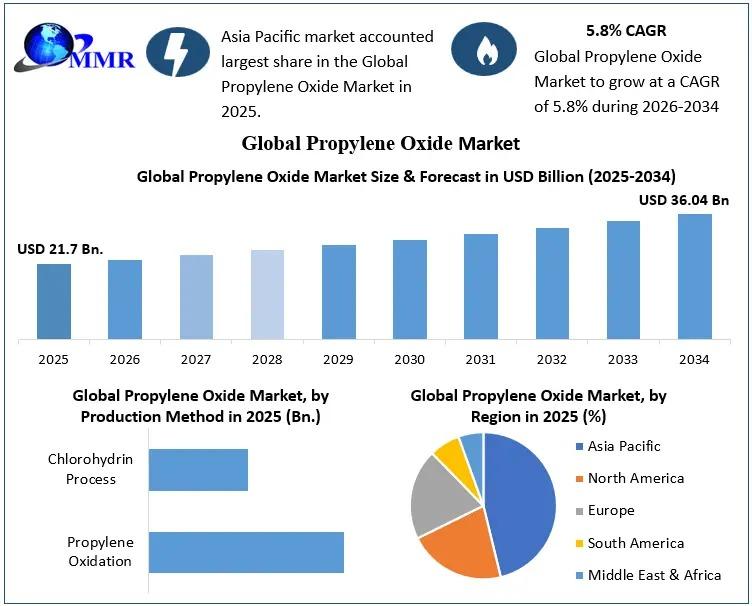
    0 Comments ·0 Shares ·402 Views
  • The Guar Gum Market is projected to achieve monumental growth. According to a comprehensive market intelligence report published by Stellar Market Research, the global market size was valued at USD 1.11 billion in 2025 and is poised to expand at a robust compound annual growth rate (CAGR) of 7.4% from 2026 to 2034, reaching nearly USD 2.1 billion by the end of the forecast period.

    The global guar gum landscape is undergoing a structural pivot defined by dual-engine demand: high-performance energy extraction and health-conscious consumerism. Processed primarily from the endosperm of the cluster bean (Cyamopsis tetragonoloba), guar gum’s unique ability to form hydrogen bonds with water molecules makes it an irreplaceable natural hydrocolloid.

    Key Findings from the Report
    Valuation & Growth Trajectory: The global guar gum market reached USD 1.11 billion in 2025 and is projected to scale to USD 2.1 billion by 2034, registering a 7.4% CAGR.

    Grade Segment Dominance: The Food grade segment held the leading market share in 2025, propelled by surging demand for clean-label, low-fat, and convenience foods.

    Application Segment Insights: The Oil & Gas application segment captured the largest market share (37.62%) in 2025, heavily driven by North American shale gas extraction and global drilling projects.

    Functional Insights: Stabilizers and emulsifiers dominated functional segments with a 54.38% market share in 2025, expanding at a projected 6.9% CAGR due to widespread utility in dairy, confectionery, and personal care.

    Geographical Leadership: North America commanded a 43.2% market share in 2025, underpinned by extensive shale operations and robust processed food consumption.

    Production Hub: Asia-Pacific—led by India, which accounts for approximately 65% to 78% of global exports and production—remains the indispensable agricultural backbone of the supply chain.

    Investment Relevance: Rising trade volumes (such as India exporting over 417,000 metric tons valued at USD 541.65 million) highlight immense investment opportunities in seed quality, processing efficiency, and supply chain logistics.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/guar-gum-market/2828

    Market Drivers and Restraints
    Drivers:
    Shale Gas Exploration and Drilling Expansion: The rapid expansion of hydraulic fracturing in North America and emerging regions requires high-viscosity friction reducers, cementing guar gum's critical role in energy extraction.

    Explosion of Clean-Label and Convenience Foods: Changing lifestyles, urban work hours, and rising disposable incomes have elevated convenience food consumption, driving demand for natural stabilizers in soups, sauces, bakery items, and frozen desserts.

    Nutritional and Health Benefits: Heightened consumer focus on functional foods that improve glucose tolerance, reduce serum LDL cholesterol, and provide soluble dietary fiber is accelerating plant hydrocolloid utilization.

    Restraints:
    Raw Material Price Volatility: Unpredictable weather patterns, monsoon variability, and fluctuating crop yields in key agricultural belts cause sharp raw material price swings.

    Limited R&D and Infrastructure Deficits: A historical lack of specialized research facilities, certified seed breeding programs, and modernized processing machinery in primary producing regions constrains yield optimization and technological upgrading.

    Technology, Regulation, and Sustainability Trends
    The guar gum industry is undergoing rapid modernization driven by evolving compliance standards and technological integration. Regulatory bodies like the U.S. Food and Drug Administration (FDA) recognize guar gum as safe (GRAS) within specified limits, fostering consumer trust.

    On the operational front, processors are adopting advanced thermal-mechanical processing techniques to enhance powder solubility, lower microbial loads, and tailor viscosity profiles for specialized industrial uses. Furthermore, sustainability and ESG considerations are taking center stage; agricultural stakeholders are promoting climate-resilient cluster bean farming, micro-irrigation, and certified seed adoption to reduce environmental footprints and stabilize farmer incomes against climate shocks.

    Regional Insights
    North America: Dominating the global landscape with a 43.2% market share in 2025, North America's leadership is anchored by extensive shale oil and gas operations in Texas and widespread adoption of functional, low-calorie convenience foods. The U.S. alone accounts for over 41% of global guar gum imports.

    Asia-Pacific: Serving as the world's primary cultivation hub, India and Pakistan drive global supply. India contributes roughly 65% to 78% of global exports, with robust export growth heading into Western markets. Domestic cultivation is also expanding in response to international demand.

    Europe & Emerging Markets: Europe maintains steady demand driven by stringent clean-label food standards and pharmaceutical binder applications, while emerging markets in the Middle East and Latin America show rising promise in water treatment and mining sectors.

    Recent Industry Developments
    VedaOils (2025): Expanded its organic cosmetic-grade guar gum powder portfolio, capturing a wider footprint in natural personal care formulations and increasing eco-friendly product output by 15%.

    Sunita Hydrocolloids (2024): Invested in upgraded hydro-thermal processing units at its Rajasthan facility, boosting high-viscosity industrial-grade production capacity by 20% to meet North American oilfield demands.

    APEDA & Indian Exporters Consortium (2025): Implemented streamlined agricultural export quality certification protocols, stabilizing outbound shipments which crossed 417,000 metric tons valued at over USD 541 million.

    Global Hydrocolloids (2024): Formed a strategic supply partnership with major North American oilfield service providers, securing long-term delivery contracts for frac-grade fracturing guar.

    Agricultural Universities of Rajasthan & Gujarat (2024): Launched collaborative drought-resistant cluster bean seed development initiatives, improving agricultural yields by 8–10% for participating regional farmers.

    Competitive Landscape
    The global guar gum market features a consolidated yet competitive landscape characterized by integrated processors, specialized refiners, and multinational ingredient suppliers. Leading players are focusing on backward integration, strategic export partnerships, and customized grade formulations for pharmaceutical and oilfield applications.

    Key market participants profiled in the report include Sunita Hydrocolloids, Vikas WSP Ltd., Hindustan Gum & Chemicals Ltd., Cargill, Inc., Ashland Global Holdings Inc., Kerry Group, and Lotus Gums & Chemicals. These companies actively deploy capacity expansions, joint ventures, and customized bio-polymer innovations to reinforce their market positioning.

    Analyst Commentary
    "The guar gum market has evolved far beyond traditional food stabilization into a high-tech biopolymer essential for modern energy extraction and advanced pharmaceutical drug delivery," said a Senior Research Analyst at Stellar Market Research. "While agricultural volatility and processing infrastructure bottlenecks remain challenges, the pivot toward sustainable, plant-based hydrocolloids and enhanced shale exploration guarantees a lucrative pathway for stakeholders willing to invest in R&D and supply chain transparency through 2034."

    Future Outlook
    Looking toward 2034, the guar gum market is set for sustained evolution. Demand will increasingly favor high-purity, enzymatically modified, and sustainably sourced derivatives. Investment will concentrate on digitalizing agricultural supply chains, establishing dedicated R&D institutes for cluster bean genetics, and optimizing eco-friendly extraction technologies. As regulatory frameworks tighten around synthetic additives, natural hydrocolloids like guar gum will secure an irreplaceable strategic role across industrial ecosystems worldwide.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/guar-gum-market/2828

    About Stellar Market Research

    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Address
    Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041

    Email
    [email protected]

    Mobile
    +91 9607365656
    The Guar Gum Market is projected to achieve monumental growth. According to a comprehensive market intelligence report published by Stellar Market Research, the global market size was valued at USD 1.11 billion in 2025 and is poised to expand at a robust compound annual growth rate (CAGR) of 7.4% from 2026 to 2034, reaching nearly USD 2.1 billion by the end of the forecast period. The global guar gum landscape is undergoing a structural pivot defined by dual-engine demand: high-performance energy extraction and health-conscious consumerism. Processed primarily from the endosperm of the cluster bean (Cyamopsis tetragonoloba), guar gum’s unique ability to form hydrogen bonds with water molecules makes it an irreplaceable natural hydrocolloid. Key Findings from the Report Valuation & Growth Trajectory: The global guar gum market reached USD 1.11 billion in 2025 and is projected to scale to USD 2.1 billion by 2034, registering a 7.4% CAGR. Grade Segment Dominance: The Food grade segment held the leading market share in 2025, propelled by surging demand for clean-label, low-fat, and convenience foods. Application Segment Insights: The Oil & Gas application segment captured the largest market share (37.62%) in 2025, heavily driven by North American shale gas extraction and global drilling projects. Functional Insights: Stabilizers and emulsifiers dominated functional segments with a 54.38% market share in 2025, expanding at a projected 6.9% CAGR due to widespread utility in dairy, confectionery, and personal care. Geographical Leadership: North America commanded a 43.2% market share in 2025, underpinned by extensive shale operations and robust processed food consumption. Production Hub: Asia-Pacific—led by India, which accounts for approximately 65% to 78% of global exports and production—remains the indispensable agricultural backbone of the supply chain. Investment Relevance: Rising trade volumes (such as India exporting over 417,000 metric tons valued at USD 541.65 million) highlight immense investment opportunities in seed quality, processing efficiency, and supply chain logistics. For further information, click the following link:https://www.stellarmr.com/report/req_sample/guar-gum-market/2828 Market Drivers and Restraints Drivers: Shale Gas Exploration and Drilling Expansion: The rapid expansion of hydraulic fracturing in North America and emerging regions requires high-viscosity friction reducers, cementing guar gum's critical role in energy extraction. Explosion of Clean-Label and Convenience Foods: Changing lifestyles, urban work hours, and rising disposable incomes have elevated convenience food consumption, driving demand for natural stabilizers in soups, sauces, bakery items, and frozen desserts. Nutritional and Health Benefits: Heightened consumer focus on functional foods that improve glucose tolerance, reduce serum LDL cholesterol, and provide soluble dietary fiber is accelerating plant hydrocolloid utilization. Restraints: Raw Material Price Volatility: Unpredictable weather patterns, monsoon variability, and fluctuating crop yields in key agricultural belts cause sharp raw material price swings. Limited R&D and Infrastructure Deficits: A historical lack of specialized research facilities, certified seed breeding programs, and modernized processing machinery in primary producing regions constrains yield optimization and technological upgrading. Technology, Regulation, and Sustainability Trends The guar gum industry is undergoing rapid modernization driven by evolving compliance standards and technological integration. Regulatory bodies like the U.S. Food and Drug Administration (FDA) recognize guar gum as safe (GRAS) within specified limits, fostering consumer trust. On the operational front, processors are adopting advanced thermal-mechanical processing techniques to enhance powder solubility, lower microbial loads, and tailor viscosity profiles for specialized industrial uses. Furthermore, sustainability and ESG considerations are taking center stage; agricultural stakeholders are promoting climate-resilient cluster bean farming, micro-irrigation, and certified seed adoption to reduce environmental footprints and stabilize farmer incomes against climate shocks. Regional Insights North America: Dominating the global landscape with a 43.2% market share in 2025, North America's leadership is anchored by extensive shale oil and gas operations in Texas and widespread adoption of functional, low-calorie convenience foods. The U.S. alone accounts for over 41% of global guar gum imports. Asia-Pacific: Serving as the world's primary cultivation hub, India and Pakistan drive global supply. India contributes roughly 65% to 78% of global exports, with robust export growth heading into Western markets. Domestic cultivation is also expanding in response to international demand. Europe & Emerging Markets: Europe maintains steady demand driven by stringent clean-label food standards and pharmaceutical binder applications, while emerging markets in the Middle East and Latin America show rising promise in water treatment and mining sectors. Recent Industry Developments VedaOils (2025): Expanded its organic cosmetic-grade guar gum powder portfolio, capturing a wider footprint in natural personal care formulations and increasing eco-friendly product output by 15%. Sunita Hydrocolloids (2024): Invested in upgraded hydro-thermal processing units at its Rajasthan facility, boosting high-viscosity industrial-grade production capacity by 20% to meet North American oilfield demands. APEDA & Indian Exporters Consortium (2025): Implemented streamlined agricultural export quality certification protocols, stabilizing outbound shipments which crossed 417,000 metric tons valued at over USD 541 million. Global Hydrocolloids (2024): Formed a strategic supply partnership with major North American oilfield service providers, securing long-term delivery contracts for frac-grade fracturing guar. Agricultural Universities of Rajasthan & Gujarat (2024): Launched collaborative drought-resistant cluster bean seed development initiatives, improving agricultural yields by 8–10% for participating regional farmers. Competitive Landscape The global guar gum market features a consolidated yet competitive landscape characterized by integrated processors, specialized refiners, and multinational ingredient suppliers. Leading players are focusing on backward integration, strategic export partnerships, and customized grade formulations for pharmaceutical and oilfield applications. Key market participants profiled in the report include Sunita Hydrocolloids, Vikas WSP Ltd., Hindustan Gum & Chemicals Ltd., Cargill, Inc., Ashland Global Holdings Inc., Kerry Group, and Lotus Gums & Chemicals. These companies actively deploy capacity expansions, joint ventures, and customized bio-polymer innovations to reinforce their market positioning. Analyst Commentary "The guar gum market has evolved far beyond traditional food stabilization into a high-tech biopolymer essential for modern energy extraction and advanced pharmaceutical drug delivery," said a Senior Research Analyst at Stellar Market Research. "While agricultural volatility and processing infrastructure bottlenecks remain challenges, the pivot toward sustainable, plant-based hydrocolloids and enhanced shale exploration guarantees a lucrative pathway for stakeholders willing to invest in R&D and supply chain transparency through 2034." Future Outlook Looking toward 2034, the guar gum market is set for sustained evolution. Demand will increasingly favor high-purity, enzymatically modified, and sustainably sourced derivatives. Investment will concentrate on digitalizing agricultural supply chains, establishing dedicated R&D institutes for cluster bean genetics, and optimizing eco-friendly extraction technologies. As regulatory frameworks tighten around synthetic additives, natural hydrocolloids like guar gum will secure an irreplaceable strategic role across industrial ecosystems worldwide. For further information, click the following link:https://www.stellarmr.com/report/req_sample/guar-gum-market/2828 About Stellar Market Research Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Address Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041 Email [email protected] Mobile +91 9607365656
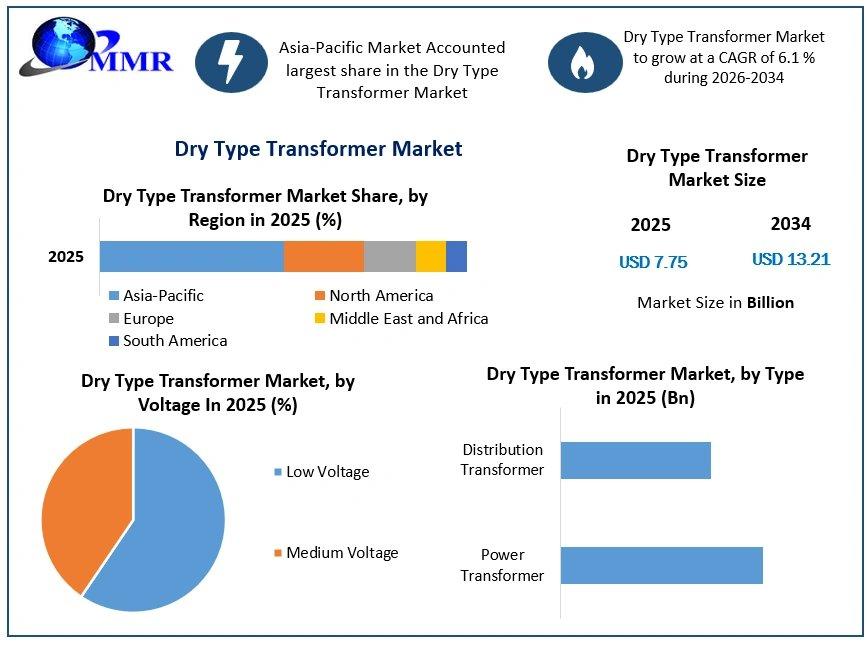
    0 Comments ·0 Shares ·984 Views
  • Stellar Market Research has released a comprehensive intelligence study on the Wood Chips Market, revealing that the industry is undergoing a structural evolution driven by global decarbonization mandates and renewable energy transitions. Valued at USD 12.11 Billion in 2025, the market is projected to reach USD 23.60 Billion by 2032, expanding at a remarkable compound annual growth rate (CAGR) of 10% during the forecast period. The report underscores the strategic importance of wood chips as a versatile biomass feedstock critical for meeting international climate targets while ensuring reliable industrial and residential heat generation.

    The global energy matrix is undergoing a profound paradigm shift, moving decisively away from fossil fuel reliance toward decentralized renewable alternatives. Within this transformation, the wood chips market has emerged as a linchpin for circular bioeconomy initiatives. Driven by tightening carbon emission policies and the necessity for secure, localized heat and power sources, commercial enterprises and municipal utilities are actively restructuring their fuel supply chains.

    Key Findings from the Report
    Market Valuation & Trajectory: The global Wood Chips Market reached USD 12.11 Billion in 2025 and is projected to expand to USD 23.60 Billion by 2032 at a 10% CAGR.

    Dominant Product Segment: The Softwood segment commanded the largest market share at 46% in 2025, primarily driven by widespread utilization in garden mulching, playground surfacing, and high-volume industrial applications.

    Leading Application Category: Residential Heating dominated application channels with a 38% market share in 2025, supported by widespread global adoption of eco-friendly home heating solutions.

    Regional Dominance: The Asia-Pacific region captured a leading 39% market share in 2025, heavily reinforced by government feed-in-tariff subsidy schemes and expanding biomass project pipelines in countries like Japan.

    High-Growth Regional Frontier: Europe is forecast to register steady, high-value growth at a 9.92% CAGR over the forecast period, anchored by decentralized small-scale combined heat and power (CHP) installations.

    Pulp & Paper Integration: The increasing demand for wood chips as a primary raw material in pulp mills continues to provide a stable industrial baseline for continuous market expansion.

    Investment & Diversification Potential: Emerging interest in advanced applications—such as utilizing nanocrystalline cellulose (NCC) extracted from wood pulp for next-generation flexible electronics—is unlocking new commercial horizons for market stakeholders.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/Wood-Chips-Market/485

    Market Drivers and Restraints
    Driver 1: Accelerated Transition to Renewable Biomass Energy: Escalating depletion of conventional fossil fuels and stringent international climate protocols are compelling governments and utility providers to scale up biomass solid fuel utilization.

    Driver 2: Surging Demand from the Pulp and Paper Sector: Continuous capacity expansions across global pulp mills require reliable, high-grade wood chip inputs to satisfy paper, packaging, and derivative product manufacturing needs.

    Driver 3: Proliferation of Eco-Friendly Landscaping and Composting: Rising consumer and municipal preference for organic soil amendments, playground safety surfacing, and sustainable garden mulch acts as a consistent secondary growth catalyst.

    Restraint 1: Intense Competition from Alternative Biofuels: The growing popularity and commercial scaling of wood pellets as an alternative dense fuel pose a competitive threat, particularly in commercial power generation segments.

    Restraint 2: Strict GHG Emissions Compliance and Certification Hurdles: Regulatory burdens regarding greenhouse gas emissions standards and the high cost of acquiring sustainability-related forestry certifications can impede rapid supply chain scaling.

    Technology, Regulation, and Sustainability Trends
    The industry is experiencing profound operational transformation through the adoption of advanced digital log loaders, automated de-wrapping stations, and precision chipping technology designed to minimize waste and optimize fiber recovery. Regulatory frameworks are increasingly prioritizing carbon accountability; policy instruments such as carbon pricing and strict sustainability compliance require market players to maintain transparent, traceable sourcing operations. Simultaneously, ESG (Environmental, Social, and Governance) imperatives are accelerating reforestation partnerships and waste-to-energy circularity, ensuring that wood chip harvesting actively balances ecological restoration with commercial output.

    Regional Insights
    Asia-Pacific: Securing a commanding 39% market share in 2025, Asia-Pacific represents the epicenter of global consumption. Japan continues to spearhead regional expansion by leveraging robust Feed-in-Tariff (FiT) subsidy mechanisms to construct extensive biomass energy generation pipelines, while major developing economies scale up domestic pulp production infrastructure.

    Europe: Europe is poised to record a stellar 9.92% CAGR through the forecast period. The region's growth is anchored by established small-scale (sub-20MW) combined heat and power (CHP) infrastructure that predominantly utilizes locally sourced wood, satisfying rigorous EU renewable energy directives.

    North America: Supported by well-established commercial forestry networks in the United States and Canada, North America remains a highly consolidated market focused on supply chain optimization, advanced wood processing technology, and export efficiency.

    Recent Industry Developments
    River City Fibre LP (2025): Deployed a USD 600,000 modernization investment backed by local public-private funding to integrate an electric log loader and de-wrapping station in Kamloops, boosting low-value pulp log processing efficiency while cutting operational emissions.

    Eternali (2024): Expanded its Brazilian operational footprint by acquiring 3.3 hectares of land in Moju, Pará, to construct a dedicated wood chip production facility designed to feed regional biomass energy demands using locally sourced sawmill residues.

    Ørsted A/S (2024): Announced strategic plans to expand its European biomass power generation portfolio, driving substantial long-term demand commitments for sustainable wood chip fuel supplies.

    Great Northern Timber (2024): Partnered with local ecological conservation groups to initiate structured reforestation projects in harvested timber tracts, establishing a verifiable precedent for balancing commercial wood chip harvesting with active ecosystem restoration.

    Drax Group (2024): Committed a USD 300 million capital investment toward the construction of advanced biomass power generation and renewable energy infrastructure in Scotland, driving long-term market demand for sustainably certified wood chips.

    Competitive Landscape
    The global wood chips market exhibits a semi-consolidated competitive structure characterized by the active participation of major forestry conglomerates, specialized biomass processors, and regional market players. Leading industry participants are actively pursuing strategic supply chain integration, technological modernization, and long-term municipal procurement partnerships. Key companies profiled in the market intelligence landscape include Enviva Inc., Drax Group, Weyerhaeuser Company, West Fraser Timber Co. Ltd., International Paper Company, St. Boniface Pallet Company Ltd., EVOWORLD GmbH, and American Wood Resources. Major players are increasingly emphasizing certified sustainable forestry practices and processing efficiency to capture high-margin supply agreements across European and Asian energy corridors.

    Analyst Commentary
    "The wood chips market has transitioned far beyond a conventional forestry byproduct sector into an essential pillar of the global bio-energy and bio-materials economy," said a Senior Research Analyst at Stellar Market Research. "As corporate sustainability mandates and government decarbonization targets tighten through 2032, market participants that invest in supply chain traceability, advanced fiber processing efficiency, and localized sourcing networks will capture outsized value. The ability to guarantee compliant, low-carbon biomass feedstocks will ultimately separate market leaders from legacy followers."

    Future Outlook
    Looking ahead through the 2026–2032 forecast horizon, the wood chips market is expected to experience sustained, high-value expansion. Demand dynamics will increasingly pivot toward high-efficiency combined heat and power (CHP) applications and innovative high-tech bio-refining avenues, such as nanocrystalline cellulose production. While regulatory frameworks and carbon accounting standards will grow more stringent, they will simultaneously reward forward-thinking operators who embrace certified sustainable forestry. Supported by robust infrastructure investments across Asia-Pacific and Europe, the market is well-positioned to cement its role as a cornerstone of the global green energy transition.

    For further information, click the following link:https://www.stellarmr.com/report/req_sample/Wood-Chips-Market/485 

    About Stellar Market Research

    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Address
    Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041

    Email
    [email protected]

    Mobile
    +91 9607365656 #APAC Wood Chips Market, Japan Biomass Feed-in-Tariff, Asia Pacific Renewable Energy, Wood Pulp Export Asia, Biomass Imports APAC, Forest Biomass Supply Chain, Sustainable Energy Asia
    Stellar Market Research has released a comprehensive intelligence study on the Wood Chips Market, revealing that the industry is undergoing a structural evolution driven by global decarbonization mandates and renewable energy transitions. Valued at USD 12.11 Billion in 2025, the market is projected to reach USD 23.60 Billion by 2032, expanding at a remarkable compound annual growth rate (CAGR) of 10% during the forecast period. The report underscores the strategic importance of wood chips as a versatile biomass feedstock critical for meeting international climate targets while ensuring reliable industrial and residential heat generation. The global energy matrix is undergoing a profound paradigm shift, moving decisively away from fossil fuel reliance toward decentralized renewable alternatives. Within this transformation, the wood chips market has emerged as a linchpin for circular bioeconomy initiatives. Driven by tightening carbon emission policies and the necessity for secure, localized heat and power sources, commercial enterprises and municipal utilities are actively restructuring their fuel supply chains. Key Findings from the Report Market Valuation & Trajectory: The global Wood Chips Market reached USD 12.11 Billion in 2025 and is projected to expand to USD 23.60 Billion by 2032 at a 10% CAGR. Dominant Product Segment: The Softwood segment commanded the largest market share at 46% in 2025, primarily driven by widespread utilization in garden mulching, playground surfacing, and high-volume industrial applications. Leading Application Category: Residential Heating dominated application channels with a 38% market share in 2025, supported by widespread global adoption of eco-friendly home heating solutions. Regional Dominance: The Asia-Pacific region captured a leading 39% market share in 2025, heavily reinforced by government feed-in-tariff subsidy schemes and expanding biomass project pipelines in countries like Japan. High-Growth Regional Frontier: Europe is forecast to register steady, high-value growth at a 9.92% CAGR over the forecast period, anchored by decentralized small-scale combined heat and power (CHP) installations. Pulp & Paper Integration: The increasing demand for wood chips as a primary raw material in pulp mills continues to provide a stable industrial baseline for continuous market expansion. Investment & Diversification Potential: Emerging interest in advanced applications—such as utilizing nanocrystalline cellulose (NCC) extracted from wood pulp for next-generation flexible electronics—is unlocking new commercial horizons for market stakeholders. For further information, click the following link:https://www.stellarmr.com/report/req_sample/Wood-Chips-Market/485 Market Drivers and Restraints Driver 1: Accelerated Transition to Renewable Biomass Energy: Escalating depletion of conventional fossil fuels and stringent international climate protocols are compelling governments and utility providers to scale up biomass solid fuel utilization. Driver 2: Surging Demand from the Pulp and Paper Sector: Continuous capacity expansions across global pulp mills require reliable, high-grade wood chip inputs to satisfy paper, packaging, and derivative product manufacturing needs. Driver 3: Proliferation of Eco-Friendly Landscaping and Composting: Rising consumer and municipal preference for organic soil amendments, playground safety surfacing, and sustainable garden mulch acts as a consistent secondary growth catalyst. Restraint 1: Intense Competition from Alternative Biofuels: The growing popularity and commercial scaling of wood pellets as an alternative dense fuel pose a competitive threat, particularly in commercial power generation segments. Restraint 2: Strict GHG Emissions Compliance and Certification Hurdles: Regulatory burdens regarding greenhouse gas emissions standards and the high cost of acquiring sustainability-related forestry certifications can impede rapid supply chain scaling. Technology, Regulation, and Sustainability Trends The industry is experiencing profound operational transformation through the adoption of advanced digital log loaders, automated de-wrapping stations, and precision chipping technology designed to minimize waste and optimize fiber recovery. Regulatory frameworks are increasingly prioritizing carbon accountability; policy instruments such as carbon pricing and strict sustainability compliance require market players to maintain transparent, traceable sourcing operations. Simultaneously, ESG (Environmental, Social, and Governance) imperatives are accelerating reforestation partnerships and waste-to-energy circularity, ensuring that wood chip harvesting actively balances ecological restoration with commercial output. Regional Insights Asia-Pacific: Securing a commanding 39% market share in 2025, Asia-Pacific represents the epicenter of global consumption. Japan continues to spearhead regional expansion by leveraging robust Feed-in-Tariff (FiT) subsidy mechanisms to construct extensive biomass energy generation pipelines, while major developing economies scale up domestic pulp production infrastructure. Europe: Europe is poised to record a stellar 9.92% CAGR through the forecast period. The region's growth is anchored by established small-scale (sub-20MW) combined heat and power (CHP) infrastructure that predominantly utilizes locally sourced wood, satisfying rigorous EU renewable energy directives. North America: Supported by well-established commercial forestry networks in the United States and Canada, North America remains a highly consolidated market focused on supply chain optimization, advanced wood processing technology, and export efficiency. Recent Industry Developments River City Fibre LP (2025): Deployed a USD 600,000 modernization investment backed by local public-private funding to integrate an electric log loader and de-wrapping station in Kamloops, boosting low-value pulp log processing efficiency while cutting operational emissions. Eternali (2024): Expanded its Brazilian operational footprint by acquiring 3.3 hectares of land in Moju, Pará, to construct a dedicated wood chip production facility designed to feed regional biomass energy demands using locally sourced sawmill residues. Ørsted A/S (2024): Announced strategic plans to expand its European biomass power generation portfolio, driving substantial long-term demand commitments for sustainable wood chip fuel supplies. Great Northern Timber (2024): Partnered with local ecological conservation groups to initiate structured reforestation projects in harvested timber tracts, establishing a verifiable precedent for balancing commercial wood chip harvesting with active ecosystem restoration. Drax Group (2024): Committed a USD 300 million capital investment toward the construction of advanced biomass power generation and renewable energy infrastructure in Scotland, driving long-term market demand for sustainably certified wood chips. Competitive Landscape The global wood chips market exhibits a semi-consolidated competitive structure characterized by the active participation of major forestry conglomerates, specialized biomass processors, and regional market players. Leading industry participants are actively pursuing strategic supply chain integration, technological modernization, and long-term municipal procurement partnerships. Key companies profiled in the market intelligence landscape include Enviva Inc., Drax Group, Weyerhaeuser Company, West Fraser Timber Co. Ltd., International Paper Company, St. Boniface Pallet Company Ltd., EVOWORLD GmbH, and American Wood Resources. Major players are increasingly emphasizing certified sustainable forestry practices and processing efficiency to capture high-margin supply agreements across European and Asian energy corridors. Analyst Commentary "The wood chips market has transitioned far beyond a conventional forestry byproduct sector into an essential pillar of the global bio-energy and bio-materials economy," said a Senior Research Analyst at Stellar Market Research. "As corporate sustainability mandates and government decarbonization targets tighten through 2032, market participants that invest in supply chain traceability, advanced fiber processing efficiency, and localized sourcing networks will capture outsized value. The ability to guarantee compliant, low-carbon biomass feedstocks will ultimately separate market leaders from legacy followers." Future Outlook Looking ahead through the 2026–2032 forecast horizon, the wood chips market is expected to experience sustained, high-value expansion. Demand dynamics will increasingly pivot toward high-efficiency combined heat and power (CHP) applications and innovative high-tech bio-refining avenues, such as nanocrystalline cellulose production. While regulatory frameworks and carbon accounting standards will grow more stringent, they will simultaneously reward forward-thinking operators who embrace certified sustainable forestry. Supported by robust infrastructure investments across Asia-Pacific and Europe, the market is well-positioned to cement its role as a cornerstone of the global green energy transition. For further information, click the following link:https://www.stellarmr.com/report/req_sample/Wood-Chips-Market/485  About Stellar Market Research Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Address Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041 Email [email protected] Mobile +91 9607365656 #APAC Wood Chips Market, Japan Biomass Feed-in-Tariff, Asia Pacific Renewable Energy, Wood Pulp Export Asia, Biomass Imports APAC, Forest Biomass Supply Chain, Sustainable Energy Asia
    0 Comments ·0 Shares ·495 Views
  • India’s curing agent industry is growing with rising demand from construction, infrastructure, electronics, renewable energy, and industrial manufacturing. According to Markntel Advisors, the industry is projected to reach USD 778 million by 2032, registering a CAGR of 11.49%. Discover key industry trends, emerging applications, and growth opportunities.

    Explore the Full Report: https://www.marknteladvisors.com/research-library/india-curing-agent-market-report.html
    India’s curing agent industry is growing with rising demand from construction, infrastructure, electronics, renewable energy, and industrial manufacturing. According to Markntel Advisors, the industry is projected to reach USD 778 million by 2032, registering a CAGR of 11.49%. Discover key industry trends, emerging applications, and growth opportunities. Explore the Full Report: https://www.marknteladvisors.com/research-library/india-curing-agent-market-report.html
    India Curing Agent Market Trends, Growth & Share Study
    www.marknteladvisors.com
    India Curing Agent Market growth remains strong as amine-based chemistry captures around 47% share while industrial applications continue expanding.
    0 Comments ·0 Shares ·342 Views
  • Dry Type Transformer Market Growth Drivers, Demand, and Future Opportunities Report by MMR

    Dry Type Transformer Market to Reach US$ 13.21 Billion by 2034, Driven by Grid Modernization and Rising Electricity Demand

    The Dry Type Transformer Market is witnessing steady growth as industries, utilities, commercial buildings, and renewable energy projects increasingly require reliable, energy-efficient, and safer electrical distribution systems. According to Maximize Market Research, the market was valued at US$ 7.75 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.1% from 2026 to 2034, reaching nearly US$ 13.21 billion by 2034.

    Dry type transformers use air or solid insulation systems instead of liquid insulating oil, making them suitable for indoor installations and locations where fire safety, reduced maintenance, and environmental considerations are important. Increasing electricity consumption, expanding data center infrastructure, electrification of industrial processes, and investments in modern power grids are supporting demand for these transformers worldwide.

    Market Estimation, Growth Drivers, and Opportunities

    The market is expected to expand significantly during the forecast period as electricity networks adapt to changing consumption patterns and the integration of renewable energy sources. Aging electrical infrastructure in developed economies requires upgrades, while emerging economies are investing in industrial facilities, commercial developments, transportation infrastructure, and new power distribution networks.

    Key growth drivers include the increasing adoption of renewable energy, rising demand for dependable electricity distribution, and stricter requirements for electrical safety in buildings and industrial facilities. Dry type transformers eliminate the need for liquid dielectric insulation, reducing the risk of oil leakage and associated environmental contamination. Their suitability for hospitals, airports, commercial complexes, underground installations, manufacturing plants, and data centers further strengthens their market position.

    Get a Sample Insight Report Now : https://www.maximizemarketresearch.com/request-sample/11250/

    U.S. Market Trends and Investment Outlook

    The United States represents an important growth market as utilities, technology companies, and industrial operators invest in electricity infrastructure to support increasing power requirements. In 2025, growing attention to data center construction, artificial intelligence infrastructure, domestic manufacturing, and grid resilience reinforced the need for dependable electrical equipment. Transformer demand is also being influenced by renewable energy installations, electrification projects, and the replacement of aging distribution assets. Federal initiatives supporting domestic manufacturing and energy infrastructure, alongside utility investments in transmission and distribution networks, provide a favorable environment for transformer suppliers. In addition, energy-efficiency requirements and fire-safety considerations are encouraging buyers to evaluate dry type transformer solutions for suitable indoor and commercial applications. Supply-chain localization, production capacity expansion, and technological improvements remain important investment priorities for manufacturers seeking to meet long-term U.S. electricity demand.

    Dry Type Transformer Market Growth Drivers, Demand, and Future Opportunities Report by MMR Dry Type Transformer Market to Reach US$ 13.21 Billion by 2034, Driven by Grid Modernization and Rising Electricity Demand The Dry Type Transformer Market is witnessing steady growth as industries, utilities, commercial buildings, and renewable energy projects increasingly require reliable, energy-efficient, and safer electrical distribution systems. According to Maximize Market Research, the market was valued at US$ 7.75 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.1% from 2026 to 2034, reaching nearly US$ 13.21 billion by 2034. Dry type transformers use air or solid insulation systems instead of liquid insulating oil, making them suitable for indoor installations and locations where fire safety, reduced maintenance, and environmental considerations are important. Increasing electricity consumption, expanding data center infrastructure, electrification of industrial processes, and investments in modern power grids are supporting demand for these transformers worldwide. Market Estimation, Growth Drivers, and Opportunities The market is expected to expand significantly during the forecast period as electricity networks adapt to changing consumption patterns and the integration of renewable energy sources. Aging electrical infrastructure in developed economies requires upgrades, while emerging economies are investing in industrial facilities, commercial developments, transportation infrastructure, and new power distribution networks. Key growth drivers include the increasing adoption of renewable energy, rising demand for dependable electricity distribution, and stricter requirements for electrical safety in buildings and industrial facilities. Dry type transformers eliminate the need for liquid dielectric insulation, reducing the risk of oil leakage and associated environmental contamination. Their suitability for hospitals, airports, commercial complexes, underground installations, manufacturing plants, and data centers further strengthens their market position. Get a Sample Insight Report Now : https://www.maximizemarketresearch.com/request-sample/11250/ U.S. Market Trends and Investment Outlook The United States represents an important growth market as utilities, technology companies, and industrial operators invest in electricity infrastructure to support increasing power requirements. In 2025, growing attention to data center construction, artificial intelligence infrastructure, domestic manufacturing, and grid resilience reinforced the need for dependable electrical equipment. Transformer demand is also being influenced by renewable energy installations, electrification projects, and the replacement of aging distribution assets. Federal initiatives supporting domestic manufacturing and energy infrastructure, alongside utility investments in transmission and distribution networks, provide a favorable environment for transformer suppliers. In addition, energy-efficiency requirements and fire-safety considerations are encouraging buyers to evaluate dry type transformer solutions for suitable indoor and commercial applications. Supply-chain localization, production capacity expansion, and technological improvements remain important investment priorities for manufacturers seeking to meet long-term U.S. electricity demand.
    0 Comments ·0 Shares ·391 Views
More Results