• Urea Market Demand and Growth Outlook Across Key Applications

    Urea Market Poised for Expansion as Food Security, Industrial Demand and Low-Carbon Fertilizer Investments Reshape Global Industry

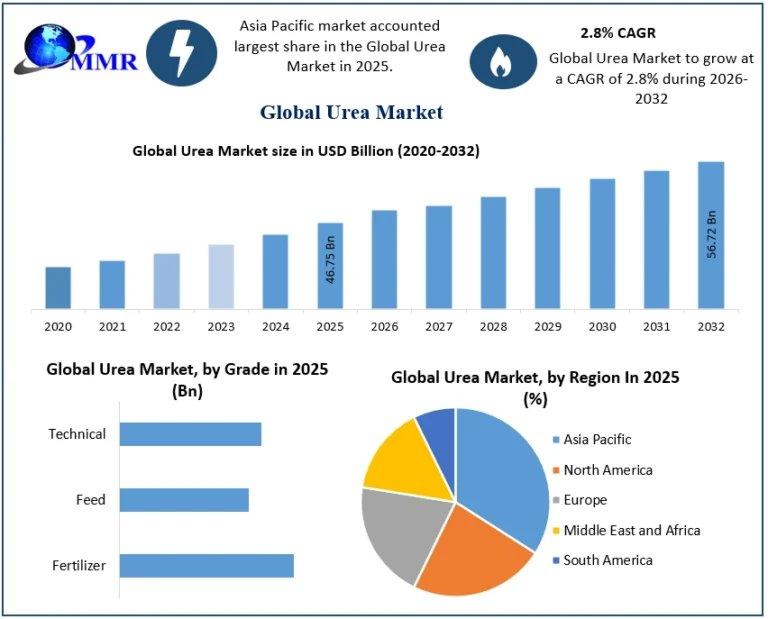
    The Urea Market is entering a period of expansion as food requirements, agricultural productivity and cleaner nitrogen investments strengthen demand. According to Maximize Market Research, the Urea Market was valued at USD 46.75 billion in 2025 and is projected to grow at a CAGR of 2.8% from 2026 to 2032, reaching nearly USD 56.72 billion by 2032. Urea remains vital because it contains approximately 46% nitrogen and is cost-effective for crop yields. Food-security priorities and shrinking arable land are supporting fertilizer consumption across agricultural economies.

    Beyond agriculture, urea demand is supported by chemical manufacturing, resins, plastics, animal nutrition and diesel exhaust fluid. Precision farming, green ammonia and carbon capture are creating opportunities for more efficient and lower-carbon fertilizer production.

    United States Market: 2025 Trends and Investment

    The U.S. urea market benefited from resilient nitrogen demand in 2025, supported by favorable corn economics and expectations for higher corn acreage. CF Industries reported strong North American nitrogen demand during the 2025 spring application season, while its outlook pointed to continued positive global nitrogen demand and constrained supply. In April 2025, CF Industries formed a joint venture with JERA and Mitsui to develop a low-carbon ammonia facility at its Blue Point Complex in Louisiana, incorporating carbon capture infrastructure. The project illustrates the U.S. shift toward lower-carbon nitrogen production. The USDA highlighted that global supply conditions make domestic capacity and supply-chain resilience investment priorities.

    Download a Free Sample of the Market Report : https://www.maximizemarketresearch.com/request-sample/26788/

    Market Segmentation: Largest-Share Segment

    By grade, agricultural-grade urea holds the largest share of the market. Its dominance reflects broad crop use, high nitrogen concentration and affordability. By application, fertilizers account for the largest market share because urea is widely used as a nitrogen fertilizer for improving crop productivity. Strong agricultural demand and food-security programs should preserve its leadership.

    Competitive Analysis

    Nutrien is a major nitrogen fertilizer producer with an extensive agricultural retail network. In 2025, the company increased nitrogen operating rates at North American facilities and allocated approximately USD 400–500 million of investing capital toward proprietary products, network optimization, digital capabilities and low-cost nitrogen expansions. Nutrien also agreed to sell its Profertil stake for about USD 600 million, supporting targeted growth, debt reduction and shareholder returns.

    CF Industries is a leading global ammonia and nitrogen producer with strong U.S. manufacturing capabilities. In 2025, the company planned approximately USD 500–550 million in capital spending and advanced its Blue Point low-carbon ammonia joint venture with JERA and Mitsui. The project could support lower-carbon nitrogen production.

    Yara International is pursuing sustainable fertilizer and ammonia opportunities. In December 2025, Yara and Air Products entered advanced negotiations to partner on low-emission ammonia projects in the United States and Saudi Arabia. The strategy supports supply diversification and lower-carbon fertilizer production.
    Urea Market Demand and Growth Outlook Across Key Applications Urea Market Poised for Expansion as Food Security, Industrial Demand and Low-Carbon Fertilizer Investments Reshape Global Industry The Urea Market is entering a period of expansion as food requirements, agricultural productivity and cleaner nitrogen investments strengthen demand. According to Maximize Market Research, the Urea Market was valued at USD 46.75 billion in 2025 and is projected to grow at a CAGR of 2.8% from 2026 to 2032, reaching nearly USD 56.72 billion by 2032. Urea remains vital because it contains approximately 46% nitrogen and is cost-effective for crop yields. Food-security priorities and shrinking arable land are supporting fertilizer consumption across agricultural economies. Beyond agriculture, urea demand is supported by chemical manufacturing, resins, plastics, animal nutrition and diesel exhaust fluid. Precision farming, green ammonia and carbon capture are creating opportunities for more efficient and lower-carbon fertilizer production. United States Market: 2025 Trends and Investment The U.S. urea market benefited from resilient nitrogen demand in 2025, supported by favorable corn economics and expectations for higher corn acreage. CF Industries reported strong North American nitrogen demand during the 2025 spring application season, while its outlook pointed to continued positive global nitrogen demand and constrained supply. In April 2025, CF Industries formed a joint venture with JERA and Mitsui to develop a low-carbon ammonia facility at its Blue Point Complex in Louisiana, incorporating carbon capture infrastructure. The project illustrates the U.S. shift toward lower-carbon nitrogen production. The USDA highlighted that global supply conditions make domestic capacity and supply-chain resilience investment priorities. Download a Free Sample of the Market Report : https://www.maximizemarketresearch.com/request-sample/26788/ Market Segmentation: Largest-Share Segment By grade, agricultural-grade urea holds the largest share of the market. Its dominance reflects broad crop use, high nitrogen concentration and affordability. By application, fertilizers account for the largest market share because urea is widely used as a nitrogen fertilizer for improving crop productivity. Strong agricultural demand and food-security programs should preserve its leadership. Competitive Analysis Nutrien is a major nitrogen fertilizer producer with an extensive agricultural retail network. In 2025, the company increased nitrogen operating rates at North American facilities and allocated approximately USD 400–500 million of investing capital toward proprietary products, network optimization, digital capabilities and low-cost nitrogen expansions. Nutrien also agreed to sell its Profertil stake for about USD 600 million, supporting targeted growth, debt reduction and shareholder returns. CF Industries is a leading global ammonia and nitrogen producer with strong U.S. manufacturing capabilities. In 2025, the company planned approximately USD 500–550 million in capital spending and advanced its Blue Point low-carbon ammonia joint venture with JERA and Mitsui. The project could support lower-carbon nitrogen production. Yara International is pursuing sustainable fertilizer and ammonia opportunities. In December 2025, Yara and Air Products entered advanced negotiations to partner on low-emission ammonia projects in the United States and Saudi Arabia. The strategy supports supply diversification and lower-carbon fertilizer production.
    0 Comments ·0 Shares ·485 Views
  • Rendered Products Industry Growth, Market Trends and Future Opportunities

    Key Highlights

    The Rendered Products Market was valued at USD 23.61 billion in 2025, creating a substantial base for continued industry activity.
    The market is projected to reach USD 29.31 billion by 2034, indicating sustained demand across multiple applications.
    A CAGR of 2.43% is projected during 2026–2034, pointing to steady rather than abrupt expansion.
    Tallow held the largest product-type share in 2025, supported by broad food, feed, soap, candle, and lubricant applications.
    North America led the market and is expected to maintain a significant position during the forecast period.


    Market Overview

    The Rendered Products Market is built around the processing of animal by-products through heating and separation to recover useful fats, proteins, and other materials. Tallow, grease, protein meal, bone meal, feather meal, and blood meal can serve different commercial purposes, helping industries reduce waste while recovering economic value.

    The market reached USD 23.61 billion in 2025, demonstrating the scale of demand for recovered animal-derived materials. Its projected rise to USD 29.31 billion by 2034 signals an expanding opportunity for processors that can combine efficient production with consistent quality and regulatory compliance.

    Get a Sample Insight Report Now : https://www.maximizemarketresearch.com/request-sample/221538/

    Key Trends Driving Growth

    One major trend is the expanding use of rendered materials in animal nutrition. Protein-rich meals support livestock, poultry, aquaculture, and companion-animal feed applications, creating diversified demand.

    Another important trend is technological modernization. Continuous rendering systems, improved grinding, low-temperature separation, and waste-heat recovery are helping facilities improve cooking efficiency, energy performance, and product quality.

    Sustainability is also strengthening the market's relevance. Converting animal by-products into feed ingredients, fertilizers, biofuels, and industrial materials supports resource conservation and creates additional value streams for processors.

    Rendered Products Industry Growth, Market Trends and Future Opportunities Key Highlights The Rendered Products Market was valued at USD 23.61 billion in 2025, creating a substantial base for continued industry activity. The market is projected to reach USD 29.31 billion by 2034, indicating sustained demand across multiple applications. A CAGR of 2.43% is projected during 2026–2034, pointing to steady rather than abrupt expansion. Tallow held the largest product-type share in 2025, supported by broad food, feed, soap, candle, and lubricant applications. North America led the market and is expected to maintain a significant position during the forecast period. Market Overview The Rendered Products Market is built around the processing of animal by-products through heating and separation to recover useful fats, proteins, and other materials. Tallow, grease, protein meal, bone meal, feather meal, and blood meal can serve different commercial purposes, helping industries reduce waste while recovering economic value. The market reached USD 23.61 billion in 2025, demonstrating the scale of demand for recovered animal-derived materials. Its projected rise to USD 29.31 billion by 2034 signals an expanding opportunity for processors that can combine efficient production with consistent quality and regulatory compliance. Get a Sample Insight Report Now : https://www.maximizemarketresearch.com/request-sample/221538/ Key Trends Driving Growth One major trend is the expanding use of rendered materials in animal nutrition. Protein-rich meals support livestock, poultry, aquaculture, and companion-animal feed applications, creating diversified demand. Another important trend is technological modernization. Continuous rendering systems, improved grinding, low-temperature separation, and waste-heat recovery are helping facilities improve cooking efficiency, energy performance, and product quality. Sustainability is also strengthening the market's relevance. Converting animal by-products into feed ingredients, fertilizers, biofuels, and industrial materials supports resource conservation and creates additional value streams for processors.
    0 Comments ·0 Shares ·512 Views
  • Asia Pacific Biochar Market Growth, Trends, Opportunities and Forecast 2023–2029
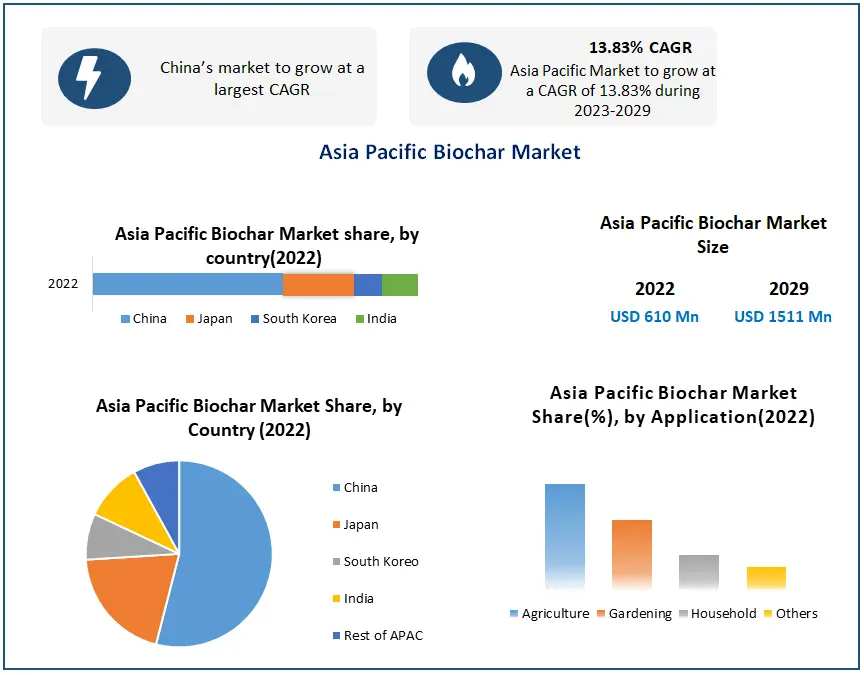
    The Asia Pacific Biochar Market was valued at USD 610 million in 2022 and is projected to grow at a CAGR of 13.83% from 2023 to 2029, reaching approximately USD 1,511 million by 2029. The market is gaining momentum as agriculture, waste management, and sustainable farming practices increasingly adopt biochar as an environmentally beneficial material.

    Asia Pacific Biochar Market Overview
    Biochar is increasingly being recognized across the Asia Pacific region for its applications in agriculture, gardening, waste management, and other end-use sectors. Strong environmental regulations, growing demand from end-user industries, increasing organic farming, and the use of biochar in waste management are among the major factors supporting market expansion.

    The agriculture sector represents a major area of demand for biochar. The material can be produced from different forms of biomass and agricultural waste, providing an opportunity to convert waste into a value-added resource. Pyrolysis remains one of the leading production methods and accounts for a significant share of the market.

    Request Free Sample Copy:https://www.maximizemarketresearch.com/request-sample/20189/

    Key Growth Drivers
    Rising Demand for Organic Farming
    The increasing adoption of organic farming and sustainable agricultural practices is creating significant demand for biochar. Farmers and agricultural businesses are increasingly exploring solutions that can support soil health while reducing dependence on conventional chemical fertilizers.

    Biochar also provides an opportunity to utilize agricultural and organic waste that would otherwise require disposal. Crop residues, biomass, and animal manure can be converted into biochar, creating an additional value stream from agricultural waste.

    Growing Importance of Waste Management
    The Asia Pacific region generates substantial quantities of agricultural and organic waste. Biochar production offers a method of converting some of these waste materials into useful products while reducing waste volumes.

    The combination of waste management and biochar production is therefore becoming increasingly relevant to governments, agricultural businesses, and sustainability-focused organizations.

    Environmental Regulations
    Stricter environmental regulations are also supporting market development. Governments and industries are looking for alternatives that can contribute to sustainable resource management and reduce environmental impacts.

    Market Restraints
    High Initial Investment
    The establishment of biochar production facilities and implementation of associated technologies can require significant upfront investment. High initial costs may discourage new entrants and investors, particularly in areas where financial resources and production infrastructure are limited.

    Lack of Awareness
    Limited awareness among farmers and consumers regarding the benefits and applications of biochar remains another challenge. Greater education and stakeholder awareness are needed to accelerate adoption across developing markets in the region.

    Market Opportunities
    Sustainable Agriculture
    Increasing awareness of sustainable agriculture presents an important opportunity for the Asia Pacific Biochar Market. Biochar can be incorporated into agricultural practices aimed at improving soil health and reducing dependence on chemical fertilizers.

    Growing consumer interest in environmentally friendly agricultural products may further encourage farmers to explore biochar-based solutions.

    Integration with Waste-to-Energy
    The region's large volume of agricultural and organic waste provides an opportunity to integrate biochar production with bioenergy and waste-to-energy processes. Such integration can enable the utilization of waste resources while creating value-added products.

    Government subsidies, incentives, and favorable regulations could further encourage investment in biochar production and sustainable agricultural practices.

    Asia Pacific Biochar Market Segmentation
    The market is segmented based on application, technology, manufacturing, and feedstock. Agriculture is a major application segment, while pyrolysis represents an important manufacturing process.

    By Technology
    Pyrolysis has dominated the market and is expected to maintain its leading position during the forecast period. It is a widely used thermochemical process in which biomass is heated in the absence of oxygen to produce biochar, bio-oil, and syngas.

    Gasification is another production method. In this process, biomass is oxidized to generate syngas, which can subsequently be processed to produce biochar.

    By Feedstock
    The Agricultural Waste segment holds a significant market share and is expected to remain dominant. Common agricultural feedstocks include rice straw, wheat straw, corn stalks, nutshells, and other biomass residues.

    Animal manure, including cow dung, swine dung, and poultry litter, is also used as a feedstock for biochar production.

    By Application
    The market covers:

    Agriculture
    Gardening
    Household
    Others
    By Manufacturing
    Gasification
    Pyrolysis
    Others
    By Feedstock
    Woody Biomass
    Agricultural Waste
    Animal Manure
    Others
    Request Free Sample Copy:https://www.maximizemarketresearch.com/request-sample/20189/

    Country Analysis
    China is the leading country in the Asia Pacific Biochar Market, accounting for approximately 95% of the regional market in 2022, according to the provided source. Chinese players are investing in research and development to understand biochar's effects on soil processes, agricultural productivity, and environmental conditions.

    Japan is also active in biochar research, particularly in understanding its physical, chemical, and biological properties and its effects on soil and compost. The broader Asia Pacific region is expected to experience strong growth, supported by pilot projects and increasing consumer adoption.

    The countries covered include China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan, and Rest of APAC.

    Asia Pacific Biochar Market Forecast
    Market Indicator Details
    Base Year 2022
    Historical Period 2018–2022
    Forecast Period 2023–2029
    Market Size in 2022 USD 610 Million
    CAGR 13.83%
    Market Size in 2029 USD 1,511 Million
    Key Application Agriculture
    Leading Manufacturing Process Pyrolysis
    Key Feedstock Agricultural Waste
    The market is expected to benefit from rising demand for sustainable agriculture, increasing organic waste generation, environmental regulations, and the growing integration of biochar with waste management and bioenergy systems.

    Competitive Landscape
    The Asia Pacific Biochar Market includes established companies and emerging participants involved in biochar production, pyrolysis technologies, biomass utilization, and sustainable resource management.

    Key players identified in the source include Biogreen-Energy, Agri-Tech Producers LLC, Genesis Industries, Diacarbon Energy Inc., Green Charcoal International, Vega Biofuels Inc., The Biochar Company, Cool Planet Energy Systems Inc., Full Circle Biochar, Pacific Pyrolysis Pty Ltd, ARSTA Eco, Earth Systems, Guangdong Dazhong Agricultural Science and Technology Co. Ltd, Rainbow Bee Eater and Pacific Pyrolysis, Biochar Now LLC, Tolero Energy, Airex Energy, Carbon Gold, Phoenix Energy, and AirTerra.

    Future Outlook
    The Asia Pacific Biochar Market has considerable growth potential as the region moves toward more sustainable agricultural and waste-management practices. Increasing awareness of soil health, organic farming, agricultural waste utilization, and environmentally responsible production is expected to support adoption.

    At the same time, reducing production costs, improving infrastructure, increasing stakeholder awareness, and introducing supportive government policies will be important for overcoming current market barriers.

    Overall, the market's projected growth from USD 610 million in 2022 to USD 1,511 million by 2029 highlights the expanding role of biochar in sustainable agriculture and resource management across Asia Pacific.
    Asia Pacific Biochar Market Growth, Trends, Opportunities and Forecast 2023–2029 The Asia Pacific Biochar Market was valued at USD 610 million in 2022 and is projected to grow at a CAGR of 13.83% from 2023 to 2029, reaching approximately USD 1,511 million by 2029. The market is gaining momentum as agriculture, waste management, and sustainable farming practices increasingly adopt biochar as an environmentally beneficial material. Asia Pacific Biochar Market Overview Biochar is increasingly being recognized across the Asia Pacific region for its applications in agriculture, gardening, waste management, and other end-use sectors. Strong environmental regulations, growing demand from end-user industries, increasing organic farming, and the use of biochar in waste management are among the major factors supporting market expansion. The agriculture sector represents a major area of demand for biochar. The material can be produced from different forms of biomass and agricultural waste, providing an opportunity to convert waste into a value-added resource. Pyrolysis remains one of the leading production methods and accounts for a significant share of the market. Request Free Sample Copy:https://www.maximizemarketresearch.com/request-sample/20189/ Key Growth Drivers Rising Demand for Organic Farming The increasing adoption of organic farming and sustainable agricultural practices is creating significant demand for biochar. Farmers and agricultural businesses are increasingly exploring solutions that can support soil health while reducing dependence on conventional chemical fertilizers. Biochar also provides an opportunity to utilize agricultural and organic waste that would otherwise require disposal. Crop residues, biomass, and animal manure can be converted into biochar, creating an additional value stream from agricultural waste. Growing Importance of Waste Management The Asia Pacific region generates substantial quantities of agricultural and organic waste. Biochar production offers a method of converting some of these waste materials into useful products while reducing waste volumes. The combination of waste management and biochar production is therefore becoming increasingly relevant to governments, agricultural businesses, and sustainability-focused organizations. Environmental Regulations Stricter environmental regulations are also supporting market development. Governments and industries are looking for alternatives that can contribute to sustainable resource management and reduce environmental impacts. Market Restraints High Initial Investment The establishment of biochar production facilities and implementation of associated technologies can require significant upfront investment. High initial costs may discourage new entrants and investors, particularly in areas where financial resources and production infrastructure are limited. Lack of Awareness Limited awareness among farmers and consumers regarding the benefits and applications of biochar remains another challenge. Greater education and stakeholder awareness are needed to accelerate adoption across developing markets in the region. Market Opportunities Sustainable Agriculture Increasing awareness of sustainable agriculture presents an important opportunity for the Asia Pacific Biochar Market. Biochar can be incorporated into agricultural practices aimed at improving soil health and reducing dependence on chemical fertilizers. Growing consumer interest in environmentally friendly agricultural products may further encourage farmers to explore biochar-based solutions. Integration with Waste-to-Energy The region's large volume of agricultural and organic waste provides an opportunity to integrate biochar production with bioenergy and waste-to-energy processes. Such integration can enable the utilization of waste resources while creating value-added products. Government subsidies, incentives, and favorable regulations could further encourage investment in biochar production and sustainable agricultural practices. Asia Pacific Biochar Market Segmentation The market is segmented based on application, technology, manufacturing, and feedstock. Agriculture is a major application segment, while pyrolysis represents an important manufacturing process. By Technology Pyrolysis has dominated the market and is expected to maintain its leading position during the forecast period. It is a widely used thermochemical process in which biomass is heated in the absence of oxygen to produce biochar, bio-oil, and syngas. Gasification is another production method. In this process, biomass is oxidized to generate syngas, which can subsequently be processed to produce biochar. By Feedstock The Agricultural Waste segment holds a significant market share and is expected to remain dominant. Common agricultural feedstocks include rice straw, wheat straw, corn stalks, nutshells, and other biomass residues. Animal manure, including cow dung, swine dung, and poultry litter, is also used as a feedstock for biochar production. By Application The market covers: Agriculture Gardening Household Others By Manufacturing Gasification Pyrolysis Others By Feedstock Woody Biomass Agricultural Waste Animal Manure Others Request Free Sample Copy:https://www.maximizemarketresearch.com/request-sample/20189/ Country Analysis China is the leading country in the Asia Pacific Biochar Market, accounting for approximately 95% of the regional market in 2022, according to the provided source. Chinese players are investing in research and development to understand biochar's effects on soil processes, agricultural productivity, and environmental conditions. Japan is also active in biochar research, particularly in understanding its physical, chemical, and biological properties and its effects on soil and compost. The broader Asia Pacific region is expected to experience strong growth, supported by pilot projects and increasing consumer adoption. The countries covered include China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan, and Rest of APAC. Asia Pacific Biochar Market Forecast Market Indicator Details Base Year 2022 Historical Period 2018–2022 Forecast Period 2023–2029 Market Size in 2022 USD 610 Million CAGR 13.83% Market Size in 2029 USD 1,511 Million Key Application Agriculture Leading Manufacturing Process Pyrolysis Key Feedstock Agricultural Waste The market is expected to benefit from rising demand for sustainable agriculture, increasing organic waste generation, environmental regulations, and the growing integration of biochar with waste management and bioenergy systems. Competitive Landscape The Asia Pacific Biochar Market includes established companies and emerging participants involved in biochar production, pyrolysis technologies, biomass utilization, and sustainable resource management. Key players identified in the source include Biogreen-Energy, Agri-Tech Producers LLC, Genesis Industries, Diacarbon Energy Inc., Green Charcoal International, Vega Biofuels Inc., The Biochar Company, Cool Planet Energy Systems Inc., Full Circle Biochar, Pacific Pyrolysis Pty Ltd, ARSTA Eco, Earth Systems, Guangdong Dazhong Agricultural Science and Technology Co. Ltd, Rainbow Bee Eater and Pacific Pyrolysis, Biochar Now LLC, Tolero Energy, Airex Energy, Carbon Gold, Phoenix Energy, and AirTerra. Future Outlook The Asia Pacific Biochar Market has considerable growth potential as the region moves toward more sustainable agricultural and waste-management practices. Increasing awareness of soil health, organic farming, agricultural waste utilization, and environmentally responsible production is expected to support adoption. At the same time, reducing production costs, improving infrastructure, increasing stakeholder awareness, and introducing supportive government policies will be important for overcoming current market barriers. Overall, the market's projected growth from USD 610 million in 2022 to USD 1,511 million by 2029 highlights the expanding role of biochar in sustainable agriculture and resource management across Asia Pacific.
    0 Comments ·0 Shares ·356 Views
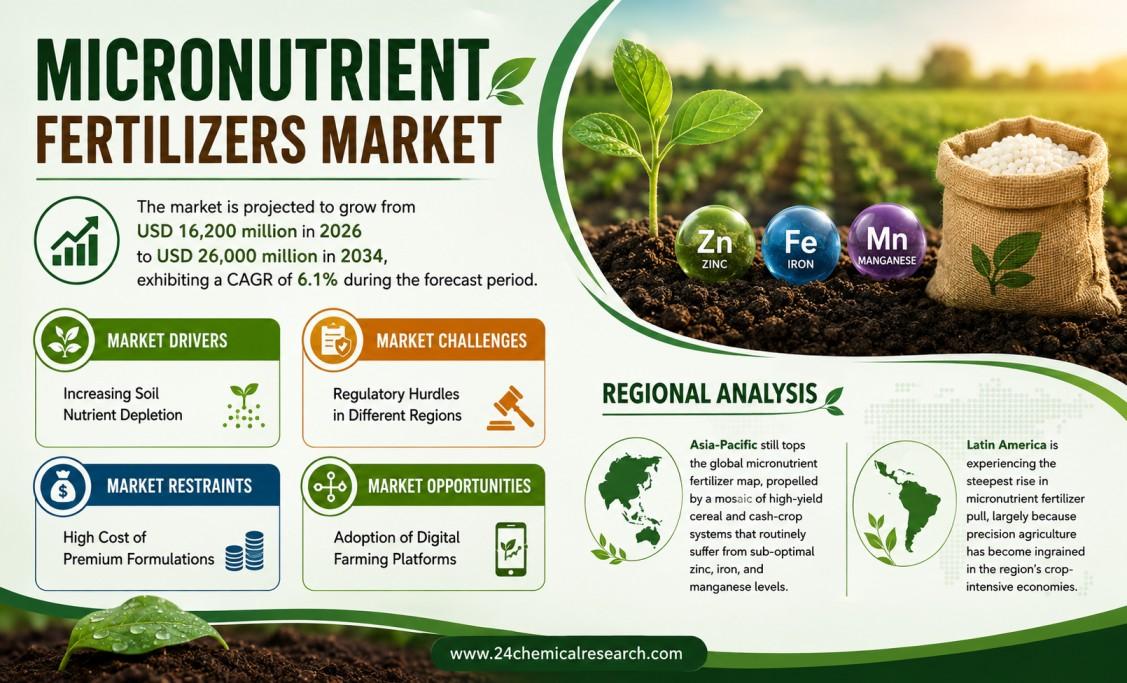
  • Global Micronutrient Fertilizers Market to reach USD 26 Billion by 2034 at 6.1% CAGR. Soil health and precision agriculture drive trace element demand.

    View full report: https://www.24chemicalresearch.com/reports/316101/micronutrient-fertilizers-market

    #MarketResearch #MicronutrientFertilizers #SoilHealth #PrecisionAgriculture #SustainableFarming
    Global Micronutrient Fertilizers Market to reach USD 26 Billion by 2034 at 6.1% CAGR. Soil health and precision agriculture drive trace element demand. View full report: https://www.24chemicalresearch.com/reports/316101/micronutrient-fertilizers-market #MarketResearch #MicronutrientFertilizers #SoilHealth #PrecisionAgriculture #SustainableFarming
    0 Comments ·0 Shares ·268 Views
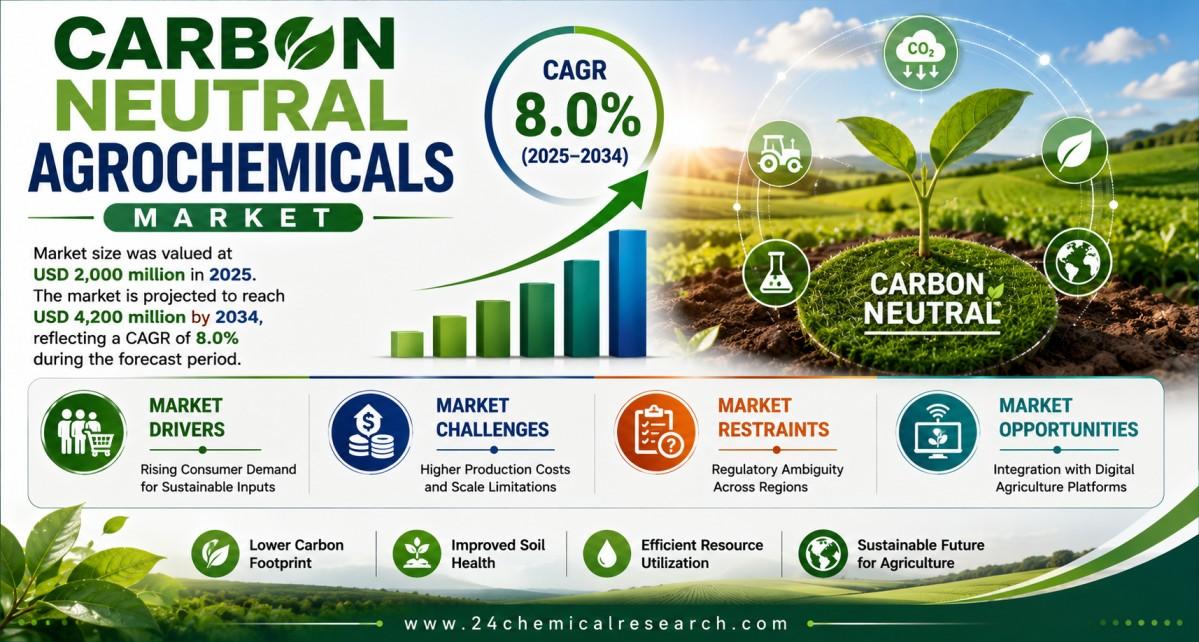
  • Global Carbon Neutral Agrochemicals Market to reach USD 4.2 Billion by 2034 at 8.0% CAGR. Sustainable farming and net-zero emissions drive green agrochemical demand.

    View full report: https://www.24chemicalresearch.com/reports/313239/carbon-neutral-agrochemicals-market

    #MarketResearch #CarbonNeutralAgrochemicals #SustainableFarming #GreenFertilizers #NetZero
    Global Carbon Neutral Agrochemicals Market to reach USD 4.2 Billion by 2034 at 8.0% CAGR. Sustainable farming and net-zero emissions drive green agrochemical demand. View full report: https://www.24chemicalresearch.com/reports/313239/carbon-neutral-agrochemicals-market #MarketResearch #CarbonNeutralAgrochemicals #SustainableFarming #GreenFertilizers #NetZero
    0 Comments ·0 Shares ·318 Views
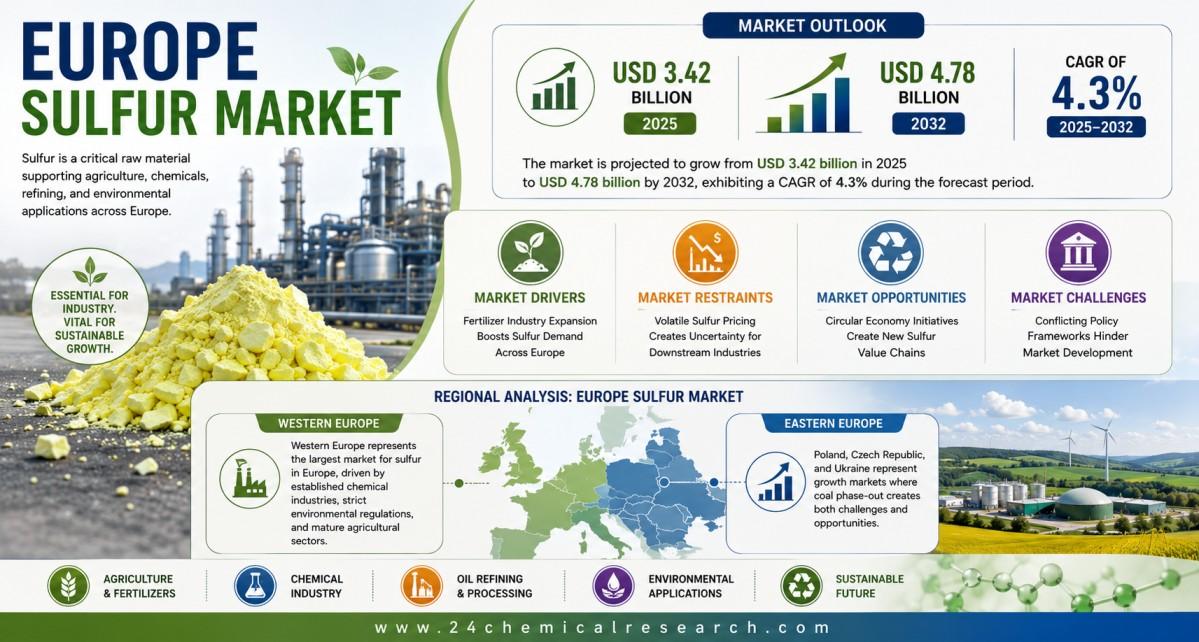
  • Europe Sulfur Market to reach USD 4.78 Billion by 2032 at 4.3% CAGR. Fertilizer demand and chemical processing drive sulfur consumption.

    View full report: https://www.24chemicalresearch.com/reports/281988/global-europe-sulfur-market

    #MarketResearch #SulfurMarket #EuropeChemicals #Fertilizers #ChemicalIndustry
    Europe Sulfur Market to reach USD 4.78 Billion by 2032 at 4.3% CAGR. Fertilizer demand and chemical processing drive sulfur consumption. View full report: https://www.24chemicalresearch.com/reports/281988/global-europe-sulfur-market #MarketResearch #SulfurMarket #EuropeChemicals #Fertilizers #ChemicalIndustry
    0 Comments ·0 Shares ·197 Views
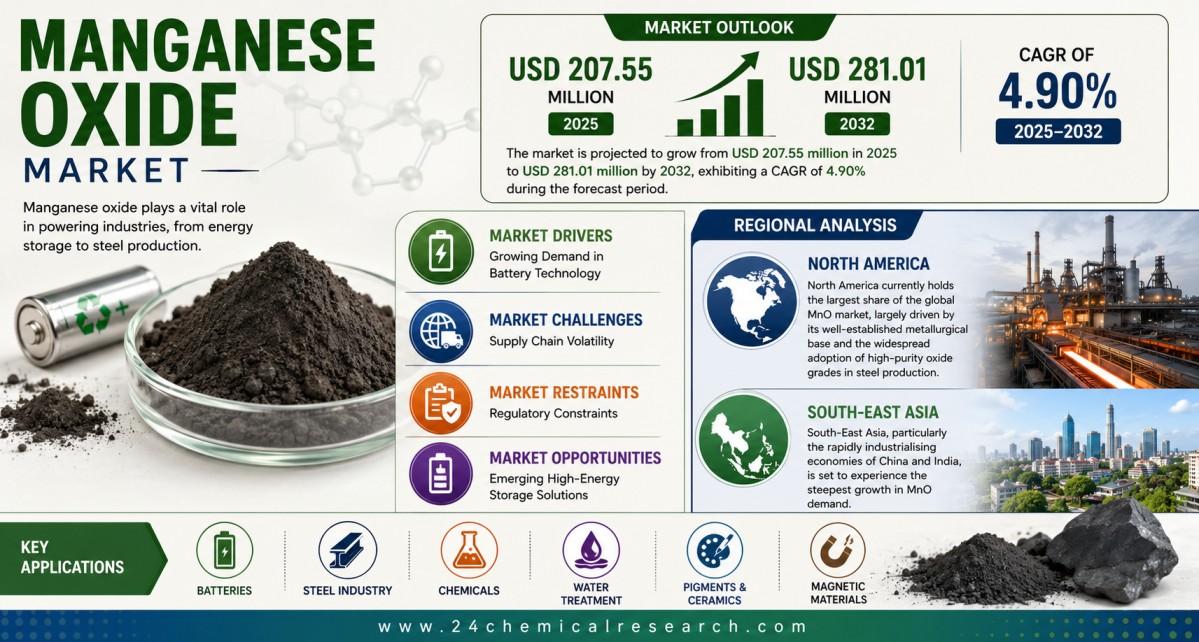
  • The Global Manganese Oxide (MnO) Market is projected to reach USD 281.01 Million by 2032, growing at a 4.90% CAGR, driven by battery manufacturing, fertilizers, and chemical applications.

    Full Report: https://www.24chemicalresearch.com/reports/283749/global-regional-manganese-oxide-forecast-supply-dem-analysis-competitive-market

    #ManganeseOxide,#MnO,#BatteryMaterials,#Agriculture,#Chemicals,#MarketResearch
    The Global Manganese Oxide (MnO) Market is projected to reach USD 281.01 Million by 2032, growing at a 4.90% CAGR, driven by battery manufacturing, fertilizers, and chemical applications. Full Report: https://www.24chemicalresearch.com/reports/283749/global-regional-manganese-oxide-forecast-supply-dem-analysis-competitive-market #ManganeseOxide,#MnO,#BatteryMaterials,#Agriculture,#Chemicals,#MarketResearch
    0 Comments ·0 Shares ·206 Views
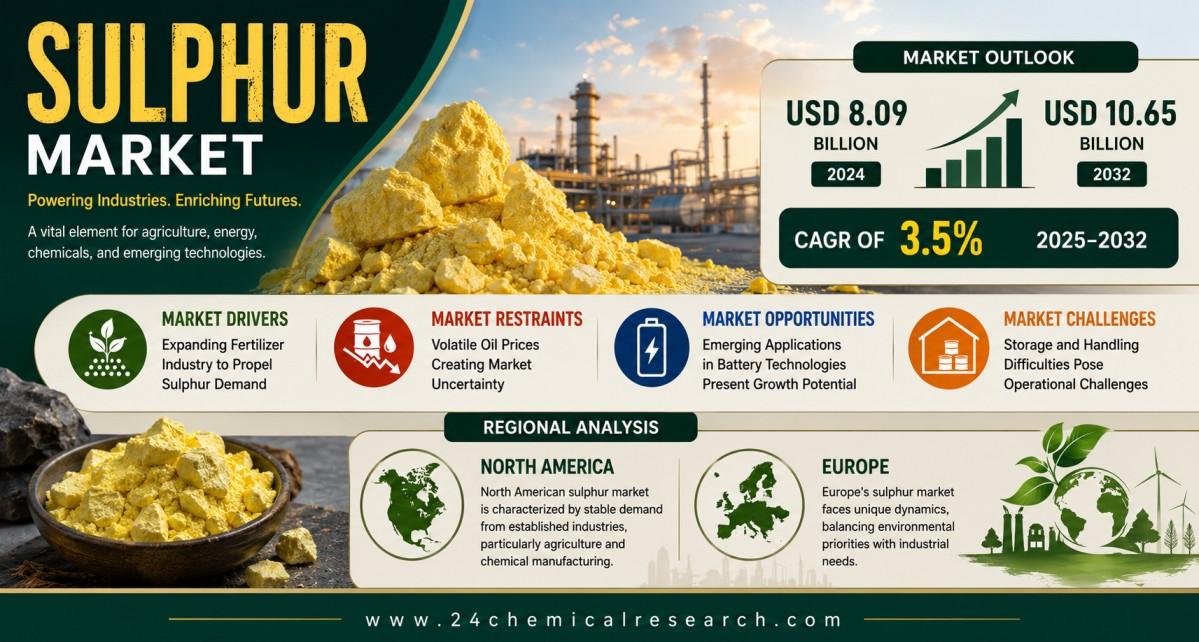
  • Global Sulphur Market to reach USD 10.65 Billion by 2032 at 3.5% CAGR. Fertilizer demand and sulfuric acid production drive sulphur consumption.

    View full report: https://www.24chemicalresearch.com/reports/291053/global-sulphur-forecast-market-2025-2032-307

    #MarketResearch #Sulphur #Fertilizers #SulfuricAcid #ChemicalIndustry
    Global Sulphur Market to reach USD 10.65 Billion by 2032 at 3.5% CAGR. Fertilizer demand and sulfuric acid production drive sulphur consumption. View full report: https://www.24chemicalresearch.com/reports/291053/global-sulphur-forecast-market-2025-2032-307 #MarketResearch #Sulphur #Fertilizers #SulfuricAcid #ChemicalIndustry
    0 Comments ·0 Shares ·260 Views
  • MAP Fertilizers Market Projected to Witness Significant Growth Driven by Global Agricultural Demand

    https://researchintelo.com/report/map-fertilizers-market

    The global MAP Fertilizers Market is poised for substantial growth due to the rising demand for high-efficiency fertilizers in modern agriculture. Monoammonium phosphate (MAP) fertilizers are widely used for their superior phosphorus and nitrogen content, critical nutrients for crop productivity. Increasing focus on enhancing soil fertility and improving crop yields is driving market adoption worldwide.
    MAP Fertilizers Market Projected to Witness Significant Growth Driven by Global Agricultural Demand https://researchintelo.com/report/map-fertilizers-market The global MAP Fertilizers Market is poised for substantial growth due to the rising demand for high-efficiency fertilizers in modern agriculture. Monoammonium phosphate (MAP) fertilizers are widely used for their superior phosphorus and nitrogen content, critical nutrients for crop productivity. Increasing focus on enhancing soil fertility and improving crop yields is driving market adoption worldwide.
    MAP Fertilizers Market Research Report 2033
    researchintelo.com
    According to our latest research, the MAP Fertilizers market size reached USD 14.2 billion globally in 2024, reflecting robust demand across key agricultural regions.
    0 Comments ·0 Shares ·427 Views