• The Low Voltage Electrical Switchboard Market includes assemblies used to distribute, control, isolate, and protect electrical power at low-voltage levels. They are widely deployed in residential, commercial, industrial, infrastructure, and data-center facilities. Construction activity, industrial automation, distributed energy resources, and electrical safety requirements are supporting demand for modular, compact, and digitally monitored switchboards. https://www.wiseguyreports.com/reports/low-voltage-electrical-switchboard-market
    The Low Voltage Electrical Switchboard Market includes assemblies used to distribute, control, isolate, and protect electrical power at low-voltage levels. They are widely deployed in residential, commercial, industrial, infrastructure, and data-center facilities. Construction activity, industrial automation, distributed energy resources, and electrical safety requirements are supporting demand for modular, compact, and digitally monitored switchboards. https://www.wiseguyreports.com/reports/low-voltage-electrical-switchboard-market
    Low Voltage Electrical Switchboard Market Sector Growth 2035
    www.wiseguyreports.com
    The Low Voltage Electrical Switchboard Market is expected to grow from 5.05 USD Billion in 2025 to 7.8 USD Billion by 2035. The Low Voltage Electrical Switchboard Market CAGR (growth rate) is expected to be around 4.4% | Wiseguy Reports
    0 Comments ·0 Shares ·320 Views
  • Virtual Reality in Gaming Market Opportunities Driven by Advanced Gaming Hardware and Software 2032

    Virtual Client Computing Market Overview

    The Virtual Client Computing Market report provides an in-depth analysis that is required to make informed industry decisions and develop strategic growth plans. Regardless of the production method or cost structures, the Virtual Client Computing market report provides a full understanding of advanced tactics and plans.

    Virtual Client Computing Market Forecast

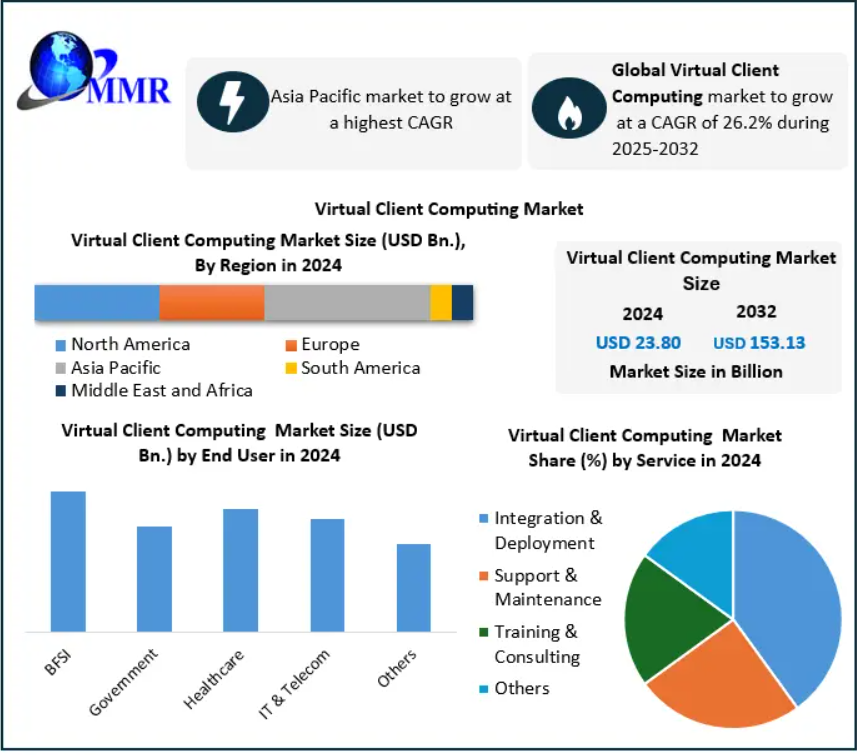
    Global Virtual Client Computing Market size was valued at USD 23.80 Bn. in 2024, and the total Virtual Client Computing Market revenue is expected to grow by 26.2% from 2025 to 2032, reaching nearly USD 153.13 Bn.

    Please connect with our representative, who will ensure you to get a report sample here @https://www.maximizemarketresearch.com/request-sample/81463/

    Virtual Client Computing Market Report Scope and Research Methodology

    The report offers an extensive examination of top players' strategies within the Virtual Client Computing industry, coupled with an in-depth analysis of market segments and regional dynamics. In-depth insights into market dynamics, encompassing drivers, restraints, opportunities, and challenges, are provided both on a regional and segmental basis within the Virtual Client Computing Market report. Additionally, the report presents import/export consumption, supply and demand, pricing, costs, revenue, and gross margins data, serving as an invaluable guide for investors.

    The data for the Virtual Client Computing Market report was meticulously gathered through a combination of primary and secondary research methods, ensuring its authenticity. Primary research methods employed encompassed questionnaire distribution, surveys, and telephone interviews with Virtual Client Computing industry experts, market leaders, marketing professionals, and entrepreneurs. The report's estimates of global and regional Virtual Client Computing market size were derived using a bottom-up approach. Furthermore, the strengths and weaknesses of Virtual Client Computing key players within the industry are outlined using SWOT analysis.

    Virtual Client Computing Market Regional Insights

    The report delves into the Virtual Client Computing business in great depth, segmenting it into numerous locations. North America, South America, Europe, Asia Pacific (APAC), Africa, and the Middle East are evaluated by region and country in the study. In the Virtual Client Computing market report, regional markets are thoroughly investigated in order to uncover regional market trends, restrictions, and possible prospects.

    Virtual Client Computing Market Segmentation

    by Type

    Virtual User Sessions (VUS)
    Terminal Sessions
    Virtual Desktop Infrastructure
    Others

    by Services

    Integration & Deployment
    Support & Maintenance
    Training & Consulting
    Others

    by Deployment Mode

    Hosted / Cloud-based
    On Premise

    by Enterprise Size

    Large Enterprises
    SMEs (Small & Medium Enterprises)

    by End Use

    BFSI
    Government
    Healthcare
    IT & Telecom
    Others

    Request Free Sample Copy:https://www.maximizemarketresearch.com/request-sample/81463/

    Virtual Client Computing Market Key Players

    1. VMware, Inc. (United States)
    2. Citrix Systems, Inc.(United States)
    3. Microsoft Corporation (United States)
    4. Dell Technologies, Inc.(United States)
    5. HP Inc.(United States)
    6. Nutanix, Inc.(United States)
    7. Cisco Systems, Inc.(United States)
    8. IBM Corporation (United States)
    9. IGEL Technology (Germany)
    10. Parallels International GmbH (United States)
    11. Ericom Software (United States)
    12. Sangfor Technologies (China)
    13. Huawei Technologies Co., Ltd.(China)
    14. Oracle Corporation (United States)
    15. NComputing Co., Ltd. (South Korea)
    16. Lenovo Group Limited (China)
    17. Teradici Corporation
    18. Unidesk Corporation

    Key Offerings:

    A detailed market overview
    Market Share, Size & Forecast by Revenue | 2026−2034
    Market Dynamics – Growth Drivers, Restraints, Investment Opportunities, and Key Trends
    Market Segmentation – A detailed analysis by segments and sub-segments
    Regional Insights
    Competitive Landscape – Top Key Vendors and Other Prominent Vendors
    More Trending From MMR:

    Global AI in Computer Vision Market https://www.maximizemarketresearch.com/market-report/global-ai-in-computer-vision-market/6916/
    HVAC Motors Market https://www.maximizemarketresearch.com/market-report/hvac-motors-market/66492/

    About Maximize Market Research:

    Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Contact Maximize Market Research:

    3rd Floor, Naval IT Park, Phase 2

    Pune Banglore Highway, Narhe

    Pune, Maharashtra 411041, India

    [email protected]

    +91 96071 95908, +91 9607365656
    Virtual Reality in Gaming Market Opportunities Driven by Advanced Gaming Hardware and Software 2032 Virtual Client Computing Market Overview The Virtual Client Computing Market report provides an in-depth analysis that is required to make informed industry decisions and develop strategic growth plans. Regardless of the production method or cost structures, the Virtual Client Computing market report provides a full understanding of advanced tactics and plans. Virtual Client Computing Market Forecast Global Virtual Client Computing Market size was valued at USD 23.80 Bn. in 2024, and the total Virtual Client Computing Market revenue is expected to grow by 26.2% from 2025 to 2032, reaching nearly USD 153.13 Bn. Please connect with our representative, who will ensure you to get a report sample here @https://www.maximizemarketresearch.com/request-sample/81463/ Virtual Client Computing Market Report Scope and Research Methodology The report offers an extensive examination of top players' strategies within the Virtual Client Computing industry, coupled with an in-depth analysis of market segments and regional dynamics. In-depth insights into market dynamics, encompassing drivers, restraints, opportunities, and challenges, are provided both on a regional and segmental basis within the Virtual Client Computing Market report. Additionally, the report presents import/export consumption, supply and demand, pricing, costs, revenue, and gross margins data, serving as an invaluable guide for investors. The data for the Virtual Client Computing Market report was meticulously gathered through a combination of primary and secondary research methods, ensuring its authenticity. Primary research methods employed encompassed questionnaire distribution, surveys, and telephone interviews with Virtual Client Computing industry experts, market leaders, marketing professionals, and entrepreneurs. The report's estimates of global and regional Virtual Client Computing market size were derived using a bottom-up approach. Furthermore, the strengths and weaknesses of Virtual Client Computing key players within the industry are outlined using SWOT analysis. Virtual Client Computing Market Regional Insights The report delves into the Virtual Client Computing business in great depth, segmenting it into numerous locations. North America, South America, Europe, Asia Pacific (APAC), Africa, and the Middle East are evaluated by region and country in the study. In the Virtual Client Computing market report, regional markets are thoroughly investigated in order to uncover regional market trends, restrictions, and possible prospects. Virtual Client Computing Market Segmentation by Type Virtual User Sessions (VUS) Terminal Sessions Virtual Desktop Infrastructure Others by Services Integration & Deployment Support & Maintenance Training & Consulting Others by Deployment Mode Hosted / Cloud-based On Premise by Enterprise Size Large Enterprises SMEs (Small & Medium Enterprises) by End Use BFSI Government Healthcare IT & Telecom Others Request Free Sample Copy:https://www.maximizemarketresearch.com/request-sample/81463/ Virtual Client Computing Market Key Players 1. VMware, Inc. (United States) 2. Citrix Systems, Inc.(United States) 3. Microsoft Corporation (United States) 4. Dell Technologies, Inc.(United States) 5. HP Inc.(United States) 6. Nutanix, Inc.(United States) 7. Cisco Systems, Inc.(United States) 8. IBM Corporation (United States) 9. IGEL Technology (Germany) 10. Parallels International GmbH (United States) 11. Ericom Software (United States) 12. Sangfor Technologies (China) 13. Huawei Technologies Co., Ltd.(China) 14. Oracle Corporation (United States) 15. NComputing Co., Ltd. (South Korea) 16. Lenovo Group Limited (China) 17. Teradici Corporation 18. Unidesk Corporation Key Offerings: A detailed market overview Market Share, Size & Forecast by Revenue | 2026−2034 Market Dynamics – Growth Drivers, Restraints, Investment Opportunities, and Key Trends Market Segmentation – A detailed analysis by segments and sub-segments Regional Insights Competitive Landscape – Top Key Vendors and Other Prominent Vendors More Trending From MMR: Global AI in Computer Vision Market https://www.maximizemarketresearch.com/market-report/global-ai-in-computer-vision-market/6916/ HVAC Motors Market https://www.maximizemarketresearch.com/market-report/hvac-motors-market/66492/ About Maximize Market Research: Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Contact Maximize Market Research: 3rd Floor, Naval IT Park, Phase 2 Pune Banglore Highway, Narhe Pune, Maharashtra 411041, India [email protected] +91 96071 95908, +91 9607365656
    0 Comments ·0 Shares ·320 Views
  • Urea Market Demand and Growth Outlook Across Key Applications

    Urea Market Poised for Expansion as Food Security, Industrial Demand and Low-Carbon Fertilizer Investments Reshape Global Industry

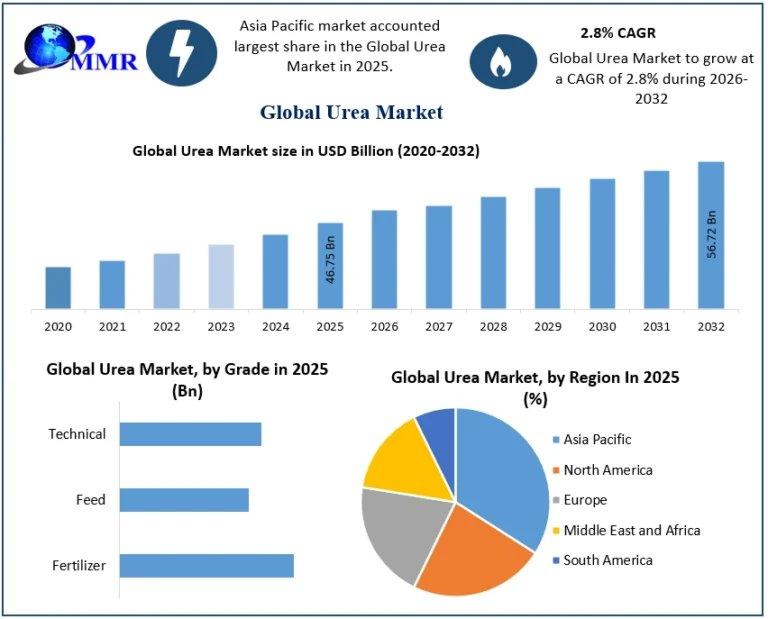
    The Urea Market is entering a period of expansion as food requirements, agricultural productivity and cleaner nitrogen investments strengthen demand. According to Maximize Market Research, the Urea Market was valued at USD 46.75 billion in 2025 and is projected to grow at a CAGR of 2.8% from 2026 to 2032, reaching nearly USD 56.72 billion by 2032. Urea remains vital because it contains approximately 46% nitrogen and is cost-effective for crop yields. Food-security priorities and shrinking arable land are supporting fertilizer consumption across agricultural economies.

    Beyond agriculture, urea demand is supported by chemical manufacturing, resins, plastics, animal nutrition and diesel exhaust fluid. Precision farming, green ammonia and carbon capture are creating opportunities for more efficient and lower-carbon fertilizer production.

    United States Market: 2025 Trends and Investment

    The U.S. urea market benefited from resilient nitrogen demand in 2025, supported by favorable corn economics and expectations for higher corn acreage. CF Industries reported strong North American nitrogen demand during the 2025 spring application season, while its outlook pointed to continued positive global nitrogen demand and constrained supply. In April 2025, CF Industries formed a joint venture with JERA and Mitsui to develop a low-carbon ammonia facility at its Blue Point Complex in Louisiana, incorporating carbon capture infrastructure. The project illustrates the U.S. shift toward lower-carbon nitrogen production. The USDA highlighted that global supply conditions make domestic capacity and supply-chain resilience investment priorities.

    Download a Free Sample of the Market Report : https://www.maximizemarketresearch.com/request-sample/26788/

    Market Segmentation: Largest-Share Segment

    By grade, agricultural-grade urea holds the largest share of the market. Its dominance reflects broad crop use, high nitrogen concentration and affordability. By application, fertilizers account for the largest market share because urea is widely used as a nitrogen fertilizer for improving crop productivity. Strong agricultural demand and food-security programs should preserve its leadership.

    Competitive Analysis

    Nutrien is a major nitrogen fertilizer producer with an extensive agricultural retail network. In 2025, the company increased nitrogen operating rates at North American facilities and allocated approximately USD 400–500 million of investing capital toward proprietary products, network optimization, digital capabilities and low-cost nitrogen expansions. Nutrien also agreed to sell its Profertil stake for about USD 600 million, supporting targeted growth, debt reduction and shareholder returns.

    CF Industries is a leading global ammonia and nitrogen producer with strong U.S. manufacturing capabilities. In 2025, the company planned approximately USD 500–550 million in capital spending and advanced its Blue Point low-carbon ammonia joint venture with JERA and Mitsui. The project could support lower-carbon nitrogen production.

    Yara International is pursuing sustainable fertilizer and ammonia opportunities. In December 2025, Yara and Air Products entered advanced negotiations to partner on low-emission ammonia projects in the United States and Saudi Arabia. The strategy supports supply diversification and lower-carbon fertilizer production.
    Urea Market Demand and Growth Outlook Across Key Applications Urea Market Poised for Expansion as Food Security, Industrial Demand and Low-Carbon Fertilizer Investments Reshape Global Industry The Urea Market is entering a period of expansion as food requirements, agricultural productivity and cleaner nitrogen investments strengthen demand. According to Maximize Market Research, the Urea Market was valued at USD 46.75 billion in 2025 and is projected to grow at a CAGR of 2.8% from 2026 to 2032, reaching nearly USD 56.72 billion by 2032. Urea remains vital because it contains approximately 46% nitrogen and is cost-effective for crop yields. Food-security priorities and shrinking arable land are supporting fertilizer consumption across agricultural economies. Beyond agriculture, urea demand is supported by chemical manufacturing, resins, plastics, animal nutrition and diesel exhaust fluid. Precision farming, green ammonia and carbon capture are creating opportunities for more efficient and lower-carbon fertilizer production. United States Market: 2025 Trends and Investment The U.S. urea market benefited from resilient nitrogen demand in 2025, supported by favorable corn economics and expectations for higher corn acreage. CF Industries reported strong North American nitrogen demand during the 2025 spring application season, while its outlook pointed to continued positive global nitrogen demand and constrained supply. In April 2025, CF Industries formed a joint venture with JERA and Mitsui to develop a low-carbon ammonia facility at its Blue Point Complex in Louisiana, incorporating carbon capture infrastructure. The project illustrates the U.S. shift toward lower-carbon nitrogen production. The USDA highlighted that global supply conditions make domestic capacity and supply-chain resilience investment priorities. Download a Free Sample of the Market Report : https://www.maximizemarketresearch.com/request-sample/26788/ Market Segmentation: Largest-Share Segment By grade, agricultural-grade urea holds the largest share of the market. Its dominance reflects broad crop use, high nitrogen concentration and affordability. By application, fertilizers account for the largest market share because urea is widely used as a nitrogen fertilizer for improving crop productivity. Strong agricultural demand and food-security programs should preserve its leadership. Competitive Analysis Nutrien is a major nitrogen fertilizer producer with an extensive agricultural retail network. In 2025, the company increased nitrogen operating rates at North American facilities and allocated approximately USD 400–500 million of investing capital toward proprietary products, network optimization, digital capabilities and low-cost nitrogen expansions. Nutrien also agreed to sell its Profertil stake for about USD 600 million, supporting targeted growth, debt reduction and shareholder returns. CF Industries is a leading global ammonia and nitrogen producer with strong U.S. manufacturing capabilities. In 2025, the company planned approximately USD 500–550 million in capital spending and advanced its Blue Point low-carbon ammonia joint venture with JERA and Mitsui. The project could support lower-carbon nitrogen production. Yara International is pursuing sustainable fertilizer and ammonia opportunities. In December 2025, Yara and Air Products entered advanced negotiations to partner on low-emission ammonia projects in the United States and Saudi Arabia. The strategy supports supply diversification and lower-carbon fertilizer production.
    0 Comments ·0 Shares ·407 Views
  • Isobutanol Market Growth, Demand and Future Industry Outlook

    Isobutanol Market Set to Reach USD 1.47 Billion by 2032, Driven by Growing Demand for Solvents, Chemical Intermediates and Sustainable Fuels

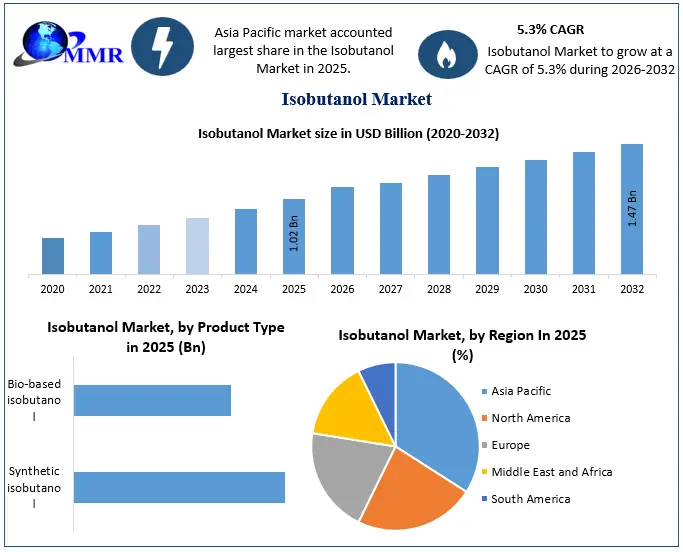
    The Isobutanol Market is entering a period of steady expansion as manufacturers across chemicals, coatings, oil & gas, pharmaceuticals and related industries increase their use of isobutanol as a versatile solvent and chemical intermediate. According to Maximize Market Research, the global Isobutanol Market size was valued at USD 1.02 billion in 2025 and is expected to grow at a CAGR of 5.3% from 2026 to 2032, reaching nearly USD 1.47 billion by 2032. Increasing industrial production, expanding applications in paints and coatings, demand for specialty chemical intermediates and growing interest in bio-based production technologies are expected to create attractive opportunities for market participants. Isobutanol's functional properties make it valuable in solvent formulations, coatings, chemical synthesis and fuel-related applications.

    U.S. Isobutanol Market Gains Momentum Through Industrial Demand and Low-Carbon Investment

    The United States remains an important market for isobutanol because of its large chemical manufacturing base, established refining infrastructure and expanding interest in renewable fuels. During 2025, industry activity highlighted both pricing pressure and investment in low-carbon technologies. Eastman announced a USD 0.05-per-pound increase on its N-Isobutyl Alcohol and selected Oxo products in North America and Latin America effective February 15, 2025, citing higher operating costs, particularly raw-material expenses. At the same time, Gevo completed its USD 210 million acquisition of Red Trail Energy's ethanol and carbon-capture assets in North Dakota in January 2025. The investment strengthens the company's low-carbon alcohol and renewable-fuels platform and creates an opportunity to develop additional alcohol-to-jet and related projects. Such developments demonstrate how U.S. producers are combining established alcohol infrastructure with carbon capture, renewable feedstocks and advanced conversion technologies. This trend can support longer-term opportunities for bio-based isobutanol and other renewable chemical products.

    Get a Free Sample Market Report Link : https://www.maximizemarketresearch.com/request-sample/56743/

    Synthetic Isobutanol Holds the Largest Market Share

    Based on the segmentation covered in the Maximize Market Research study, the market is analyzed according to Type, Application and Region. Among the segments, Synthetic Isobutanol represents the leading product category, supported by its established industrial manufacturing base, reliable availability and broad use in chemical and solvent applications. Synthetic production continues to benefit from mature production technologies and its ability to supply large-volume industrial requirements.

    Competitive Landscape: Companies Invest in Capacity, Sustainability and Advanced Chemistry

    The global Isobutanol Market remains competitive, with major chemical producers focusing on production reliability, downstream integration, product quality and technological development.

    Eastman Chemical Company maintains a significant position through its established Oxo alcohol portfolio and broad industrial customer base. In 2025, the company implemented a price increase for N-Isobutyl Alcohol in North America and Latin America because of elevated raw-material and operating costs. Its broad specialty-materials platform and application-development capabilities provide opportunities to optimize isobutanol-based products for coatings, construction, transportation and other markets.

    OQ Chemicals is strengthening its position through its extensive Oxo alcohol production network. Its Bay City, Texas operations are particularly important to the North American supply chain. Expansion of isobutanol production capacity in the United States is aligned with increasing demand from coatings, printing inks and chemical-intermediate manufacturers. Greater production capability can improve supply security while supporting downstream growth.

    BASF SE benefits from its global chemical manufacturing infrastructure and integrated approach to solvents, intermediates and performance chemicals. Continued investment in process efficiency, sustainable chemistry and specialty chemical applications can create additional opportunities for isobutanol-based formulations.

    Sasol Limited participates across the chemicals and solvents value chain, with its integrated production capabilities supporting industrial customers. The company's focus on operational efficiency and specialty chemical applications provides a platform for serving markets where performance solvents and chemical intermediates are required.

    Gevo Inc. represents an important emerging force in renewable alcohol and low-carbon chemical technologies. Its 2025 acquisition of Red Trail Energy for approximately USD 210 million added ethanol production and carbon-capture assets to its portfolio. The acquired site provides a platform for future sustainable aviation fuel and renewable-chemical projects, demonstrating how low-carbon alcohol technologies can become increasingly interconnected with the broader isobutanol and renewable chemicals ecosystem.

    Regional Analysis: United States, Germany, France, UK, Japan and China

    United States: The U.S. benefits from a strong petrochemical and chemical manufacturing ecosystem, extensive downstream solvent demand and growing investment in renewable fuels. Federal incentives supporting carbon reduction and renewable fuel production can encourage investment in low-carbon alcohol technologies.

    China: China offers substantial growth potential because of its large chemical manufacturing sector, expanding coatings industry and increasing demand for chemical intermediates. Domestic investment in integrated chemical complexes and downstream manufacturing is strengthening the country's role in global isobutanol supply.

    Germany: Germany's advanced chemical industry and emphasis on resource efficiency and sustainable manufacturing support demand for high-performance solvents and intermediates. European decarbonization initiatives can further encourage lower-carbon production routes.

    France: France is supported by its diversified chemical, coatings, automotive and industrial manufacturing industries. Increasing attention to sustainable chemistry and reduced-emission production can create opportunities for bio-based and advanced isobutanol technologies.

    United Kingdom: The UK market benefits from demand from specialty chemicals, coatings and industrial applications. Sustainability objectives and research into renewable chemicals may support the gradual adoption of bio-based alternatives.

    Japan: Japan's technologically advanced chemical and manufacturing industries create demand for high-purity and performance-oriented chemical materials. Applications in coatings, specialty chemicals and industrial formulations are expected to sustain demand for isobutanol.

    Key Players

    Key companies operating in the global Isobutanol Market include Eastman Chemical Company, OQ Chemicals, BASF SE, Sasol Limited and Gevo Inc. These companies compete through manufacturing capacity, product quality, technological innovation, supply-chain capabilities, sustainability initiatives and downstream application development.
    Isobutanol Market Growth, Demand and Future Industry Outlook Isobutanol Market Set to Reach USD 1.47 Billion by 2032, Driven by Growing Demand for Solvents, Chemical Intermediates and Sustainable Fuels The Isobutanol Market is entering a period of steady expansion as manufacturers across chemicals, coatings, oil & gas, pharmaceuticals and related industries increase their use of isobutanol as a versatile solvent and chemical intermediate. According to Maximize Market Research, the global Isobutanol Market size was valued at USD 1.02 billion in 2025 and is expected to grow at a CAGR of 5.3% from 2026 to 2032, reaching nearly USD 1.47 billion by 2032. Increasing industrial production, expanding applications in paints and coatings, demand for specialty chemical intermediates and growing interest in bio-based production technologies are expected to create attractive opportunities for market participants. Isobutanol's functional properties make it valuable in solvent formulations, coatings, chemical synthesis and fuel-related applications. U.S. Isobutanol Market Gains Momentum Through Industrial Demand and Low-Carbon Investment The United States remains an important market for isobutanol because of its large chemical manufacturing base, established refining infrastructure and expanding interest in renewable fuels. During 2025, industry activity highlighted both pricing pressure and investment in low-carbon technologies. Eastman announced a USD 0.05-per-pound increase on its N-Isobutyl Alcohol and selected Oxo products in North America and Latin America effective February 15, 2025, citing higher operating costs, particularly raw-material expenses. At the same time, Gevo completed its USD 210 million acquisition of Red Trail Energy's ethanol and carbon-capture assets in North Dakota in January 2025. The investment strengthens the company's low-carbon alcohol and renewable-fuels platform and creates an opportunity to develop additional alcohol-to-jet and related projects. Such developments demonstrate how U.S. producers are combining established alcohol infrastructure with carbon capture, renewable feedstocks and advanced conversion technologies. This trend can support longer-term opportunities for bio-based isobutanol and other renewable chemical products. Get a Free Sample Market Report Link : https://www.maximizemarketresearch.com/request-sample/56743/ Synthetic Isobutanol Holds the Largest Market Share Based on the segmentation covered in the Maximize Market Research study, the market is analyzed according to Type, Application and Region. Among the segments, Synthetic Isobutanol represents the leading product category, supported by its established industrial manufacturing base, reliable availability and broad use in chemical and solvent applications. Synthetic production continues to benefit from mature production technologies and its ability to supply large-volume industrial requirements. Competitive Landscape: Companies Invest in Capacity, Sustainability and Advanced Chemistry The global Isobutanol Market remains competitive, with major chemical producers focusing on production reliability, downstream integration, product quality and technological development. Eastman Chemical Company maintains a significant position through its established Oxo alcohol portfolio and broad industrial customer base. In 2025, the company implemented a price increase for N-Isobutyl Alcohol in North America and Latin America because of elevated raw-material and operating costs. Its broad specialty-materials platform and application-development capabilities provide opportunities to optimize isobutanol-based products for coatings, construction, transportation and other markets. OQ Chemicals is strengthening its position through its extensive Oxo alcohol production network. Its Bay City, Texas operations are particularly important to the North American supply chain. Expansion of isobutanol production capacity in the United States is aligned with increasing demand from coatings, printing inks and chemical-intermediate manufacturers. Greater production capability can improve supply security while supporting downstream growth. BASF SE benefits from its global chemical manufacturing infrastructure and integrated approach to solvents, intermediates and performance chemicals. Continued investment in process efficiency, sustainable chemistry and specialty chemical applications can create additional opportunities for isobutanol-based formulations. Sasol Limited participates across the chemicals and solvents value chain, with its integrated production capabilities supporting industrial customers. The company's focus on operational efficiency and specialty chemical applications provides a platform for serving markets where performance solvents and chemical intermediates are required. Gevo Inc. represents an important emerging force in renewable alcohol and low-carbon chemical technologies. Its 2025 acquisition of Red Trail Energy for approximately USD 210 million added ethanol production and carbon-capture assets to its portfolio. The acquired site provides a platform for future sustainable aviation fuel and renewable-chemical projects, demonstrating how low-carbon alcohol technologies can become increasingly interconnected with the broader isobutanol and renewable chemicals ecosystem. Regional Analysis: United States, Germany, France, UK, Japan and China United States: The U.S. benefits from a strong petrochemical and chemical manufacturing ecosystem, extensive downstream solvent demand and growing investment in renewable fuels. Federal incentives supporting carbon reduction and renewable fuel production can encourage investment in low-carbon alcohol technologies. China: China offers substantial growth potential because of its large chemical manufacturing sector, expanding coatings industry and increasing demand for chemical intermediates. Domestic investment in integrated chemical complexes and downstream manufacturing is strengthening the country's role in global isobutanol supply. Germany: Germany's advanced chemical industry and emphasis on resource efficiency and sustainable manufacturing support demand for high-performance solvents and intermediates. European decarbonization initiatives can further encourage lower-carbon production routes. France: France is supported by its diversified chemical, coatings, automotive and industrial manufacturing industries. Increasing attention to sustainable chemistry and reduced-emission production can create opportunities for bio-based and advanced isobutanol technologies. United Kingdom: The UK market benefits from demand from specialty chemicals, coatings and industrial applications. Sustainability objectives and research into renewable chemicals may support the gradual adoption of bio-based alternatives. Japan: Japan's technologically advanced chemical and manufacturing industries create demand for high-purity and performance-oriented chemical materials. Applications in coatings, specialty chemicals and industrial formulations are expected to sustain demand for isobutanol. Key Players Key companies operating in the global Isobutanol Market include Eastman Chemical Company, OQ Chemicals, BASF SE, Sasol Limited and Gevo Inc. These companies compete through manufacturing capacity, product quality, technological innovation, supply-chain capabilities, sustainability initiatives and downstream application development.
    0 Comments ·0 Shares ·544 Views
  • Why Choose Accredited Immigration DNA Testing in Bengaluru?

    Bengaluru is a leading metropolitan city in India, known for its advanced healthcare facilities, modern infrastructure, and strong international connectivity. For individuals applying for family visas or immigration, DNA testing can help provide reliable biological relationship verification when requested by an embassy or immigration authority.

    At DDC Laboratories India, we provide accurate, confidential, and professionally managed immigration DNA testing services in Bengaluru. With 250+ sample collection centers worldwide, applicants can access convenient collection options. Our testing process follows established quality standards, and we provide results within the applicable testing timeframe. Immigration DNA tests can verify relationships such as parent-child, siblings, or other eligible family relationships when required for immigration purposes.

    For questions about immigration DNA tests in Bengaluru, call +91 8010177771 or connect with us on WhatsApp at +91 9266615552.

    #ImmigrationDNATest #ImmigrationDNA #DNATestingBengaluru #BengaluruDNATesting #FamilyVisa #ImmigrationTesting #RelationshipDNA #LegalDNATest #FamilyReunification
    Why Choose Accredited Immigration DNA Testing in Bengaluru? Bengaluru is a leading metropolitan city in India, known for its advanced healthcare facilities, modern infrastructure, and strong international connectivity. For individuals applying for family visas or immigration, DNA testing can help provide reliable biological relationship verification when requested by an embassy or immigration authority. At DDC Laboratories India, we provide accurate, confidential, and professionally managed immigration DNA testing services in Bengaluru. With 250+ sample collection centers worldwide, applicants can access convenient collection options. Our testing process follows established quality standards, and we provide results within the applicable testing timeframe. Immigration DNA tests can verify relationships such as parent-child, siblings, or other eligible family relationships when required for immigration purposes. For questions about immigration DNA tests in Bengaluru, call +91 8010177771 or connect with us on WhatsApp at +91 9266615552. #ImmigrationDNATest #ImmigrationDNA #DNATestingBengaluru #BengaluruDNATesting #FamilyVisa #ImmigrationTesting #RelationshipDNA #LegalDNATest #FamilyReunification
    Immigration DNA Tests in Bengaluru – Fast, Accurate, Accredited
    www.ddclaboratories.com
    Get Immigration DNA Tests in Bengaluru from certified labs. We offer accredited DNA tests for immigration purposes. Call us at +91 8010177771.
    0 Comments ·0 Shares ·256 Views
  • Asia Pacific Biochar Market Growth, Trends, Opportunities and Forecast 2023–2029
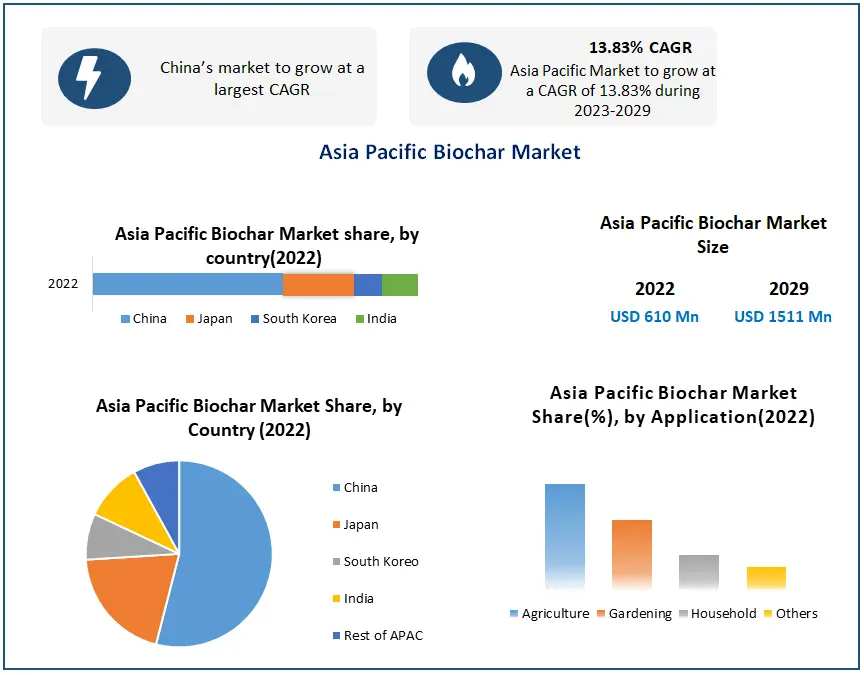
    The Asia Pacific Biochar Market was valued at USD 610 million in 2022 and is projected to grow at a CAGR of 13.83% from 2023 to 2029, reaching approximately USD 1,511 million by 2029. The market is gaining momentum as agriculture, waste management, and sustainable farming practices increasingly adopt biochar as an environmentally beneficial material.

    Asia Pacific Biochar Market Overview
    Biochar is increasingly being recognized across the Asia Pacific region for its applications in agriculture, gardening, waste management, and other end-use sectors. Strong environmental regulations, growing demand from end-user industries, increasing organic farming, and the use of biochar in waste management are among the major factors supporting market expansion.

    The agriculture sector represents a major area of demand for biochar. The material can be produced from different forms of biomass and agricultural waste, providing an opportunity to convert waste into a value-added resource. Pyrolysis remains one of the leading production methods and accounts for a significant share of the market.

    Request Free Sample Copy:https://www.maximizemarketresearch.com/request-sample/20189/

    Key Growth Drivers
    Rising Demand for Organic Farming
    The increasing adoption of organic farming and sustainable agricultural practices is creating significant demand for biochar. Farmers and agricultural businesses are increasingly exploring solutions that can support soil health while reducing dependence on conventional chemical fertilizers.

    Biochar also provides an opportunity to utilize agricultural and organic waste that would otherwise require disposal. Crop residues, biomass, and animal manure can be converted into biochar, creating an additional value stream from agricultural waste.

    Growing Importance of Waste Management
    The Asia Pacific region generates substantial quantities of agricultural and organic waste. Biochar production offers a method of converting some of these waste materials into useful products while reducing waste volumes.

    The combination of waste management and biochar production is therefore becoming increasingly relevant to governments, agricultural businesses, and sustainability-focused organizations.

    Environmental Regulations
    Stricter environmental regulations are also supporting market development. Governments and industries are looking for alternatives that can contribute to sustainable resource management and reduce environmental impacts.

    Market Restraints
    High Initial Investment
    The establishment of biochar production facilities and implementation of associated technologies can require significant upfront investment. High initial costs may discourage new entrants and investors, particularly in areas where financial resources and production infrastructure are limited.

    Lack of Awareness
    Limited awareness among farmers and consumers regarding the benefits and applications of biochar remains another challenge. Greater education and stakeholder awareness are needed to accelerate adoption across developing markets in the region.

    Market Opportunities
    Sustainable Agriculture
    Increasing awareness of sustainable agriculture presents an important opportunity for the Asia Pacific Biochar Market. Biochar can be incorporated into agricultural practices aimed at improving soil health and reducing dependence on chemical fertilizers.

    Growing consumer interest in environmentally friendly agricultural products may further encourage farmers to explore biochar-based solutions.

    Integration with Waste-to-Energy
    The region's large volume of agricultural and organic waste provides an opportunity to integrate biochar production with bioenergy and waste-to-energy processes. Such integration can enable the utilization of waste resources while creating value-added products.

    Government subsidies, incentives, and favorable regulations could further encourage investment in biochar production and sustainable agricultural practices.

    Asia Pacific Biochar Market Segmentation
    The market is segmented based on application, technology, manufacturing, and feedstock. Agriculture is a major application segment, while pyrolysis represents an important manufacturing process.

    By Technology
    Pyrolysis has dominated the market and is expected to maintain its leading position during the forecast period. It is a widely used thermochemical process in which biomass is heated in the absence of oxygen to produce biochar, bio-oil, and syngas.

    Gasification is another production method. In this process, biomass is oxidized to generate syngas, which can subsequently be processed to produce biochar.

    By Feedstock
    The Agricultural Waste segment holds a significant market share and is expected to remain dominant. Common agricultural feedstocks include rice straw, wheat straw, corn stalks, nutshells, and other biomass residues.

    Animal manure, including cow dung, swine dung, and poultry litter, is also used as a feedstock for biochar production.

    By Application
    The market covers:

    Agriculture
    Gardening
    Household
    Others
    By Manufacturing
    Gasification
    Pyrolysis
    Others
    By Feedstock
    Woody Biomass
    Agricultural Waste
    Animal Manure
    Others
    Request Free Sample Copy:https://www.maximizemarketresearch.com/request-sample/20189/

    Country Analysis
    China is the leading country in the Asia Pacific Biochar Market, accounting for approximately 95% of the regional market in 2022, according to the provided source. Chinese players are investing in research and development to understand biochar's effects on soil processes, agricultural productivity, and environmental conditions.

    Japan is also active in biochar research, particularly in understanding its physical, chemical, and biological properties and its effects on soil and compost. The broader Asia Pacific region is expected to experience strong growth, supported by pilot projects and increasing consumer adoption.

    The countries covered include China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan, and Rest of APAC.

    Asia Pacific Biochar Market Forecast
    Market Indicator Details
    Base Year 2022
    Historical Period 2018–2022
    Forecast Period 2023–2029
    Market Size in 2022 USD 610 Million
    CAGR 13.83%
    Market Size in 2029 USD 1,511 Million
    Key Application Agriculture
    Leading Manufacturing Process Pyrolysis
    Key Feedstock Agricultural Waste
    The market is expected to benefit from rising demand for sustainable agriculture, increasing organic waste generation, environmental regulations, and the growing integration of biochar with waste management and bioenergy systems.

    Competitive Landscape
    The Asia Pacific Biochar Market includes established companies and emerging participants involved in biochar production, pyrolysis technologies, biomass utilization, and sustainable resource management.

    Key players identified in the source include Biogreen-Energy, Agri-Tech Producers LLC, Genesis Industries, Diacarbon Energy Inc., Green Charcoal International, Vega Biofuels Inc., The Biochar Company, Cool Planet Energy Systems Inc., Full Circle Biochar, Pacific Pyrolysis Pty Ltd, ARSTA Eco, Earth Systems, Guangdong Dazhong Agricultural Science and Technology Co. Ltd, Rainbow Bee Eater and Pacific Pyrolysis, Biochar Now LLC, Tolero Energy, Airex Energy, Carbon Gold, Phoenix Energy, and AirTerra.

    Future Outlook
    The Asia Pacific Biochar Market has considerable growth potential as the region moves toward more sustainable agricultural and waste-management practices. Increasing awareness of soil health, organic farming, agricultural waste utilization, and environmentally responsible production is expected to support adoption.

    At the same time, reducing production costs, improving infrastructure, increasing stakeholder awareness, and introducing supportive government policies will be important for overcoming current market barriers.

    Overall, the market's projected growth from USD 610 million in 2022 to USD 1,511 million by 2029 highlights the expanding role of biochar in sustainable agriculture and resource management across Asia Pacific.
    Asia Pacific Biochar Market Growth, Trends, Opportunities and Forecast 2023–2029 The Asia Pacific Biochar Market was valued at USD 610 million in 2022 and is projected to grow at a CAGR of 13.83% from 2023 to 2029, reaching approximately USD 1,511 million by 2029. The market is gaining momentum as agriculture, waste management, and sustainable farming practices increasingly adopt biochar as an environmentally beneficial material. Asia Pacific Biochar Market Overview Biochar is increasingly being recognized across the Asia Pacific region for its applications in agriculture, gardening, waste management, and other end-use sectors. Strong environmental regulations, growing demand from end-user industries, increasing organic farming, and the use of biochar in waste management are among the major factors supporting market expansion. The agriculture sector represents a major area of demand for biochar. The material can be produced from different forms of biomass and agricultural waste, providing an opportunity to convert waste into a value-added resource. Pyrolysis remains one of the leading production methods and accounts for a significant share of the market. Request Free Sample Copy:https://www.maximizemarketresearch.com/request-sample/20189/ Key Growth Drivers Rising Demand for Organic Farming The increasing adoption of organic farming and sustainable agricultural practices is creating significant demand for biochar. Farmers and agricultural businesses are increasingly exploring solutions that can support soil health while reducing dependence on conventional chemical fertilizers. Biochar also provides an opportunity to utilize agricultural and organic waste that would otherwise require disposal. Crop residues, biomass, and animal manure can be converted into biochar, creating an additional value stream from agricultural waste. Growing Importance of Waste Management The Asia Pacific region generates substantial quantities of agricultural and organic waste. Biochar production offers a method of converting some of these waste materials into useful products while reducing waste volumes. The combination of waste management and biochar production is therefore becoming increasingly relevant to governments, agricultural businesses, and sustainability-focused organizations. Environmental Regulations Stricter environmental regulations are also supporting market development. Governments and industries are looking for alternatives that can contribute to sustainable resource management and reduce environmental impacts. Market Restraints High Initial Investment The establishment of biochar production facilities and implementation of associated technologies can require significant upfront investment. High initial costs may discourage new entrants and investors, particularly in areas where financial resources and production infrastructure are limited. Lack of Awareness Limited awareness among farmers and consumers regarding the benefits and applications of biochar remains another challenge. Greater education and stakeholder awareness are needed to accelerate adoption across developing markets in the region. Market Opportunities Sustainable Agriculture Increasing awareness of sustainable agriculture presents an important opportunity for the Asia Pacific Biochar Market. Biochar can be incorporated into agricultural practices aimed at improving soil health and reducing dependence on chemical fertilizers. Growing consumer interest in environmentally friendly agricultural products may further encourage farmers to explore biochar-based solutions. Integration with Waste-to-Energy The region's large volume of agricultural and organic waste provides an opportunity to integrate biochar production with bioenergy and waste-to-energy processes. Such integration can enable the utilization of waste resources while creating value-added products. Government subsidies, incentives, and favorable regulations could further encourage investment in biochar production and sustainable agricultural practices. Asia Pacific Biochar Market Segmentation The market is segmented based on application, technology, manufacturing, and feedstock. Agriculture is a major application segment, while pyrolysis represents an important manufacturing process. By Technology Pyrolysis has dominated the market and is expected to maintain its leading position during the forecast period. It is a widely used thermochemical process in which biomass is heated in the absence of oxygen to produce biochar, bio-oil, and syngas. Gasification is another production method. In this process, biomass is oxidized to generate syngas, which can subsequently be processed to produce biochar. By Feedstock The Agricultural Waste segment holds a significant market share and is expected to remain dominant. Common agricultural feedstocks include rice straw, wheat straw, corn stalks, nutshells, and other biomass residues. Animal manure, including cow dung, swine dung, and poultry litter, is also used as a feedstock for biochar production. By Application The market covers: Agriculture Gardening Household Others By Manufacturing Gasification Pyrolysis Others By Feedstock Woody Biomass Agricultural Waste Animal Manure Others Request Free Sample Copy:https://www.maximizemarketresearch.com/request-sample/20189/ Country Analysis China is the leading country in the Asia Pacific Biochar Market, accounting for approximately 95% of the regional market in 2022, according to the provided source. Chinese players are investing in research and development to understand biochar's effects on soil processes, agricultural productivity, and environmental conditions. Japan is also active in biochar research, particularly in understanding its physical, chemical, and biological properties and its effects on soil and compost. The broader Asia Pacific region is expected to experience strong growth, supported by pilot projects and increasing consumer adoption. The countries covered include China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan, and Rest of APAC. Asia Pacific Biochar Market Forecast Market Indicator Details Base Year 2022 Historical Period 2018–2022 Forecast Period 2023–2029 Market Size in 2022 USD 610 Million CAGR 13.83% Market Size in 2029 USD 1,511 Million Key Application Agriculture Leading Manufacturing Process Pyrolysis Key Feedstock Agricultural Waste The market is expected to benefit from rising demand for sustainable agriculture, increasing organic waste generation, environmental regulations, and the growing integration of biochar with waste management and bioenergy systems. Competitive Landscape The Asia Pacific Biochar Market includes established companies and emerging participants involved in biochar production, pyrolysis technologies, biomass utilization, and sustainable resource management. Key players identified in the source include Biogreen-Energy, Agri-Tech Producers LLC, Genesis Industries, Diacarbon Energy Inc., Green Charcoal International, Vega Biofuels Inc., The Biochar Company, Cool Planet Energy Systems Inc., Full Circle Biochar, Pacific Pyrolysis Pty Ltd, ARSTA Eco, Earth Systems, Guangdong Dazhong Agricultural Science and Technology Co. Ltd, Rainbow Bee Eater and Pacific Pyrolysis, Biochar Now LLC, Tolero Energy, Airex Energy, Carbon Gold, Phoenix Energy, and AirTerra. Future Outlook The Asia Pacific Biochar Market has considerable growth potential as the region moves toward more sustainable agricultural and waste-management practices. Increasing awareness of soil health, organic farming, agricultural waste utilization, and environmentally responsible production is expected to support adoption. At the same time, reducing production costs, improving infrastructure, increasing stakeholder awareness, and introducing supportive government policies will be important for overcoming current market barriers. Overall, the market's projected growth from USD 610 million in 2022 to USD 1,511 million by 2029 highlights the expanding role of biochar in sustainable agriculture and resource management across Asia Pacific.
    0 Comments ·0 Shares ·312 Views
  • Silica Aerogel Market Size and Share with Future Growth Opportunities

    Key Highlights

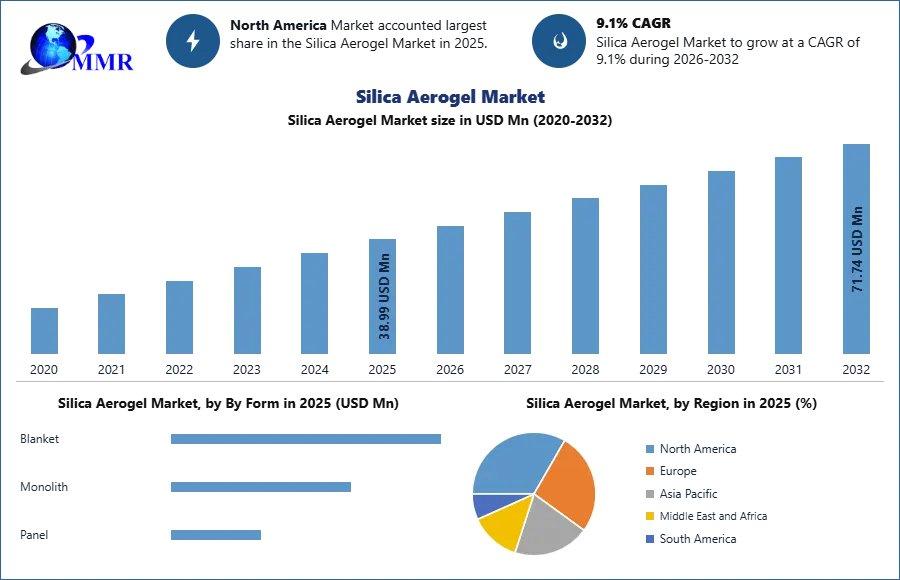
    The market was valued at USD 38.99 Mn in 2025.
    It is expected to reach USD 71.74 Mn by 2032.
    The market is projected to grow at a CAGR of 9.1% during the forecast period.
    Rising demand for high-performance insulation is strengthening the commercial relevance of silica aerogel.
    Manufacturers with advanced material capabilities are positioned to benefit from expanding application opportunities.

    Market Overview

    The Silica Aerogel Market is moving from a specialized material segment toward a broader industrial opportunity. Its commercial appeal comes from the ability of silica aerogel to provide high-performance insulation while maintaining a lightweight structure. This combination makes it relevant to industries seeking improved material efficiency and thermal management.

    The market reached USD 38.99 Mn in 2025, establishing a measurable base for future expansion. For manufacturers, this signals increasing opportunities to develop differentiated aerogel products and serve industries where conventional insulation solutions may not provide the required performance.

    Why This Market Matters Now

    Energy efficiency has become an increasingly important consideration for industrial operations, infrastructure developers, and equipment manufacturers. As businesses look for materials that can contribute to better thermal management, advanced insulation technologies are receiving greater attention.

    For investors, the projected expansion from USD 38.99 Mn in 2025 to USD 71.74 Mn by 2032 indicates a substantial increase in market value. This growth creates opportunities across production, application development, distribution, and technology-focused investments.

    Access a Free Sample Report Copy : https://www.maximizemarketresearch.com/request-sample/70767/

    Key Trends Driving Growth

    A major trend shaping the industry is the growing preference for materials that combine insulation performance with low weight. Silica aerogel fits this requirement and can support applications where space, weight, and thermal performance are important purchasing considerations.

    Another important trend is the movement toward advanced material solutions. As industrial users become more performance-oriented, suppliers have opportunities to compete through product quality, application-specific designs, and manufacturing capabilities rather than relying only on conventional insulation products.

    Silica Aerogel Market Size and Share with Future Growth Opportunities Key Highlights The market was valued at USD 38.99 Mn in 2025. It is expected to reach USD 71.74 Mn by 2032. The market is projected to grow at a CAGR of 9.1% during the forecast period. Rising demand for high-performance insulation is strengthening the commercial relevance of silica aerogel. Manufacturers with advanced material capabilities are positioned to benefit from expanding application opportunities. Market Overview The Silica Aerogel Market is moving from a specialized material segment toward a broader industrial opportunity. Its commercial appeal comes from the ability of silica aerogel to provide high-performance insulation while maintaining a lightweight structure. This combination makes it relevant to industries seeking improved material efficiency and thermal management. The market reached USD 38.99 Mn in 2025, establishing a measurable base for future expansion. For manufacturers, this signals increasing opportunities to develop differentiated aerogel products and serve industries where conventional insulation solutions may not provide the required performance. Why This Market Matters Now Energy efficiency has become an increasingly important consideration for industrial operations, infrastructure developers, and equipment manufacturers. As businesses look for materials that can contribute to better thermal management, advanced insulation technologies are receiving greater attention. For investors, the projected expansion from USD 38.99 Mn in 2025 to USD 71.74 Mn by 2032 indicates a substantial increase in market value. This growth creates opportunities across production, application development, distribution, and technology-focused investments. Access a Free Sample Report Copy : https://www.maximizemarketresearch.com/request-sample/70767/ Key Trends Driving Growth A major trend shaping the industry is the growing preference for materials that combine insulation performance with low weight. Silica aerogel fits this requirement and can support applications where space, weight, and thermal performance are important purchasing considerations. Another important trend is the movement toward advanced material solutions. As industrial users become more performance-oriented, suppliers have opportunities to compete through product quality, application-specific designs, and manufacturing capabilities rather than relying only on conventional insulation products.
    0 Comments ·0 Shares ·192 Views
  • Geosynthetics Market Analysis, Growth Drivers and Emerging Industry Trends

    Top of Form

    Key Highlights

    The Geosynthetics Market was valued at USD 19.21 billion in 2025, establishing a substantial base for future infrastructure demand.
    Revenue is projected to reach nearly USD 29.15 billion by 2032, indicating expanding commercial opportunities.
    The market is forecast to grow at a 6.14% CAGR from 2026 to 2032, reflecting sustained adoption.
    Asia Pacific held regional supremacy in 2025, supported by urbanization and infrastructure development.
    Geotextiles remain a prominent product category because of their broad construction and soil-management applications.

    Market Overview

    The Geosynthetics Market has moved beyond being a specialized construction-material segment into a strategic component of modern infrastructure. These engineered materials improve soil performance through filtration, drainage, reinforcement, separation, stabilization, and containment. Their ability to reduce material usage and support longer-lasting infrastructure is strengthening their relevance for project developers.

    Geotextiles are widely applied in roads, embankments, erosion control, and landscaping, while geomembranes provide impermeable barriers for applications such as landfills and containment systems. Geogrids reinforce soil and distribute loads, helping improve the performance of roads, retaining structures, and embankments.

    Get Your Free Sample Report Link : https://www.maximizemarketresearch.com/request-sample/30009/

    Key Trends Driving Growth

    A major trend shaping the Geosynthetics Market is the growing emphasis on resilient infrastructure. Geogrids can reinforce road structures, while geotextiles support drainage and soil stabilization. These applications become particularly important as urban development increases pressure on transportation and drainage networks.

    Environmental protection is another important growth factor. Geomembranes are used for containment in landfills, reservoirs, dams, and mining facilities. Meanwhile, erosion-control products support shoreline protection and slope stabilization.

    The integration of geosynthetics with recycled materials also creates opportunities for more resource-efficient construction. Advanced applications, including systems integrated with monitoring technologies, could further expand their role in infrastructure management.

    Geosynthetics Market Analysis, Growth Drivers and Emerging Industry Trends Top of Form Key Highlights The Geosynthetics Market was valued at USD 19.21 billion in 2025, establishing a substantial base for future infrastructure demand. Revenue is projected to reach nearly USD 29.15 billion by 2032, indicating expanding commercial opportunities. The market is forecast to grow at a 6.14% CAGR from 2026 to 2032, reflecting sustained adoption. Asia Pacific held regional supremacy in 2025, supported by urbanization and infrastructure development. Geotextiles remain a prominent product category because of their broad construction and soil-management applications. Market Overview The Geosynthetics Market has moved beyond being a specialized construction-material segment into a strategic component of modern infrastructure. These engineered materials improve soil performance through filtration, drainage, reinforcement, separation, stabilization, and containment. Their ability to reduce material usage and support longer-lasting infrastructure is strengthening their relevance for project developers. Geotextiles are widely applied in roads, embankments, erosion control, and landscaping, while geomembranes provide impermeable barriers for applications such as landfills and containment systems. Geogrids reinforce soil and distribute loads, helping improve the performance of roads, retaining structures, and embankments. Get Your Free Sample Report Link : https://www.maximizemarketresearch.com/request-sample/30009/ Key Trends Driving Growth A major trend shaping the Geosynthetics Market is the growing emphasis on resilient infrastructure. Geogrids can reinforce road structures, while geotextiles support drainage and soil stabilization. These applications become particularly important as urban development increases pressure on transportation and drainage networks. Environmental protection is another important growth factor. Geomembranes are used for containment in landfills, reservoirs, dams, and mining facilities. Meanwhile, erosion-control products support shoreline protection and slope stabilization. The integration of geosynthetics with recycled materials also creates opportunities for more resource-efficient construction. Advanced applications, including systems integrated with monitoring technologies, could further expand their role in infrastructure management.
    Request Sample
    www.maximizemarketresearch.com
    for Request Sample fill the form
    0 Comments ·0 Shares ·492 Views
  • Wallpaper Market Industry Analysis, Growth Drivers, and Future Opportunities

    Key Highlights

    The Wallpaper Market was valued at USD 2.01 billion in 2025, establishing a substantial base for continued industry expansion.
    Revenue is projected to reach nearly USD 2.78 billion by 2034, creating opportunities for manufacturers and distributors.
    The market is expected to expand at a 3.7% CAGR from 2026 to 2034, indicating steady rather than short-term growth.
    Non-woven wallpaper is expected to hold the largest market share by 2034 because of its practical installation and durability advantages.
    North America is expected to maintain market leadership through 2034, supported by home improvement demand and remodeling activity.

    Market Overview

    The Wallpaper Market is moving beyond its traditional role as a decorative wall covering. Wallpaper now combines design flexibility with practical attributes such as convenient installation, durability, rich patterns, color variety, and environmental considerations. These characteristics are increasing its relevance across homes, offices, and other buildings.

    The market reached USD 2.01 billion in 2025. This scale demonstrates established demand, while the projected increase to nearly USD 2.78 billion by 2034 points to continued commercial opportunities for manufacturers, retailers, and installation-related businesses.

    Why This Market Matters Now

    Construction activity and expanding housing infrastructure are creating new surfaces that require interior finishing solutions. At the same time, increasing disposable income and the growth of middle-class housing are supporting spending on interior improvements.

    The Wallpaper Market also benefits from installation convenience compared with traditional wall painting. However, specialized wallpaper can carry a higher cost, creating a pricing challenge that suppliers must address through product differentiation and value-focused offerings.

    Request Your Sample Report Now : https://www.maximizemarketresearch.com/request-sample/22571/

    Key Trends Driving Growth

    Digital printing is becoming an important development because it enables visually appealing wall designs while offering an economical alternative to interior paint. Digitally printed products also provide manufacturers with opportunities to deliver distinctive aesthetic solutions.

    Another important trend is the development of practical wallpaper materials. Non-woven products are valued for tear resistance, washability, flexibility, lightweight construction, and shorter installation and removal times. These characteristics align closely with consumers seeking lower-maintenance interior solutions.

    Wallpaper Market Industry Analysis, Growth Drivers, and Future Opportunities Key Highlights The Wallpaper Market was valued at USD 2.01 billion in 2025, establishing a substantial base for continued industry expansion. Revenue is projected to reach nearly USD 2.78 billion by 2034, creating opportunities for manufacturers and distributors. The market is expected to expand at a 3.7% CAGR from 2026 to 2034, indicating steady rather than short-term growth. Non-woven wallpaper is expected to hold the largest market share by 2034 because of its practical installation and durability advantages. North America is expected to maintain market leadership through 2034, supported by home improvement demand and remodeling activity. Market Overview The Wallpaper Market is moving beyond its traditional role as a decorative wall covering. Wallpaper now combines design flexibility with practical attributes such as convenient installation, durability, rich patterns, color variety, and environmental considerations. These characteristics are increasing its relevance across homes, offices, and other buildings. The market reached USD 2.01 billion in 2025. This scale demonstrates established demand, while the projected increase to nearly USD 2.78 billion by 2034 points to continued commercial opportunities for manufacturers, retailers, and installation-related businesses. Why This Market Matters Now Construction activity and expanding housing infrastructure are creating new surfaces that require interior finishing solutions. At the same time, increasing disposable income and the growth of middle-class housing are supporting spending on interior improvements. The Wallpaper Market also benefits from installation convenience compared with traditional wall painting. However, specialized wallpaper can carry a higher cost, creating a pricing challenge that suppliers must address through product differentiation and value-focused offerings. Request Your Sample Report Now : https://www.maximizemarketresearch.com/request-sample/22571/ Key Trends Driving Growth Digital printing is becoming an important development because it enables visually appealing wall designs while offering an economical alternative to interior paint. Digitally printed products also provide manufacturers with opportunities to deliver distinctive aesthetic solutions. Another important trend is the development of practical wallpaper materials. Non-woven products are valued for tear resistance, washability, flexibility, lightweight construction, and shorter installation and removal times. These characteristics align closely with consumers seeking lower-maintenance interior solutions.
    Request Sample
    www.maximizemarketresearch.com
    for Request Sample fill the form
    0 Comments ·0 Shares ·199 Views
  • Small Business Logistics Challenges That Can Slow Down Growth

    For many growing companies, small business logistics challenges do not begin with a major supply chain failure. They usually appear as small, recurring issues that gradually consume time and money. A delayed vehicle, limited storage space, inaccurate stock records, rising shipping costs, or the constant need to follow up on deliveries can quickly affect daily operations.

    One of the biggest logistics challenges for small businesses is managing growth with limited resources. Unlike larger organisations, they may not have separate teams for transportation, warehousing, inventory, and delivery coordination. As order volumes increase, manual processes and multiple service providers can make operations harder to control.

    A practical approach is to improve shipment planning, maintain clearer inventory visibility, and use logistics support that matches actual business requirements. Rather than investing heavily in infrastructure, businesses can build a more flexible supply chain by coordinating transport, storage, and delivery more effectively.

    Onpointlogistics helps businesses address everyday logistics requirements through solutions that support smoother movement of goods and better operational coordination.
    Click here for more- https://onpointlogistics.in/blog/how-small-business-logistics-challenges-affect-customer-experience


    #smallbusinesslogistics #logisticschallenge #onpoint
    Small Business Logistics Challenges That Can Slow Down Growth For many growing companies, small business logistics challenges do not begin with a major supply chain failure. They usually appear as small, recurring issues that gradually consume time and money. A delayed vehicle, limited storage space, inaccurate stock records, rising shipping costs, or the constant need to follow up on deliveries can quickly affect daily operations. One of the biggest logistics challenges for small businesses is managing growth with limited resources. Unlike larger organisations, they may not have separate teams for transportation, warehousing, inventory, and delivery coordination. As order volumes increase, manual processes and multiple service providers can make operations harder to control. A practical approach is to improve shipment planning, maintain clearer inventory visibility, and use logistics support that matches actual business requirements. Rather than investing heavily in infrastructure, businesses can build a more flexible supply chain by coordinating transport, storage, and delivery more effectively. Onpointlogistics helps businesses address everyday logistics requirements through solutions that support smoother movement of goods and better operational coordination. Click here for more- https://onpointlogistics.in/blog/how-small-business-logistics-challenges-affect-customer-experience #smallbusinesslogistics #logisticschallenge #onpoint
    How Small Business Logistics Challenges Can Impact Customer Experience
    onpointlogistics.in
    Learn how small business logistics challenges impact customer experience, revenue, and business growth, plus practical ways to overcome logistics issues.
    0 Comments ·0 Shares ·921 Views
  • Cross-Border Payments Market Size, Regional Revenue and Outlook 2026-2035

    The cross-border payments market was valued at USD 212.8 billion in 2025 and is projected to cross USD 434.5 billion by 2035, expanding at a CAGR of 7.4% during 2026-2035. Market expansion is being driven by international trade, global e-commerce, overseas employment and remittances, digital banking, and the growing need for faster and more transparent international money movement. Increasing adoption of fintech infrastructure and real-time payment technologies is also reshaping traditional cross-border transaction models.

    Request Sample @ https://www.researchnester.com/sample-request-8121

    Cross-Border Payments Industry Demand

    Cross-border payments refer to financial transactions in which the sender and recipient are located in different countries or jurisdictions. They enable businesses, consumers, financial institutions, governments, and organizations to transfer money internationally for trade, services, investments, payroll, remittances, and online purchases.

    Demand is increasing as businesses expand internationally and consumers increasingly purchase products and services from overseas merchants. Digital payment platforms can offer greater cost-effectiveness by reducing intermediary expenses, while automated administration simplifies reconciliation, compliance, currency conversion, and transaction tracking. Unlike physical financial products, the concept of “long shelf life” is not directly applicable to payment services; however, persistent digital accessibility, reusable payment infrastructure, and scalable transaction platforms provide comparable operational advantages. Faster settlement, improved transparency, enhanced security, and convenient mobile access are additional demand drivers.

    Cross-Border Payments Market: Growth Drivers & Key Restraint

    Growth Drivers –
    • Globalization and Cross-Border Commerce: International trade, remote services, global supply chains, freelance work, and e-commerce are increasing the frequency of international transactions.
    • Fintech and Payment Technology Innovation: Digital wallets, API-based payment infrastructure, artificial intelligence, blockchain, automated compliance, and real-time payment networks are making international transfers faster and more convenient.
    • Demand for Lower-Cost and Faster Transactions: Businesses and consumers increasingly expect transparent foreign-exchange pricing, reduced intermediary charges, instant or near-instant settlement, and easy transaction tracking.

    Restraint –
    • Complex regulatory requirements, foreign-exchange volatility, fraud and cybersecurity risks, fragmented payment infrastructures, sanctions screening, and inconsistent regulatory frameworks can increase transaction costs and implementation complexity.

    Cross-Border Payments Market: Segment Analysis

    Segment Analysis by Payment Type: B2B transactions serve international suppliers, distributors, contractors, and corporate partners and remain important for global commerce. C2B payments are supported by international online purchases and digital services. B2C payments facilitate international payroll, refunds, marketplace payouts, and business-to-consumer transfers. C2C transactions are strongly associated with remittances, family support, travel, and personal international transfers.

    Segment Analysis by End User: Large enterprises use cross-border payments for procurement, payroll, treasury, and international operations. SMEs increasingly rely on fintech platforms for affordable global transactions and overseas suppliers. Financial institutions facilitate institutional transfers, customer payments, and settlement services. Individual consumers primarily use international payments for remittances, online purchases, travel, and personal transfers. Government and public bodies require cross-border payment infrastructure for international programs, procurement, and institutional transactions.

    Segment Analysis by Payment Channel: Correspondent banking remains important for established international financial flows. Card networks support global commerce and consumer payments, while digital wallets provide convenient mobile-based transfers. Fintech platforms simplify international payments through APIs and specialized foreign-exchange services. Blockchain and cryptocurrency infrastructure can enable alternative settlement models, while ACH and RTP systems increasingly connect domestic instant-payment networks with international payment corridors.

    Segment Analysis by Settlement Speed: Instant settlement is gaining momentum in consumer and digital-commerce transactions. Near-instant payments provide a balance between speed and processing controls, while same-day settlement is increasingly preferred by businesses. Next-day services remain relevant for transactions requiring additional verification. Legacy multi-day transfers continue to serve certain institutional and correspondent-banking workflows but face growing pressure from faster alternatives.

    Segment Analysis by Industry Vertical: E-commerce and retail require seamless international checkout and merchant settlement. Manufacturing and logistics depend on payments across complex supply chains. Travel and hospitality use international transactions for bookings and supplier payments. IT and BPO companies rely on cross-border payments for global clients and distributed workforces. Oil, gas, and mining require high-value international settlements. Healthcare and pharmaceuticals use them for equipment, medicines, research, and services. Education depends on international tuition and institutional payments, while remittance and family-support services rely heavily on accessible consumer transfers.

    Segment Analysis by Currency Type: G10 currencies remain central to international trade and financial settlement. The Chinese renminbi is increasingly relevant to Asian trade and global supply chains. Emerging-market currencies are gaining importance as regional commerce expands. Stablecoins are attracting interest for programmable and potentially faster settlement, particularly in digital-native payment environments. Central bank digital currencies may eventually support more direct and efficient international settlement, subject to regulatory interoperability and infrastructure development.

    Cross-Border Payments Market: Regional Insights

    North America

    The region benefits from sophisticated financial infrastructure, extensive international trade, strong fintech adoption, and substantial digital-commerce activity. Demand is supported by corporate payments, global marketplaces, remittances, and increasing preference for real-time digital transfers.

    Europe

    Cross-border payments benefit from integrated financial markets, extensive intra-regional commerce, digital banking adoption, and regulatory initiatives promoting payment efficiency and consumer protection. Fintech providers and open-banking infrastructure are strengthening competitive pressure on traditional payment channels.

    Asia-Pacific

    APAC is a major growth region because of expanding e-commerce, international trade, mobile-wallet adoption, migrant remittances, and rapid fintech development. Growing economic integration and digital payment ecosystems are creating demand for faster, interoperable, and lower-cost international payment solutions.

    Top Players in the Cross-Border Payments Market

    Key players in the cross-border payments market include JPMorgan Chase & Co. (U.S.), Visa Inc. (U.S.), Mastercard Incorporated (U.S.), Wells Fargo & Company (U.S.), PayPal Holdings, Inc. (U.S.), Wise plc (UK), Revolut Ltd (UK), Adyen N.V. (Netherlands), Worldline SA (France), Deutsche Bank AG (Germany), Standard Chartered PLC (UK), Mitsubishi UFJ Financial Group (MUFG) (Japan), Sumitomo Mitsui Financial Group (SMFG) (Japan), Airwallex Pty Ltd (Australia), Nium Pte. Ltd. (Singapore), Toss Payments (South Korea), Amazon (U.S.), Bank of America (U.S.), NTT DATA (Japan), and Citi (U.S.). These companies compete through global payment networks, digital wallets, banking infrastructure, foreign-exchange services, real-time settlement capabilities, merchant acquiring, fintech platforms, and technology-driven payment solutions.

    Access Detailed Report @ https://www.researchnester.com/reports/cross-border-payments-market/8121

    Research Nester Analytics is a leading service provider for strategic market research and consulting. We provide unbiased, unparalleled market insights and industry analysis to help industries, conglomerates, and executives make informed decisions regarding future marketing strategy, expansion, and investments. We believe every business can expand its horizon with the right guidance at the right time. Our out-of-the-box thinking helps clients navigate future uncertainties and market dynamics.

    Contact for more Info:
    AJ Daniel
    Email: [email protected]
    U.S. Phone: +1 646 586 9123
    U.K. Phone: +44 203 608 5919
    Cross-Border Payments Market Size, Regional Revenue and Outlook 2026-2035 The cross-border payments market was valued at USD 212.8 billion in 2025 and is projected to cross USD 434.5 billion by 2035, expanding at a CAGR of 7.4% during 2026-2035. Market expansion is being driven by international trade, global e-commerce, overseas employment and remittances, digital banking, and the growing need for faster and more transparent international money movement. Increasing adoption of fintech infrastructure and real-time payment technologies is also reshaping traditional cross-border transaction models. Request Sample @ https://www.researchnester.com/sample-request-8121 Cross-Border Payments Industry Demand Cross-border payments refer to financial transactions in which the sender and recipient are located in different countries or jurisdictions. They enable businesses, consumers, financial institutions, governments, and organizations to transfer money internationally for trade, services, investments, payroll, remittances, and online purchases. Demand is increasing as businesses expand internationally and consumers increasingly purchase products and services from overseas merchants. Digital payment platforms can offer greater cost-effectiveness by reducing intermediary expenses, while automated administration simplifies reconciliation, compliance, currency conversion, and transaction tracking. Unlike physical financial products, the concept of “long shelf life” is not directly applicable to payment services; however, persistent digital accessibility, reusable payment infrastructure, and scalable transaction platforms provide comparable operational advantages. Faster settlement, improved transparency, enhanced security, and convenient mobile access are additional demand drivers. Cross-Border Payments Market: Growth Drivers & Key Restraint Growth Drivers – • Globalization and Cross-Border Commerce: International trade, remote services, global supply chains, freelance work, and e-commerce are increasing the frequency of international transactions. • Fintech and Payment Technology Innovation: Digital wallets, API-based payment infrastructure, artificial intelligence, blockchain, automated compliance, and real-time payment networks are making international transfers faster and more convenient. • Demand for Lower-Cost and Faster Transactions: Businesses and consumers increasingly expect transparent foreign-exchange pricing, reduced intermediary charges, instant or near-instant settlement, and easy transaction tracking. Restraint – • Complex regulatory requirements, foreign-exchange volatility, fraud and cybersecurity risks, fragmented payment infrastructures, sanctions screening, and inconsistent regulatory frameworks can increase transaction costs and implementation complexity. Cross-Border Payments Market: Segment Analysis Segment Analysis by Payment Type: B2B transactions serve international suppliers, distributors, contractors, and corporate partners and remain important for global commerce. C2B payments are supported by international online purchases and digital services. B2C payments facilitate international payroll, refunds, marketplace payouts, and business-to-consumer transfers. C2C transactions are strongly associated with remittances, family support, travel, and personal international transfers. Segment Analysis by End User: Large enterprises use cross-border payments for procurement, payroll, treasury, and international operations. SMEs increasingly rely on fintech platforms for affordable global transactions and overseas suppliers. Financial institutions facilitate institutional transfers, customer payments, and settlement services. Individual consumers primarily use international payments for remittances, online purchases, travel, and personal transfers. Government and public bodies require cross-border payment infrastructure for international programs, procurement, and institutional transactions. Segment Analysis by Payment Channel: Correspondent banking remains important for established international financial flows. Card networks support global commerce and consumer payments, while digital wallets provide convenient mobile-based transfers. Fintech platforms simplify international payments through APIs and specialized foreign-exchange services. Blockchain and cryptocurrency infrastructure can enable alternative settlement models, while ACH and RTP systems increasingly connect domestic instant-payment networks with international payment corridors. Segment Analysis by Settlement Speed: Instant settlement is gaining momentum in consumer and digital-commerce transactions. Near-instant payments provide a balance between speed and processing controls, while same-day settlement is increasingly preferred by businesses. Next-day services remain relevant for transactions requiring additional verification. Legacy multi-day transfers continue to serve certain institutional and correspondent-banking workflows but face growing pressure from faster alternatives. Segment Analysis by Industry Vertical: E-commerce and retail require seamless international checkout and merchant settlement. Manufacturing and logistics depend on payments across complex supply chains. Travel and hospitality use international transactions for bookings and supplier payments. IT and BPO companies rely on cross-border payments for global clients and distributed workforces. Oil, gas, and mining require high-value international settlements. Healthcare and pharmaceuticals use them for equipment, medicines, research, and services. Education depends on international tuition and institutional payments, while remittance and family-support services rely heavily on accessible consumer transfers. Segment Analysis by Currency Type: G10 currencies remain central to international trade and financial settlement. The Chinese renminbi is increasingly relevant to Asian trade and global supply chains. Emerging-market currencies are gaining importance as regional commerce expands. Stablecoins are attracting interest for programmable and potentially faster settlement, particularly in digital-native payment environments. Central bank digital currencies may eventually support more direct and efficient international settlement, subject to regulatory interoperability and infrastructure development. Cross-Border Payments Market: Regional Insights North America The region benefits from sophisticated financial infrastructure, extensive international trade, strong fintech adoption, and substantial digital-commerce activity. Demand is supported by corporate payments, global marketplaces, remittances, and increasing preference for real-time digital transfers. Europe Cross-border payments benefit from integrated financial markets, extensive intra-regional commerce, digital banking adoption, and regulatory initiatives promoting payment efficiency and consumer protection. Fintech providers and open-banking infrastructure are strengthening competitive pressure on traditional payment channels. Asia-Pacific APAC is a major growth region because of expanding e-commerce, international trade, mobile-wallet adoption, migrant remittances, and rapid fintech development. Growing economic integration and digital payment ecosystems are creating demand for faster, interoperable, and lower-cost international payment solutions. Top Players in the Cross-Border Payments Market Key players in the cross-border payments market include JPMorgan Chase & Co. (U.S.), Visa Inc. (U.S.), Mastercard Incorporated (U.S.), Wells Fargo & Company (U.S.), PayPal Holdings, Inc. (U.S.), Wise plc (UK), Revolut Ltd (UK), Adyen N.V. (Netherlands), Worldline SA (France), Deutsche Bank AG (Germany), Standard Chartered PLC (UK), Mitsubishi UFJ Financial Group (MUFG) (Japan), Sumitomo Mitsui Financial Group (SMFG) (Japan), Airwallex Pty Ltd (Australia), Nium Pte. Ltd. (Singapore), Toss Payments (South Korea), Amazon (U.S.), Bank of America (U.S.), NTT DATA (Japan), and Citi (U.S.). These companies compete through global payment networks, digital wallets, banking infrastructure, foreign-exchange services, real-time settlement capabilities, merchant acquiring, fintech platforms, and technology-driven payment solutions. Access Detailed Report @ https://www.researchnester.com/reports/cross-border-payments-market/8121 Research Nester Analytics is a leading service provider for strategic market research and consulting. We provide unbiased, unparalleled market insights and industry analysis to help industries, conglomerates, and executives make informed decisions regarding future marketing strategy, expansion, and investments. We believe every business can expand its horizon with the right guidance at the right time. Our out-of-the-box thinking helps clients navigate future uncertainties and market dynamics. Contact for more Info: AJ Daniel Email: [email protected] U.S. Phone: +1 646 586 9123 U.K. Phone: +44 203 608 5919
    0 Comments ·0 Shares ·399 Views
  • Europe Calcium Dolomite market to reach USD 402.00 Million by 2034 at 5.9% CAGR. Germany leads, Eastern Europe fastest growing, driven by construction and infrastructure modernization.

    Get the full report: https://www.24chemicalresearch.com/reports/285578/europe-calcium-dolomite-market

    #MarketResearch, #CalciumDolomite, #ConstructionMaterials, #Europe
    Europe Calcium Dolomite market to reach USD 402.00 Million by 2034 at 5.9% CAGR. Germany leads, Eastern Europe fastest growing, driven by construction and infrastructure modernization. Get the full report: https://www.24chemicalresearch.com/reports/285578/europe-calcium-dolomite-market #MarketResearch, #CalciumDolomite, #ConstructionMaterials, #Europe
    0 Comments ·0 Shares ·365 Views
More Results