• Buy SSN Number USA
    https://usaoldteam.com/product/get-ssn-number/
    Contact Us If You Have Any Questions:➥24 Reply/
    Telegram: @usaoldteam
    WhatsApp: +1 (740) 705-0905
    Email: [email protected]
    We sell personal and business.100% Verified Us, Uk, Ca,
    #smm #usaoldteam #bestshop #bestusaoldteam #business #digital #usa_facebook #instagram #old_github_accounts #old_gmail #googlevoice #usaaccounts #accounting #bestusaseller #usatopseller #highlights #foryou

    Buy SSN Number USA https://usaoldteam.com/product/get-ssn-number/ Contact Us If You Have Any Questions:➥24 Reply/ Telegram: @usaoldteam WhatsApp: +1 (740) 705-0905 Email: [email protected] We sell personal and business.100% Verified Us, Uk, Ca, #smm #usaoldteam #bestshop #bestusaoldteam #business #digital #usa_facebook #instagram #old_github_accounts #old_gmail #googlevoice #usaaccounts #accounting #bestusaseller #usatopseller #highlights #foryou
    Get SSN Number - Requirements & Process Explained
    usaoldteam.com
    Official guidance on Social Security Numbers, including application steps, eligibility, and how to keep your SSN secure.Get SSN Number
    0 Comments ·0 Shares ·126 Views
  • Buy Old Facebook Accounts In The USA
    https://usaoldteam.com/product/get-usa-facebook-accounts/
    Contact Us If You Have Any Questions:➥24 Reply/
    Telegram: @usaoldteam
    WhatsApp: +1 (740) 705-0905
    Email: [email protected]
    We sell personal and business.100% Verified Us, Uk, Ca,
    #smm #usaoldteam #bestshop #bestusaoldteam #business #digital #usa_facebook #instagram #old_github_accounts #old_gmail #googlevoice #usaaccounts #accounting #bestusaseller #usatopseller #highlights #foryou
    Buy Old Facebook Accounts In The USA https://usaoldteam.com/product/get-usa-facebook-accounts/ Contact Us If You Have Any Questions:➥24 Reply/ Telegram: @usaoldteam WhatsApp: +1 (740) 705-0905 Email: [email protected] We sell personal and business.100% Verified Us, Uk, Ca, #smm #usaoldteam #bestshop #bestusaoldteam #business #digital #usa_facebook #instagram #old_github_accounts #old_gmail #googlevoice #usaaccounts #accounting #bestusaseller #usatopseller #highlights #foryou
    Get USA Facebook Accounts - with Marketplace
    usaoldteam.com
    Get USA Facebook Accounts for uaoldteam.com.We offer 100% verified USA Facebook Accounts. USA Facebook account for your business
    0 Comments ·0 Shares ·126 Views
  • Data Integration Market Trends Highlight Real-Time Data Processing

    Market Estimation & Definition

    The global Data Integration Market is experiencing strong growth as businesses increasingly rely on connected data to improve operational efficiency, support strategic decisions, and strengthen digital transformation initiatives. According to Stellar Market Research, the Data Integration Market size was valued at USD 16.23 Bn in 2025. The Global Data Integration Market is estimated to grow at a CAGR of 11.23% over the forecast period.

    Data integration refers to the process of combining information from different sources, systems, applications, and databases to create a unified and consistent view. It enables organizations to access relevant information across departments, improve data accuracy, and make better-informed business decisions. As enterprises generate increasing volumes of information through cloud platforms, digital transactions, connected devices, and business applications, effective data integration is becoming an essential part of modern IT infrastructure.

    Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Data-Integration-Market/460

    Market Growth Drivers & Opportunity

    The growing adoption of cloud computing is a major driver of the Data Integration Market. Organizations increasingly use multiple cloud environments alongside existing on-premises infrastructure. Integrating these systems allows businesses to synchronize information, reduce data duplication, and improve accessibility across teams and applications.

    Digital transformation across banking, financial services, retail, manufacturing, and other industries is also increasing demand. Businesses need reliable access to data from multiple operational systems to monitor performance, understand customer behavior, streamline workflows, and support analytics initiatives.

    Another important opportunity lies in open-source integration technologies. These solutions can provide organizations with flexible implementation options and help manage integration costs. Demand for professional and managed services is also increasing as businesses seek specialist support for implementation, system migration, maintenance, and data governance.

    However, market expansion faces challenges, including shortages of skilled professionals, inconsistent data management standards, legacy-system compatibility issues, and the complexity of implementing advanced extract, transform, and load (ETL) solutions. Providers that simplify deployment, improve interoperability, and strengthen security are well positioned to address these concerns.

    What Lies Ahead: Emerging Trends Shaping the Future

    Cloud-based integration is expected to remain a central trend as organizations connect applications and databases distributed across different environments. Integration platforms that support hybrid infrastructure can help businesses maintain continuity while modernizing their technology systems.

    Automation and real-time data synchronization are also becoming increasingly important. Companies need timely, consistent information to support analytics, customer services, supply-chain operations, and business intelligence. Integration tools that reduce manual data handling can improve productivity and limit errors.

    At the same time, organizations are placing greater emphasis on data quality, governance, and security. As information moves between platforms, businesses must maintain appropriate access controls and comply with relevant regulatory requirements. Open-source solutions and managed integration services are likely to provide additional opportunities, particularly for organizations seeking flexible deployment and specialist expertise.

    Get More Report Details: https://www.stellarmr.com/report/Data-Integration-Market/460

    Segmentation Analysis

    According to the Stellar Market Research report, the Data Integration Market is segmented by component, deployment mode, and region.

    By Component:
    Tools
    Service
    Managed Services
    Professional Services
    The service segment held the leading position in 2024, accounting for 38.1% of the market. Demand is supported by the need for implementation expertise, efficient integration, and ongoing technical support.

    By Deployment Mode:
    On-Premises
    Cloud
    Cloud deployment dominated the market in 2024, representing 65.3% of the total. Its flexibility and ability to connect distributed applications make it an important choice for organizations modernizing their IT environments.

    By Region:
    North America
    Europe
    Asia Pacific
    Middle East and Africa
    South America
    Country-Level Analysis: USA and Germany

    United States: North America led the global Data Integration Market in 2024, with a 42.6% share. The United States benefits from established technology providers, investment in research and development, and demand from industries such as banking, retail, and financial services. Major companies including IBM, Microsoft, Oracle, Informatica, and Salesforce contribute to the competitive technology landscape. Continued cloud adoption and the need to connect enterprise applications are expected to support demand.

    Germany: Germany represents an important European market for data integration. The presence of enterprise technology providers such as SAP and Software AG supports the country's role in business software and integration solutions. Demand is associated with the need to connect enterprise systems, improve operational visibility, and manage information across complex business environments. The report includes Germany within its European regional coverage but does not provide a separate headline market valuation for the country.

    Competitive Analysis

    The Data Integration Market features established enterprise software companies and specialist solution providers competing through product development, cloud capabilities, interoperability, and service offerings. Key players identified by Stellar Market Research include IBM, Microsoft, SAP, Oracle, SAS Institute, Talend, Informatica, Precisely, Software AG, Salesforce, Qlik, TIBCO, Syncsort, Panoply, and Intel Corporation.

    Competition is shaped by the ability to integrate diverse data sources, support cloud and on-premises environments, and deliver reliable, scalable solutions. Providers offering flexible deployment, strong governance features, and managed services may be better positioned to meet the needs of organizations with increasingly complex data ecosystems.

    Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Data-Integration-Market/460

    Press Release Conclusion

    The Data Integration Market is set for substantial expansion as organizations prioritize cloud adoption, digital transformation, and effective enterprise data management. With the market projected to grow from USD 14.59 billion in 2024 to USD 34.19 billion by 2032, opportunities are emerging across integration tools, professional services, managed services, and cloud platforms.

    Although legacy-system complexity, skills shortages, and data standardization remain challenges, continued investment in automation, interoperability, and secure data exchange is expected to support long-term development. Businesses and technology providers that can simplify integration while maintaining data quality and governance will be well positioned to benefit from the market's growth.

    About Stellar Market Research:

    Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.

    Contact Stellar Market Research:

    3rd Floor, Navale IT Park, Phase 2

    Pune Banglore Highway, Narhe,

    Pune, Maharashtra 411041, India

    [email protected]

    +91 20 6630 3320 | +91 9607365656

    Data Integration Market Trends Highlight Real-Time Data Processing Market Estimation & Definition The global Data Integration Market is experiencing strong growth as businesses increasingly rely on connected data to improve operational efficiency, support strategic decisions, and strengthen digital transformation initiatives. According to Stellar Market Research, the Data Integration Market size was valued at USD 16.23 Bn in 2025. The Global Data Integration Market is estimated to grow at a CAGR of 11.23% over the forecast period. Data integration refers to the process of combining information from different sources, systems, applications, and databases to create a unified and consistent view. It enables organizations to access relevant information across departments, improve data accuracy, and make better-informed business decisions. As enterprises generate increasing volumes of information through cloud platforms, digital transactions, connected devices, and business applications, effective data integration is becoming an essential part of modern IT infrastructure. Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Data-Integration-Market/460 Market Growth Drivers & Opportunity The growing adoption of cloud computing is a major driver of the Data Integration Market. Organizations increasingly use multiple cloud environments alongside existing on-premises infrastructure. Integrating these systems allows businesses to synchronize information, reduce data duplication, and improve accessibility across teams and applications. Digital transformation across banking, financial services, retail, manufacturing, and other industries is also increasing demand. Businesses need reliable access to data from multiple operational systems to monitor performance, understand customer behavior, streamline workflows, and support analytics initiatives. Another important opportunity lies in open-source integration technologies. These solutions can provide organizations with flexible implementation options and help manage integration costs. Demand for professional and managed services is also increasing as businesses seek specialist support for implementation, system migration, maintenance, and data governance. However, market expansion faces challenges, including shortages of skilled professionals, inconsistent data management standards, legacy-system compatibility issues, and the complexity of implementing advanced extract, transform, and load (ETL) solutions. Providers that simplify deployment, improve interoperability, and strengthen security are well positioned to address these concerns. What Lies Ahead: Emerging Trends Shaping the Future Cloud-based integration is expected to remain a central trend as organizations connect applications and databases distributed across different environments. Integration platforms that support hybrid infrastructure can help businesses maintain continuity while modernizing their technology systems. Automation and real-time data synchronization are also becoming increasingly important. Companies need timely, consistent information to support analytics, customer services, supply-chain operations, and business intelligence. Integration tools that reduce manual data handling can improve productivity and limit errors. At the same time, organizations are placing greater emphasis on data quality, governance, and security. As information moves between platforms, businesses must maintain appropriate access controls and comply with relevant regulatory requirements. Open-source solutions and managed integration services are likely to provide additional opportunities, particularly for organizations seeking flexible deployment and specialist expertise. Get More Report Details: https://www.stellarmr.com/report/Data-Integration-Market/460 Segmentation Analysis According to the Stellar Market Research report, the Data Integration Market is segmented by component, deployment mode, and region. By Component: Tools Service Managed Services Professional Services The service segment held the leading position in 2024, accounting for 38.1% of the market. Demand is supported by the need for implementation expertise, efficient integration, and ongoing technical support. By Deployment Mode: On-Premises Cloud Cloud deployment dominated the market in 2024, representing 65.3% of the total. Its flexibility and ability to connect distributed applications make it an important choice for organizations modernizing their IT environments. By Region: North America Europe Asia Pacific Middle East and Africa South America Country-Level Analysis: USA and Germany United States: North America led the global Data Integration Market in 2024, with a 42.6% share. The United States benefits from established technology providers, investment in research and development, and demand from industries such as banking, retail, and financial services. Major companies including IBM, Microsoft, Oracle, Informatica, and Salesforce contribute to the competitive technology landscape. Continued cloud adoption and the need to connect enterprise applications are expected to support demand. Germany: Germany represents an important European market for data integration. The presence of enterprise technology providers such as SAP and Software AG supports the country's role in business software and integration solutions. Demand is associated with the need to connect enterprise systems, improve operational visibility, and manage information across complex business environments. The report includes Germany within its European regional coverage but does not provide a separate headline market valuation for the country. Competitive Analysis The Data Integration Market features established enterprise software companies and specialist solution providers competing through product development, cloud capabilities, interoperability, and service offerings. Key players identified by Stellar Market Research include IBM, Microsoft, SAP, Oracle, SAS Institute, Talend, Informatica, Precisely, Software AG, Salesforce, Qlik, TIBCO, Syncsort, Panoply, and Intel Corporation. Competition is shaped by the ability to integrate diverse data sources, support cloud and on-premises environments, and deliver reliable, scalable solutions. Providers offering flexible deployment, strong governance features, and managed services may be better positioned to meet the needs of organizations with increasingly complex data ecosystems. Download Free PDF Brochure: https://www.stellarmr.com/report/req_sample/Data-Integration-Market/460 Press Release Conclusion The Data Integration Market is set for substantial expansion as organizations prioritize cloud adoption, digital transformation, and effective enterprise data management. With the market projected to grow from USD 14.59 billion in 2024 to USD 34.19 billion by 2032, opportunities are emerging across integration tools, professional services, managed services, and cloud platforms. Although legacy-system complexity, skills shortages, and data standardization remain challenges, continued investment in automation, interoperability, and secure data exchange is expected to support long-term development. Businesses and technology providers that can simplify integration while maintaining data quality and governance will be well positioned to benefit from the market's growth. About Stellar Market Research: Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies. Contact Stellar Market Research: 3rd Floor, Navale IT Park, Phase 2 Pune Banglore Highway, Narhe, Pune, Maharashtra 411041, India [email protected] +91 20 6630 3320 | +91 9607365656
    0 Comments ·0 Shares ·89 Views
  • Surface Disinfectant Market Demand and Projected Industry Growth

    Surface Disinfectant Market to Reach USD 9.47 Billion by 2034 as Hygiene Standards and Product Innovation Accelerate

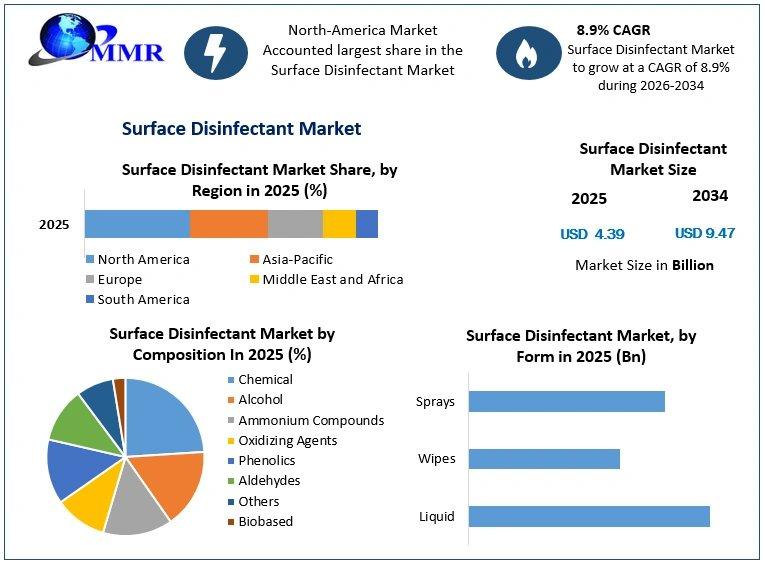
    The Surface Disinfectant Market is entering a sustained growth phase as healthcare facilities, households, hospitality businesses, and workplaces strengthen infection-control practices. According to Maximize Market Research, the market was valued at USD 4.39 billion in 2025 and is expected to grow at a CAGR of 8.9% from 2026 to 2034, reaching nearly USD 9.47 billion by 2034. Growth reflects increasing awareness of environmental hygiene, stringent sanitation requirements, rising healthcare activity, and product innovation.

    Market Estimation, Growth Drivers and Opportunities

    Demand is supported by infectious-disease concerns, higher healthcare utilization, growing numbers of surgeries, and greater attention to hygiene in high-contact environments. Hospitals and laboratories require reliable surface disinfection, while homes, schools, hotels, restaurants, offices, and food-processing sites adopt structured cleaning protocols.

    The market benefits from advances in formulation and delivery systems. Manufacturers are developing products with stronger antimicrobial performance, improved material compatibility, reduced odors, easier application, and more sustainable profiles. Electrostatic spraying, UV-C-assisted disinfection, ready-to-use wipes, concentrated liquids, and bio-based formulations create additional opportunities. Government support for hygiene programs and research can encourage investment.

    Request Your Sample Report Now : https://www.maximizemarketresearch.com/request-sample/33079/

    U.S. Market: Latest Trends and Investment

    The United States remains important because of healthcare expenditure, infection-prevention practices, consumer awareness, and commercial demand. In 2025, CloroxPro expanded its healthcare and commercial reach through a new agreement with Vizient to supply cleaning and disinfecting products. It also introduced Clorox Screen+ Sanitizing Wipes for touchscreens, laptops, tablets, and keyboards, showing how surface disinfection is expanding into technology-intensive workplaces.

    Reckitt continued strengthening Lysol’s U.S. innovation platform through new products and consumer education around proactive disinfection. Reckitt has also announced major U.S. investment in manufacturing, R&D, disinfection science, and innovation infrastructure. These developments point toward specialized and science-led hygiene solutions.

    Largest Market Segments

    By composition, the Chemical segment held the leading position, supported by widespread use of alcohols, ammonium compounds, oxidizing agents, phenolics, and aldehydes for microbial control.

    By form, Liquid surface disinfectants accounted for the leading share because they are widely used across hospitals, households, hotels, schools, commercial buildings, and other facilities.

    By application, In-House applications dominated, accounting for more than 73% of global revenue in 2022, according to the Maximize Market Research analysis. Broad use across facilities supports continued demand.

    Surface Disinfectant Market Demand and Projected Industry Growth Surface Disinfectant Market to Reach USD 9.47 Billion by 2034 as Hygiene Standards and Product Innovation Accelerate The Surface Disinfectant Market is entering a sustained growth phase as healthcare facilities, households, hospitality businesses, and workplaces strengthen infection-control practices. According to Maximize Market Research, the market was valued at USD 4.39 billion in 2025 and is expected to grow at a CAGR of 8.9% from 2026 to 2034, reaching nearly USD 9.47 billion by 2034. Growth reflects increasing awareness of environmental hygiene, stringent sanitation requirements, rising healthcare activity, and product innovation. Market Estimation, Growth Drivers and Opportunities Demand is supported by infectious-disease concerns, higher healthcare utilization, growing numbers of surgeries, and greater attention to hygiene in high-contact environments. Hospitals and laboratories require reliable surface disinfection, while homes, schools, hotels, restaurants, offices, and food-processing sites adopt structured cleaning protocols. The market benefits from advances in formulation and delivery systems. Manufacturers are developing products with stronger antimicrobial performance, improved material compatibility, reduced odors, easier application, and more sustainable profiles. Electrostatic spraying, UV-C-assisted disinfection, ready-to-use wipes, concentrated liquids, and bio-based formulations create additional opportunities. Government support for hygiene programs and research can encourage investment. Request Your Sample Report Now : https://www.maximizemarketresearch.com/request-sample/33079/ U.S. Market: Latest Trends and Investment The United States remains important because of healthcare expenditure, infection-prevention practices, consumer awareness, and commercial demand. In 2025, CloroxPro expanded its healthcare and commercial reach through a new agreement with Vizient to supply cleaning and disinfecting products. It also introduced Clorox Screen+ Sanitizing Wipes for touchscreens, laptops, tablets, and keyboards, showing how surface disinfection is expanding into technology-intensive workplaces. Reckitt continued strengthening Lysol’s U.S. innovation platform through new products and consumer education around proactive disinfection. Reckitt has also announced major U.S. investment in manufacturing, R&D, disinfection science, and innovation infrastructure. These developments point toward specialized and science-led hygiene solutions. Largest Market Segments By composition, the Chemical segment held the leading position, supported by widespread use of alcohols, ammonium compounds, oxidizing agents, phenolics, and aldehydes for microbial control. By form, Liquid surface disinfectants accounted for the leading share because they are widely used across hospitals, households, hotels, schools, commercial buildings, and other facilities. By application, In-House applications dominated, accounting for more than 73% of global revenue in 2022, according to the Maximize Market Research analysis. Broad use across facilities supports continued demand.
    0 Comments ·0 Shares ·434 Views
  • Paint Protection Film Market Demands and Projected Industry Growth

    Paint Protection Film Market to Reach USD 597.49 Million by 2032, Driven by Automotive Protection and Advanced Film Technologies

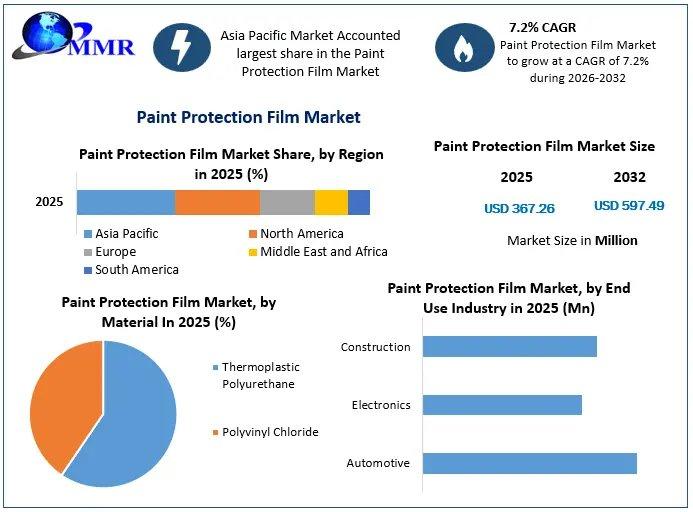
    The Paint Protection Film (PPF) Market is entering a sustained growth phase as vehicle owners, automotive manufacturers, dealerships, and professional detailing businesses increasingly adopt protective films to preserve vehicle appearance and reduce damage from road debris, scratches, stone chips, insects, and environmental exposure. According to Maximize Market Research, the global Paint Protection Film Market was valued at USD 367.26 million in 2025 and is projected to reach USD 597.49 million by 2032, expanding at a CAGR of 7.2% during 2026–2032.

    Market Estimation, Growth Drivers and Opportunities

    Paint Protection Film is primarily a thermoplastic urethane material applied to painted vehicle surfaces as a transparent or colored protective layer. Growing awareness of vehicle maintenance, rising demand for premium and luxury automobiles, increasing automotive production, and the need to preserve vehicle resale value are supporting market expansion.

    The availability of key raw materials, particularly Thermoplastic Polyurethane (TPU), is another important factor supporting production. TPU-based films offer characteristics including elasticity, self-healing capability, optical clarity, durability, non-yellowing performance, and recyclability. These properties are encouraging consumers to move from conventional protective solutions toward technologically advanced films.

    Get Your Complimentary Sample Report Today : https://www.maximizemarketresearch.com/request-sample/100882/

    Latest U.S. Market Trends and Investment

    The United States remains an important market for Paint Protection Film because of its large automotive aftermarket, established installer network, strong demand for premium vehicles, and growing consumer awareness of vehicle preservation. In 2025, U.S. industry activity increasingly focused on advanced PPF products, dealership adoption, customization, and installation technologies. XPEL reported that its paint protection film sales increased 10% in 2025, while the company also recorded growth in the U.S., its largest market. The company expanded its international strategy and continued investment in next-generation protective film technologies.

    Market Segmentation: Largest Market Share

    By material, Thermoplastic Polyurethane (TPU) held the largest market share in 2025. Its self-healing properties, elasticity, clarity, non-yellowing characteristics, recyclability, and durability are major factors supporting its adoption.

    By end-use industry, Automotive dominated the market, accounting for more than 80% of global revenue in 2025. Rising passenger and commercial vehicle demand, increasing vehicle ownership, growing awareness of vehicle maintenance, and expanding premium automobile sales continue to support this segment.

    Paint Protection Film Market Demands and Projected Industry Growth Paint Protection Film Market to Reach USD 597.49 Million by 2032, Driven by Automotive Protection and Advanced Film Technologies The Paint Protection Film (PPF) Market is entering a sustained growth phase as vehicle owners, automotive manufacturers, dealerships, and professional detailing businesses increasingly adopt protective films to preserve vehicle appearance and reduce damage from road debris, scratches, stone chips, insects, and environmental exposure. According to Maximize Market Research, the global Paint Protection Film Market was valued at USD 367.26 million in 2025 and is projected to reach USD 597.49 million by 2032, expanding at a CAGR of 7.2% during 2026–2032. Market Estimation, Growth Drivers and Opportunities Paint Protection Film is primarily a thermoplastic urethane material applied to painted vehicle surfaces as a transparent or colored protective layer. Growing awareness of vehicle maintenance, rising demand for premium and luxury automobiles, increasing automotive production, and the need to preserve vehicle resale value are supporting market expansion. The availability of key raw materials, particularly Thermoplastic Polyurethane (TPU), is another important factor supporting production. TPU-based films offer characteristics including elasticity, self-healing capability, optical clarity, durability, non-yellowing performance, and recyclability. These properties are encouraging consumers to move from conventional protective solutions toward technologically advanced films. Get Your Complimentary Sample Report Today : https://www.maximizemarketresearch.com/request-sample/100882/ Latest U.S. Market Trends and Investment The United States remains an important market for Paint Protection Film because of its large automotive aftermarket, established installer network, strong demand for premium vehicles, and growing consumer awareness of vehicle preservation. In 2025, U.S. industry activity increasingly focused on advanced PPF products, dealership adoption, customization, and installation technologies. XPEL reported that its paint protection film sales increased 10% in 2025, while the company also recorded growth in the U.S., its largest market. The company expanded its international strategy and continued investment in next-generation protective film technologies. Market Segmentation: Largest Market Share By material, Thermoplastic Polyurethane (TPU) held the largest market share in 2025. Its self-healing properties, elasticity, clarity, non-yellowing characteristics, recyclability, and durability are major factors supporting its adoption. By end-use industry, Automotive dominated the market, accounting for more than 80% of global revenue in 2025. Rising passenger and commercial vehicle demand, increasing vehicle ownership, growing awareness of vehicle maintenance, and expanding premium automobile sales continue to support this segment.
    0 Comments ·0 Shares ·217 Views
  • Tin Market Size, Growth Drivers, Demand and Revenue Forecast

    Tin Market to Reach USD 9.57 Billion by 2032 as Electronics, EVs, Renewable Energy, and Supply-Chain Diversification Accelerate Demand

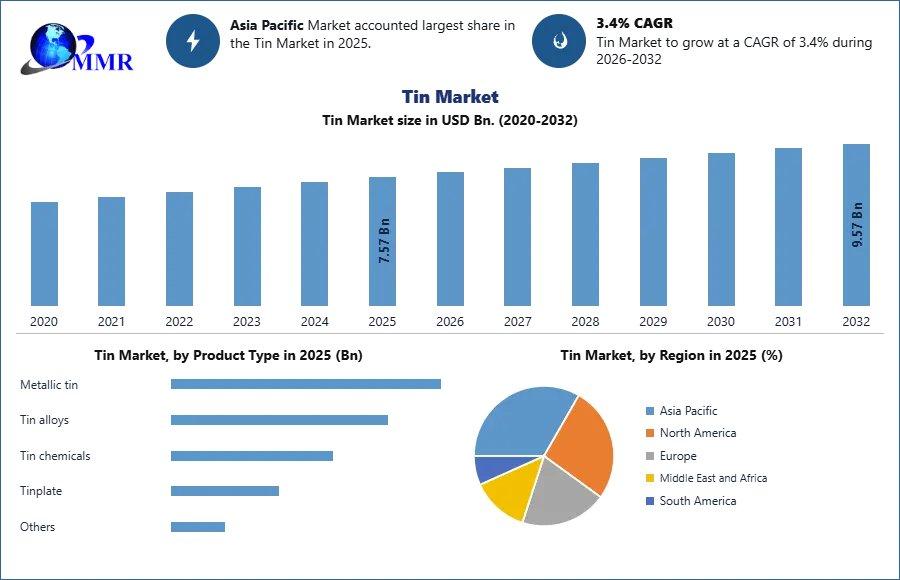
    The Tin Market is entering a period of sustained expansion as demand for electronics, semiconductors, electric vehicles, renewable energy systems, advanced soldering materials, and tin-based chemicals continues to rise. According to Maximize Market Research, the global Tin Market was valued at USD 7.57 billion in 2025 and is projected to reach nearly USD 9.57 billion by 2032, expanding at a CAGR of 3.4% from 2026 to 2032.

    Market Estimation, Growth Drivers and Opportunities

    Tin has become an increasingly strategic industrial material because of its combination of electrical conductivity, corrosion resistance, malleability, and compatibility with advanced manufacturing processes. The strongest demand is coming from electronics and semiconductor manufacturing, where tin-based solder is essential for printed circuit boards, component assembly, power electronics, and miniaturized electronic devices.

    The expansion of electric mobility is creating another important demand center. Tin-based materials are increasingly utilized in EV power electronics, battery-related components, thermal management systems, and precision soldering. At the same time, renewable-energy installations, including solar power systems, require tin-containing materials for electrical connections and soldering applications.

    Supply-chain uncertainty is also changing the structure of the industry. Disruptions affecting major producing regions have encouraged manufacturers and governments to pursue diversified sourcing, recycling, traceability, and domestic processing capabilities. Recycled tin is therefore becoming strategically important, while electronic-waste recovery and urban mining technologies offer opportunities to improve secondary supply.

    Material innovation represents another long-term opportunity. Tin-based battery anodes, lead-free solder alloys, advanced tin chemicals, and tin-based materials for next-generation solar technologies could expand the metal's role beyond traditional applications. AI-enabled smelting, automated ore sorting, digital grade monitoring, and blockchain-supported traceability can further improve efficiency and responsible sourcing.

    Request Your Sample Report Now : https://www.maximizemarketresearch.com/request-sample/57921/

    U.S. Market Trends and Investment Outlook

    The United States is experiencing growing strategic interest in minerals and materials needed for electronics, semiconductors, energy technologies, and advanced manufacturing. During 2025, the U.S. government strengthened its focus on mineral supply-chain security, including measures intended to encourage domestic mineral production, processing, recycling, and investment. The U.S. Department of the Interior's draft 2025 Critical Minerals List was designed to guide federal strategy, investment, permitting, and resource-recovery decisions. Meanwhile, substantial private investment in the U.S. semiconductor ecosystem is increasing the country's need for reliable supplies of high-performance electronic materials. These developments create opportunities for tin suppliers, refiners, recyclers, and advanced solder-material manufacturers.

    Market Segmentation: Leading Segments

    Based on Product Type, Metallic Tin dominated the Tin Market in 2025, accounting for more than 55% of total market revenue. Its extensive use in solder production, tin plating, semiconductor assembly, automotive electronics, and high-purity industrial applications supports its leading position.

    Based on Application, Soldering represented the largest segment in 2025, contributing more than 50% of global tin consumption. The segment benefits from expanding electronics production, semiconductor manufacturing, EV power electronics, PCB assembly, and solar-energy applications. The continued transition toward lead-free soldering is expected to reinforce demand for refined tin and specialized tin alloys.

    Tin Market Size, Growth Drivers, Demand and Revenue Forecast Tin Market to Reach USD 9.57 Billion by 2032 as Electronics, EVs, Renewable Energy, and Supply-Chain Diversification Accelerate Demand The Tin Market is entering a period of sustained expansion as demand for electronics, semiconductors, electric vehicles, renewable energy systems, advanced soldering materials, and tin-based chemicals continues to rise. According to Maximize Market Research, the global Tin Market was valued at USD 7.57 billion in 2025 and is projected to reach nearly USD 9.57 billion by 2032, expanding at a CAGR of 3.4% from 2026 to 2032. Market Estimation, Growth Drivers and Opportunities Tin has become an increasingly strategic industrial material because of its combination of electrical conductivity, corrosion resistance, malleability, and compatibility with advanced manufacturing processes. The strongest demand is coming from electronics and semiconductor manufacturing, where tin-based solder is essential for printed circuit boards, component assembly, power electronics, and miniaturized electronic devices. The expansion of electric mobility is creating another important demand center. Tin-based materials are increasingly utilized in EV power electronics, battery-related components, thermal management systems, and precision soldering. At the same time, renewable-energy installations, including solar power systems, require tin-containing materials for electrical connections and soldering applications. Supply-chain uncertainty is also changing the structure of the industry. Disruptions affecting major producing regions have encouraged manufacturers and governments to pursue diversified sourcing, recycling, traceability, and domestic processing capabilities. Recycled tin is therefore becoming strategically important, while electronic-waste recovery and urban mining technologies offer opportunities to improve secondary supply. Material innovation represents another long-term opportunity. Tin-based battery anodes, lead-free solder alloys, advanced tin chemicals, and tin-based materials for next-generation solar technologies could expand the metal's role beyond traditional applications. AI-enabled smelting, automated ore sorting, digital grade monitoring, and blockchain-supported traceability can further improve efficiency and responsible sourcing. Request Your Sample Report Now : https://www.maximizemarketresearch.com/request-sample/57921/ U.S. Market Trends and Investment Outlook The United States is experiencing growing strategic interest in minerals and materials needed for electronics, semiconductors, energy technologies, and advanced manufacturing. During 2025, the U.S. government strengthened its focus on mineral supply-chain security, including measures intended to encourage domestic mineral production, processing, recycling, and investment. The U.S. Department of the Interior's draft 2025 Critical Minerals List was designed to guide federal strategy, investment, permitting, and resource-recovery decisions. Meanwhile, substantial private investment in the U.S. semiconductor ecosystem is increasing the country's need for reliable supplies of high-performance electronic materials. These developments create opportunities for tin suppliers, refiners, recyclers, and advanced solder-material manufacturers. Market Segmentation: Leading Segments Based on Product Type, Metallic Tin dominated the Tin Market in 2025, accounting for more than 55% of total market revenue. Its extensive use in solder production, tin plating, semiconductor assembly, automotive electronics, and high-purity industrial applications supports its leading position. Based on Application, Soldering represented the largest segment in 2025, contributing more than 50% of global tin consumption. The segment benefits from expanding electronics production, semiconductor manufacturing, EV power electronics, PCB assembly, and solar-energy applications. The continued transition toward lead-free soldering is expected to reinforce demand for refined tin and specialized tin alloys.
    0 Comments ·0 Shares ·584 Views
  • Asia Pacific Biochar Market Growth, Trends, Opportunities and Forecast 2023–2029
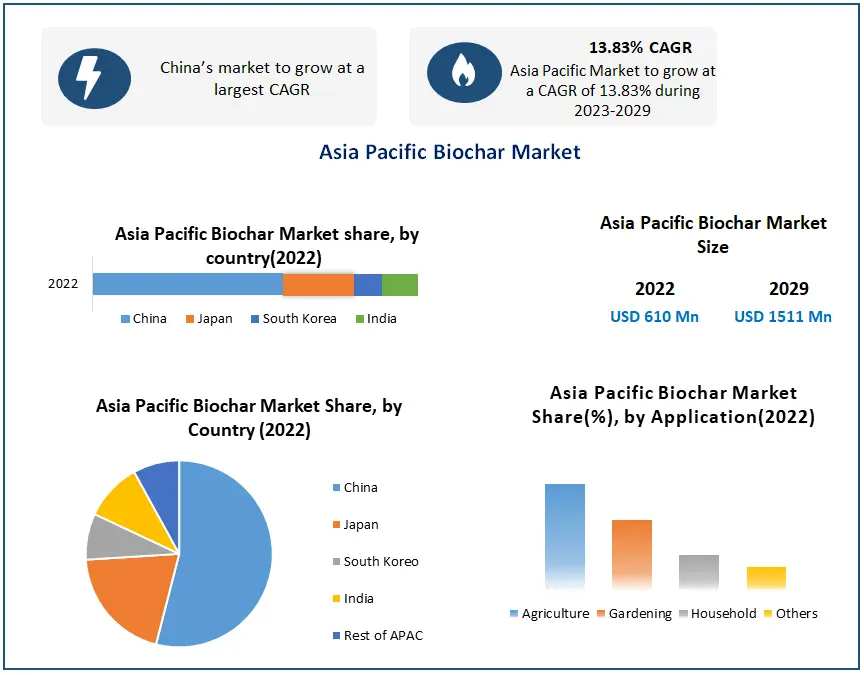
    The Asia Pacific Biochar Market was valued at USD 610 million in 2022 and is projected to grow at a CAGR of 13.83% from 2023 to 2029, reaching approximately USD 1,511 million by 2029. The market is gaining momentum as agriculture, waste management, and sustainable farming practices increasingly adopt biochar as an environmentally beneficial material.

    Asia Pacific Biochar Market Overview
    Biochar is increasingly being recognized across the Asia Pacific region for its applications in agriculture, gardening, waste management, and other end-use sectors. Strong environmental regulations, growing demand from end-user industries, increasing organic farming, and the use of biochar in waste management are among the major factors supporting market expansion.

    The agriculture sector represents a major area of demand for biochar. The material can be produced from different forms of biomass and agricultural waste, providing an opportunity to convert waste into a value-added resource. Pyrolysis remains one of the leading production methods and accounts for a significant share of the market.

    Request Free Sample Copy:https://www.maximizemarketresearch.com/request-sample/20189/

    Key Growth Drivers
    Rising Demand for Organic Farming
    The increasing adoption of organic farming and sustainable agricultural practices is creating significant demand for biochar. Farmers and agricultural businesses are increasingly exploring solutions that can support soil health while reducing dependence on conventional chemical fertilizers.

    Biochar also provides an opportunity to utilize agricultural and organic waste that would otherwise require disposal. Crop residues, biomass, and animal manure can be converted into biochar, creating an additional value stream from agricultural waste.

    Growing Importance of Waste Management
    The Asia Pacific region generates substantial quantities of agricultural and organic waste. Biochar production offers a method of converting some of these waste materials into useful products while reducing waste volumes.

    The combination of waste management and biochar production is therefore becoming increasingly relevant to governments, agricultural businesses, and sustainability-focused organizations.

    Environmental Regulations
    Stricter environmental regulations are also supporting market development. Governments and industries are looking for alternatives that can contribute to sustainable resource management and reduce environmental impacts.

    Market Restraints
    High Initial Investment
    The establishment of biochar production facilities and implementation of associated technologies can require significant upfront investment. High initial costs may discourage new entrants and investors, particularly in areas where financial resources and production infrastructure are limited.

    Lack of Awareness
    Limited awareness among farmers and consumers regarding the benefits and applications of biochar remains another challenge. Greater education and stakeholder awareness are needed to accelerate adoption across developing markets in the region.

    Market Opportunities
    Sustainable Agriculture
    Increasing awareness of sustainable agriculture presents an important opportunity for the Asia Pacific Biochar Market. Biochar can be incorporated into agricultural practices aimed at improving soil health and reducing dependence on chemical fertilizers.

    Growing consumer interest in environmentally friendly agricultural products may further encourage farmers to explore biochar-based solutions.

    Integration with Waste-to-Energy
    The region's large volume of agricultural and organic waste provides an opportunity to integrate biochar production with bioenergy and waste-to-energy processes. Such integration can enable the utilization of waste resources while creating value-added products.

    Government subsidies, incentives, and favorable regulations could further encourage investment in biochar production and sustainable agricultural practices.

    Asia Pacific Biochar Market Segmentation
    The market is segmented based on application, technology, manufacturing, and feedstock. Agriculture is a major application segment, while pyrolysis represents an important manufacturing process.

    By Technology
    Pyrolysis has dominated the market and is expected to maintain its leading position during the forecast period. It is a widely used thermochemical process in which biomass is heated in the absence of oxygen to produce biochar, bio-oil, and syngas.

    Gasification is another production method. In this process, biomass is oxidized to generate syngas, which can subsequently be processed to produce biochar.

    By Feedstock
    The Agricultural Waste segment holds a significant market share and is expected to remain dominant. Common agricultural feedstocks include rice straw, wheat straw, corn stalks, nutshells, and other biomass residues.

    Animal manure, including cow dung, swine dung, and poultry litter, is also used as a feedstock for biochar production.

    By Application
    The market covers:

    Agriculture
    Gardening
    Household
    Others
    By Manufacturing
    Gasification
    Pyrolysis
    Others
    By Feedstock
    Woody Biomass
    Agricultural Waste
    Animal Manure
    Others
    Request Free Sample Copy:https://www.maximizemarketresearch.com/request-sample/20189/

    Country Analysis
    China is the leading country in the Asia Pacific Biochar Market, accounting for approximately 95% of the regional market in 2022, according to the provided source. Chinese players are investing in research and development to understand biochar's effects on soil processes, agricultural productivity, and environmental conditions.

    Japan is also active in biochar research, particularly in understanding its physical, chemical, and biological properties and its effects on soil and compost. The broader Asia Pacific region is expected to experience strong growth, supported by pilot projects and increasing consumer adoption.

    The countries covered include China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan, and Rest of APAC.

    Asia Pacific Biochar Market Forecast
    Market Indicator Details
    Base Year 2022
    Historical Period 2018–2022
    Forecast Period 2023–2029
    Market Size in 2022 USD 610 Million
    CAGR 13.83%
    Market Size in 2029 USD 1,511 Million
    Key Application Agriculture
    Leading Manufacturing Process Pyrolysis
    Key Feedstock Agricultural Waste
    The market is expected to benefit from rising demand for sustainable agriculture, increasing organic waste generation, environmental regulations, and the growing integration of biochar with waste management and bioenergy systems.

    Competitive Landscape
    The Asia Pacific Biochar Market includes established companies and emerging participants involved in biochar production, pyrolysis technologies, biomass utilization, and sustainable resource management.

    Key players identified in the source include Biogreen-Energy, Agri-Tech Producers LLC, Genesis Industries, Diacarbon Energy Inc., Green Charcoal International, Vega Biofuels Inc., The Biochar Company, Cool Planet Energy Systems Inc., Full Circle Biochar, Pacific Pyrolysis Pty Ltd, ARSTA Eco, Earth Systems, Guangdong Dazhong Agricultural Science and Technology Co. Ltd, Rainbow Bee Eater and Pacific Pyrolysis, Biochar Now LLC, Tolero Energy, Airex Energy, Carbon Gold, Phoenix Energy, and AirTerra.

    Future Outlook
    The Asia Pacific Biochar Market has considerable growth potential as the region moves toward more sustainable agricultural and waste-management practices. Increasing awareness of soil health, organic farming, agricultural waste utilization, and environmentally responsible production is expected to support adoption.

    At the same time, reducing production costs, improving infrastructure, increasing stakeholder awareness, and introducing supportive government policies will be important for overcoming current market barriers.

    Overall, the market's projected growth from USD 610 million in 2022 to USD 1,511 million by 2029 highlights the expanding role of biochar in sustainable agriculture and resource management across Asia Pacific.
    Asia Pacific Biochar Market Growth, Trends, Opportunities and Forecast 2023–2029 The Asia Pacific Biochar Market was valued at USD 610 million in 2022 and is projected to grow at a CAGR of 13.83% from 2023 to 2029, reaching approximately USD 1,511 million by 2029. The market is gaining momentum as agriculture, waste management, and sustainable farming practices increasingly adopt biochar as an environmentally beneficial material. Asia Pacific Biochar Market Overview Biochar is increasingly being recognized across the Asia Pacific region for its applications in agriculture, gardening, waste management, and other end-use sectors. Strong environmental regulations, growing demand from end-user industries, increasing organic farming, and the use of biochar in waste management are among the major factors supporting market expansion. The agriculture sector represents a major area of demand for biochar. The material can be produced from different forms of biomass and agricultural waste, providing an opportunity to convert waste into a value-added resource. Pyrolysis remains one of the leading production methods and accounts for a significant share of the market. Request Free Sample Copy:https://www.maximizemarketresearch.com/request-sample/20189/ Key Growth Drivers Rising Demand for Organic Farming The increasing adoption of organic farming and sustainable agricultural practices is creating significant demand for biochar. Farmers and agricultural businesses are increasingly exploring solutions that can support soil health while reducing dependence on conventional chemical fertilizers. Biochar also provides an opportunity to utilize agricultural and organic waste that would otherwise require disposal. Crop residues, biomass, and animal manure can be converted into biochar, creating an additional value stream from agricultural waste. Growing Importance of Waste Management The Asia Pacific region generates substantial quantities of agricultural and organic waste. Biochar production offers a method of converting some of these waste materials into useful products while reducing waste volumes. The combination of waste management and biochar production is therefore becoming increasingly relevant to governments, agricultural businesses, and sustainability-focused organizations. Environmental Regulations Stricter environmental regulations are also supporting market development. Governments and industries are looking for alternatives that can contribute to sustainable resource management and reduce environmental impacts. Market Restraints High Initial Investment The establishment of biochar production facilities and implementation of associated technologies can require significant upfront investment. High initial costs may discourage new entrants and investors, particularly in areas where financial resources and production infrastructure are limited. Lack of Awareness Limited awareness among farmers and consumers regarding the benefits and applications of biochar remains another challenge. Greater education and stakeholder awareness are needed to accelerate adoption across developing markets in the region. Market Opportunities Sustainable Agriculture Increasing awareness of sustainable agriculture presents an important opportunity for the Asia Pacific Biochar Market. Biochar can be incorporated into agricultural practices aimed at improving soil health and reducing dependence on chemical fertilizers. Growing consumer interest in environmentally friendly agricultural products may further encourage farmers to explore biochar-based solutions. Integration with Waste-to-Energy The region's large volume of agricultural and organic waste provides an opportunity to integrate biochar production with bioenergy and waste-to-energy processes. Such integration can enable the utilization of waste resources while creating value-added products. Government subsidies, incentives, and favorable regulations could further encourage investment in biochar production and sustainable agricultural practices. Asia Pacific Biochar Market Segmentation The market is segmented based on application, technology, manufacturing, and feedstock. Agriculture is a major application segment, while pyrolysis represents an important manufacturing process. By Technology Pyrolysis has dominated the market and is expected to maintain its leading position during the forecast period. It is a widely used thermochemical process in which biomass is heated in the absence of oxygen to produce biochar, bio-oil, and syngas. Gasification is another production method. In this process, biomass is oxidized to generate syngas, which can subsequently be processed to produce biochar. By Feedstock The Agricultural Waste segment holds a significant market share and is expected to remain dominant. Common agricultural feedstocks include rice straw, wheat straw, corn stalks, nutshells, and other biomass residues. Animal manure, including cow dung, swine dung, and poultry litter, is also used as a feedstock for biochar production. By Application The market covers: Agriculture Gardening Household Others By Manufacturing Gasification Pyrolysis Others By Feedstock Woody Biomass Agricultural Waste Animal Manure Others Request Free Sample Copy:https://www.maximizemarketresearch.com/request-sample/20189/ Country Analysis China is the leading country in the Asia Pacific Biochar Market, accounting for approximately 95% of the regional market in 2022, according to the provided source. Chinese players are investing in research and development to understand biochar's effects on soil processes, agricultural productivity, and environmental conditions. Japan is also active in biochar research, particularly in understanding its physical, chemical, and biological properties and its effects on soil and compost. The broader Asia Pacific region is expected to experience strong growth, supported by pilot projects and increasing consumer adoption. The countries covered include China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan, and Rest of APAC. Asia Pacific Biochar Market Forecast Market Indicator Details Base Year 2022 Historical Period 2018–2022 Forecast Period 2023–2029 Market Size in 2022 USD 610 Million CAGR 13.83% Market Size in 2029 USD 1,511 Million Key Application Agriculture Leading Manufacturing Process Pyrolysis Key Feedstock Agricultural Waste The market is expected to benefit from rising demand for sustainable agriculture, increasing organic waste generation, environmental regulations, and the growing integration of biochar with waste management and bioenergy systems. Competitive Landscape The Asia Pacific Biochar Market includes established companies and emerging participants involved in biochar production, pyrolysis technologies, biomass utilization, and sustainable resource management. Key players identified in the source include Biogreen-Energy, Agri-Tech Producers LLC, Genesis Industries, Diacarbon Energy Inc., Green Charcoal International, Vega Biofuels Inc., The Biochar Company, Cool Planet Energy Systems Inc., Full Circle Biochar, Pacific Pyrolysis Pty Ltd, ARSTA Eco, Earth Systems, Guangdong Dazhong Agricultural Science and Technology Co. Ltd, Rainbow Bee Eater and Pacific Pyrolysis, Biochar Now LLC, Tolero Energy, Airex Energy, Carbon Gold, Phoenix Energy, and AirTerra. Future Outlook The Asia Pacific Biochar Market has considerable growth potential as the region moves toward more sustainable agricultural and waste-management practices. Increasing awareness of soil health, organic farming, agricultural waste utilization, and environmentally responsible production is expected to support adoption. At the same time, reducing production costs, improving infrastructure, increasing stakeholder awareness, and introducing supportive government policies will be important for overcoming current market barriers. Overall, the market's projected growth from USD 610 million in 2022 to USD 1,511 million by 2029 highlights the expanding role of biochar in sustainable agriculture and resource management across Asia Pacific.
    0 Comments ·0 Shares ·410 Views
  • School Management System: Enhancing Educational Administration

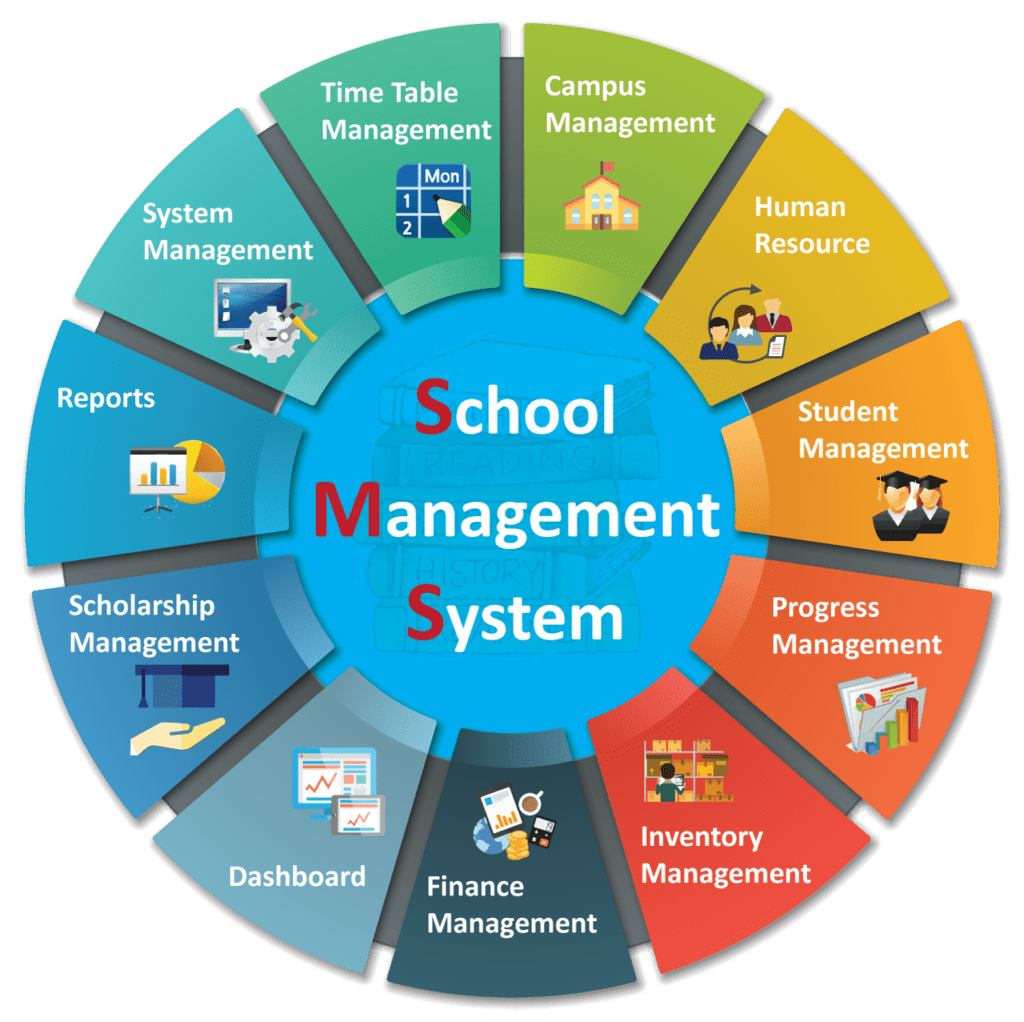
    A school management system is a comprehensive software solution designed to streamline, automate, and improve administrative tasks within educational institutions. From small private schools to large public education systems, this technology helps manage daily operations efficiently. With features like attendance tracking, timetable creation, fee management, and communication tools, a school management system ensures accuracy and saves valuable time for teachers and administrators. By integrating various school functions into one platform, these systems provide a centralized database, making data access easy, secure, and organized. This digital transformation not only reduces paperwork but also enhances the productivity of school staff, contributing to the institution's overall success.

    Source - https://www.marketresearchfuture.com/reports/school-management-system-market-8398

    In today’s tech-driven world, a school management system plays a critical role in promoting transparency between schools and parents. Parents can stay informed about their child's performance, attendance, and activities through parent portals or mobile apps linked with the system. Additionally, school management software often includes features for online examination, report card generation, library management, and even hostel and transportation management. Such integrated tools ensure that schools can focus more on delivering quality education while the system handles administrative burdens. As a result, institutions adopting school management systems often witness improved communication, better resource management, and enhanced educational outcomes.

    A school management system comes equipped with a variety of essential features that cater to every aspect of school administration. One of the standout features is student information management, where all details, from admission records to academic progress, are stored securely and can be retrieved with ease. Attendance management is another core component, offering digital attendance tracking that reduces errors and manual effort. Teachers can mark attendance online, and parents receive instant notifications of their child's presence or absence.

    Financial management is equally important, and a school management system simplifies tasks such as fee collection, invoicing, and accounting. The system can automate reminders for due fees and generate financial reports, ensuring transparency in transactions. Timetable and scheduling features enable administrators to design and distribute class schedules without conflicts. Additionally, these systems support examination management by generating exam timetables, recording marks, and creating report cards, all while maintaining data security and integrity. These comprehensive features help schools operate smoothly and focus on core educational goals.
    School Management System: Enhancing Educational Administration A school management system is a comprehensive software solution designed to streamline, automate, and improve administrative tasks within educational institutions. From small private schools to large public education systems, this technology helps manage daily operations efficiently. With features like attendance tracking, timetable creation, fee management, and communication tools, a school management system ensures accuracy and saves valuable time for teachers and administrators. By integrating various school functions into one platform, these systems provide a centralized database, making data access easy, secure, and organized. This digital transformation not only reduces paperwork but also enhances the productivity of school staff, contributing to the institution's overall success. Source - https://www.marketresearchfuture.com/reports/school-management-system-market-8398 In today’s tech-driven world, a school management system plays a critical role in promoting transparency between schools and parents. Parents can stay informed about their child's performance, attendance, and activities through parent portals or mobile apps linked with the system. Additionally, school management software often includes features for online examination, report card generation, library management, and even hostel and transportation management. Such integrated tools ensure that schools can focus more on delivering quality education while the system handles administrative burdens. As a result, institutions adopting school management systems often witness improved communication, better resource management, and enhanced educational outcomes. A school management system comes equipped with a variety of essential features that cater to every aspect of school administration. One of the standout features is student information management, where all details, from admission records to academic progress, are stored securely and can be retrieved with ease. Attendance management is another core component, offering digital attendance tracking that reduces errors and manual effort. Teachers can mark attendance online, and parents receive instant notifications of their child's presence or absence. Financial management is equally important, and a school management system simplifies tasks such as fee collection, invoicing, and accounting. The system can automate reminders for due fees and generate financial reports, ensuring transparency in transactions. Timetable and scheduling features enable administrators to design and distribute class schedules without conflicts. Additionally, these systems support examination management by generating exam timetables, recording marks, and creating report cards, all while maintaining data security and integrity. These comprehensive features help schools operate smoothly and focus on core educational goals.
    0 Comments ·0 Shares ·1K Views